Banner Template

Inflation Is Rising Again. What Does It Actually Mean for Your Money?

After several months of encouraging news, UK inflation has begun to edge upwards again.

The latest figures show the Consumer Prices Index (CPI) rose to 2.9% in July, up from 2.6% in June. Much of the increase has been driven by higher household energy bills following a rise in the energy price cap, itself linked to higher wholesale energy prices after recent tensions in the Middle East.

For many people, hearing that “inflation is rising” immediately brings back memories of the cost of living crisis.

But does this latest increase mean we’re heading back to those levels of inflation?

Not necessarily.

What Is Inflation?

Inflation measures how quickly the prices of goods and services are increasing over time.

If inflation is running at 2.9%, something that cost £100 a year ago would, on average, now cost £102.90.

The Bank of England’s target is 2%, which is generally considered a healthy level that supports economic growth without allowing prices to rise too quickly.

While the latest figure is above that target, it remains well below the levels experienced during the inflation surge of 2022 and 2023.

Why Has Inflation Increased?

The biggest factor this time is energy.

Higher wholesale gas prices have fed through into household bills following a 13% increase in the energy price cap in July. Energy costs affect almost every part of the economy, from heating our homes to transporting goods around the country, so increases can have a wider knock-on effect on prices.

There were also smaller contributions from areas such as furniture and clothing, where seasonal discounts were less pronounced than usual.

The important point is that this rise has been driven largely by external factors rather than a broad-based surge in domestic demand.

What Could It Mean for Interest Rates?

Whenever inflation rises, attention quickly turns to the Bank of England.

Higher inflation can sometimes lead to higher interest rates as policymakers try to slow spending and bring price growth back under control.

However, the picture is more balanced than it first appears.

Although headline inflation has increased, core inflation remained at 2.6%, while wage growth has continued to slow and the labour market has shown signs of cooling. In its latest Monetary Policy Report, the Bank of England said there were “clear signs of underlying disinflation” and “little evidence so far” that higher energy prices had led to broader inflationary pressures. As a result, many economists believe the Bank may not need to respond as aggressively as it did during the previous inflation spike.

What Does This Mean for Households?

For most households, the immediate impact is likely to be felt through higher energy bills and continued pressure on everyday living costs.

However, it’s worth remembering that inflation affects everyone differently.

Someone who spends more on travel or energy may notice the increase more than someone whose spending is concentrated elsewhere.

While individual prices will continue to rise and fall, it is usually long-term trends rather than month-to-month movements that matter most when making financial decisions.

Staying Focused on the Long Term

Inflation is one of those economic indicators that naturally attracts headlines.

But history shows that it moves in cycles.

There will always be periods when inflation rises and periods when it falls. Trying to make significant financial decisions based on a single month’s data rarely proves beneficial.

Instead, it is often more helpful to focus on the things you can control:

  • reviewing your household budget;
  • maintaining appropriate emergency savings;
  • ensuring your investments remain aligned with your long-term objectives; and
  • reviewing your financial plan regularly as circumstances change.

Final Thoughts

The latest inflation figures are a reminder that economic conditions continue to evolve.

While rising prices are never welcome, today’s environment looks very different from the inflation shock experienced just a few years ago.

For most people, the best approach remains the same: understand what is changing, avoid reacting to short-term headlines and keep your long-term financial plan under regular review.
cookie

Why Good Financial Habits Should Require Less Willpower

Most of us know roughly what we should be doing with our money.

Pay the bills on time. Build an emergency fund. Save regularly. Contribute towards retirement. Put money aside for larger annual costs.

The difficult part is doing all of those things consistently while managing work, family and everything else competing for our attention.

This is where financial automation can be particularly useful. By arranging for certain decisions to happen automatically, we can reduce the amount of time, effort and willpower required to stay on track.

The aim is not to remove all thought from managing money. It is to make sensible financial habits the default, rather than something we have to remember to do every month.

Why Willpower Is Not Always Enough

It is easy to assume that good money management is simply a matter of discipline.

In reality, even the most organised people can forget a payment, postpone transferring money into savings or gradually spend what remains in their account before reaching the end of the month.

Every financial decision requires a small amount of mental effort. Individually, those decisions may feel insignificant, but together they can contribute to what is sometimes called decision fatigue.

Automation reduces the number of decisions we need to make repeatedly. Once an appropriate system has been established, it can continue working quietly in the background.

Instead of deciding each month whether to save, the money moves automatically. Instead of hoping enough remains for an annual insurance premium or family holiday, a smaller amount can be set aside throughout the year.

The Power of Making Something the Default

One of the clearest demonstrations of this principle can be found in workplace pensions.

Before automatic enrolment, employees generally had to make an active decision to join a workplace pension. Many did not, even where saving for retirement would have been beneficial.

Automatic enrolment changed the starting position. Eligible employees were placed into a pension unless they chose to leave, making long-term saving the default rather than an additional task.

In 2024, 89% of eligible employees in Great Britain were saving into a workplace pension. It is a powerful example of how changing the system around a decision can sometimes have a greater effect than repeatedly asking people to make the right choice.

The same principle can be applied to other areas of personal finance.

Paying Yourself First

Many people intend to save whatever is left at the end of the month.

The difficulty is that there is not always very much left.

An alternative is to arrange for money to move into savings shortly after income arrives. This is sometimes described as paying yourself first.

The amount does not need to be large. What matters initially is creating a regular habit that reflects what you can genuinely afford.

Over time, automated contributions can help build an emergency fund, prepare for a specific purchase or support a longer-term goal. They also place the money slightly further out of reach, reducing the temptation to spend it impulsively.

Preparing for the Costs That Do Not Arrive Monthly

Not every expense fits neatly into a monthly budget.

Christmas, holidays, car maintenance, insurance renewals and home repairs can all feel unexpected, despite being reasonably predictable.

Creating separate savings pots and making regular transfers into them can turn one large future bill into a series of smaller, more manageable amounts.

This does not necessarily reduce the overall cost, but it can reduce the financial shock when payment is due.

It can also make spending more enjoyable. A holiday paid for from money deliberately set aside may feel very different from one followed by several months of credit card repayments.

Automating Long-Term Saving and Investing

Regular contributions can also support longer-term financial planning.

Making contributions at set intervals removes the pressure of trying to identify the perfect moment to invest. Markets will naturally rise and fall, and regular investing means money is added across a range of different market conditions.

However, investments can fall as well as rise, and regular contributions do not guarantee a positive return. The amount invested, the level of risk and the investments selected should remain appropriate for your circumstances and goals.

Automation should support a considered financial plan, not replace one.

Making More of a Pay Rise

A pay rise is another point at which automation can be useful.

As income increases, spending often rises with it. This is sometimes known as lifestyle inflation. It may happen gradually, without us consciously deciding to change how we live.

Before becoming accustomed to the full increase, some people choose to direct a proportion of it towards savings, pensions or investments.

That still leaves room to enjoy the benefits of earning more, while also using part of the increase to strengthen future financial security.

What Should Not Be Left on Autopilot?

Automation can be helpful, but it should not mean ignoring your finances completely.

Direct Debits can continue long after a service has stopped providing value. Savings accounts can become uncompetitive. Insurance policies may no longer reflect your needs, and investment arrangements should be reviewed as circumstances and objectives change.

Credit card payments also require particular care. Automatically paying only the minimum amount can keep an account technically up to date while allowing interest and debt to build over time.

A sensible approach is to automate the regular activity, then review the wider arrangements periodically.

Think of it less as switching your finances off and more as installing a system that still requires occasional maintenance.

Small Systems, Repeated Over Time

Financial progress rarely comes from one dramatic decision.

More often, it is the result of small actions repeated consistently over many years.

Automating bills, savings and long-term contributions cannot remove every financial concern. Nor can it compensate for a budget that is already stretched beyond what is affordable.

But where there is room to save, it can make positive habits easier to maintain and reduce the likelihood that important goals are continually postponed.

Banner Template

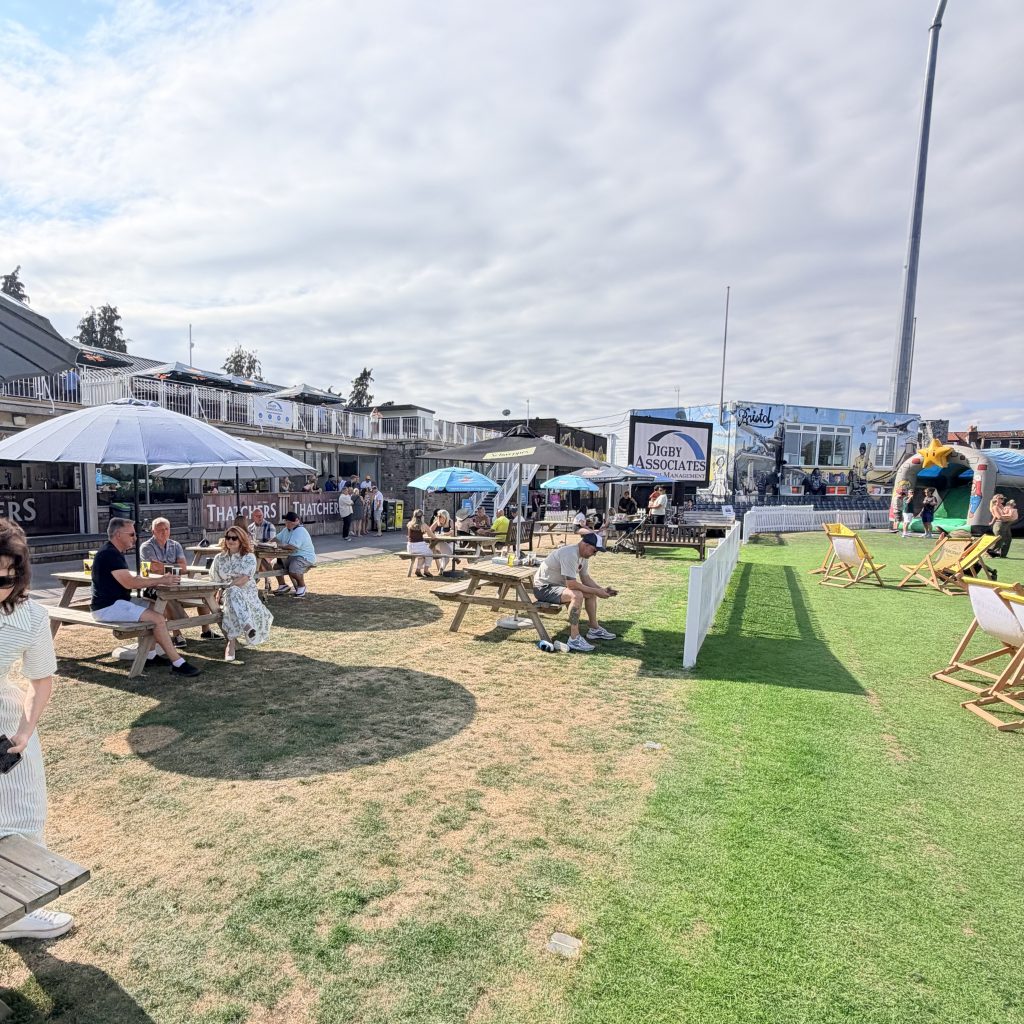
A Fantastic Day at the Digby Associates Family Fun Day

There is something special about bringing people together away from the office, and this year’s Digby Associates Family Fun Day was exactly that.

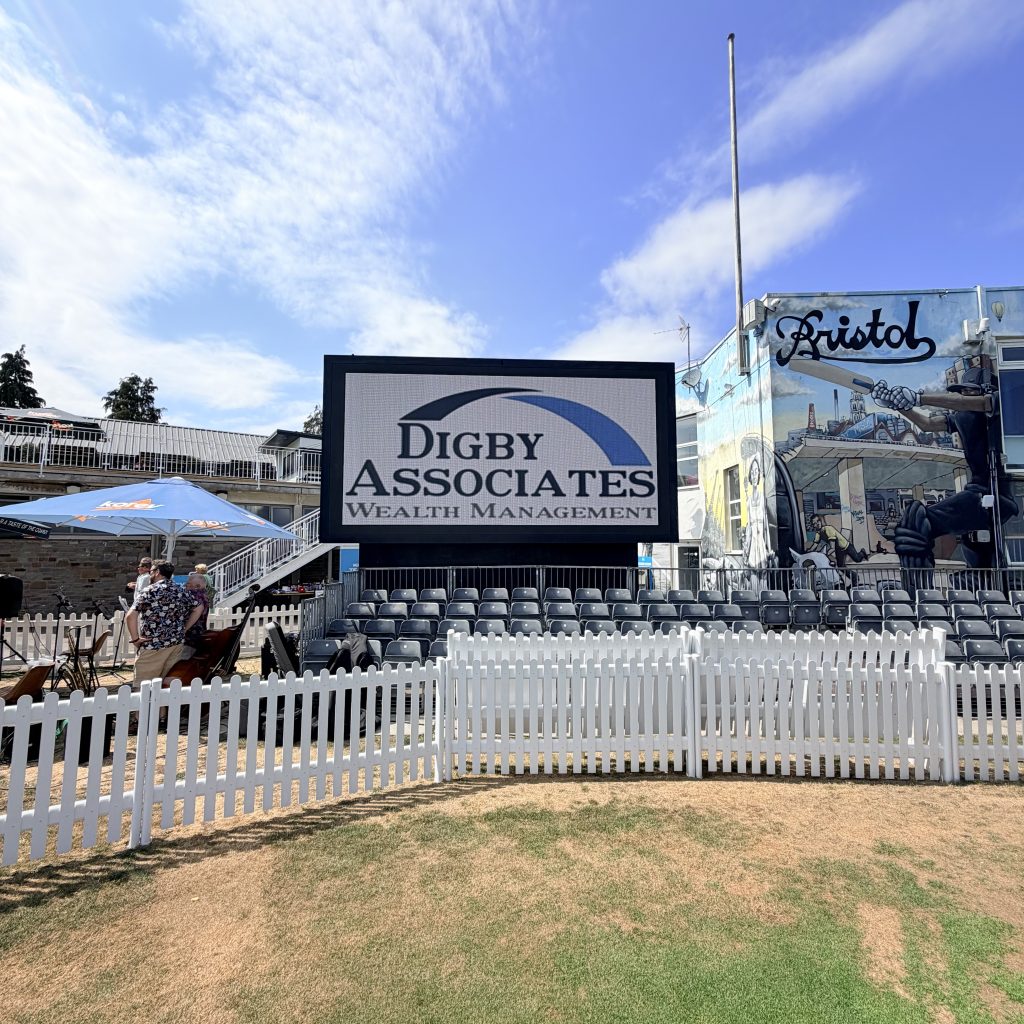
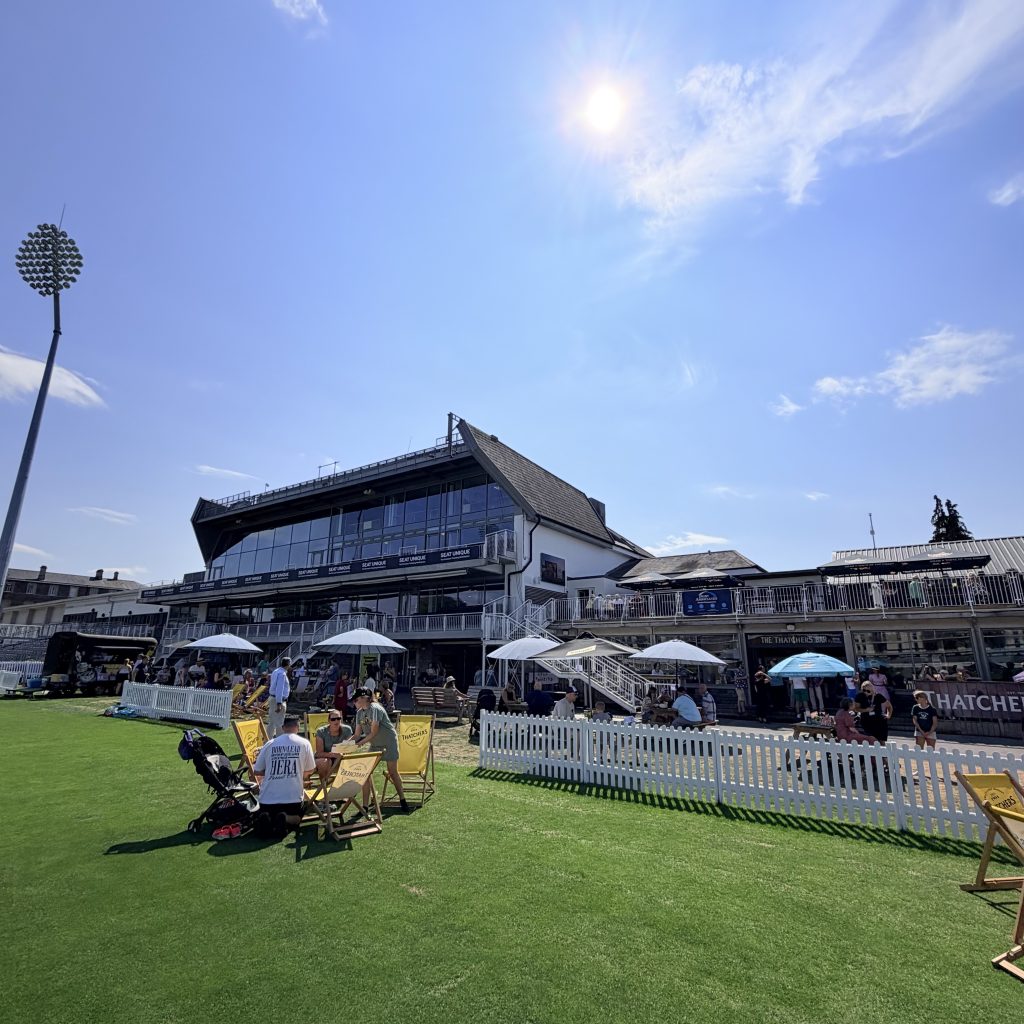
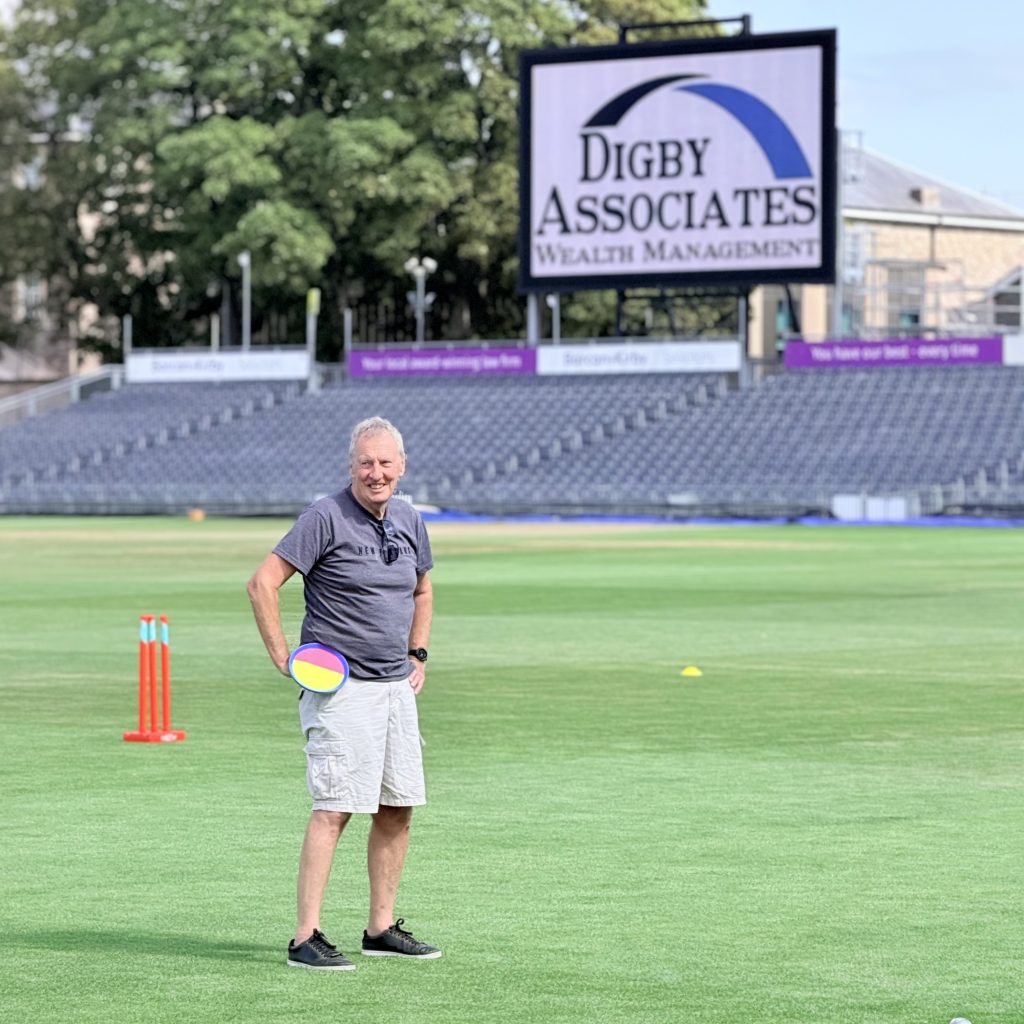
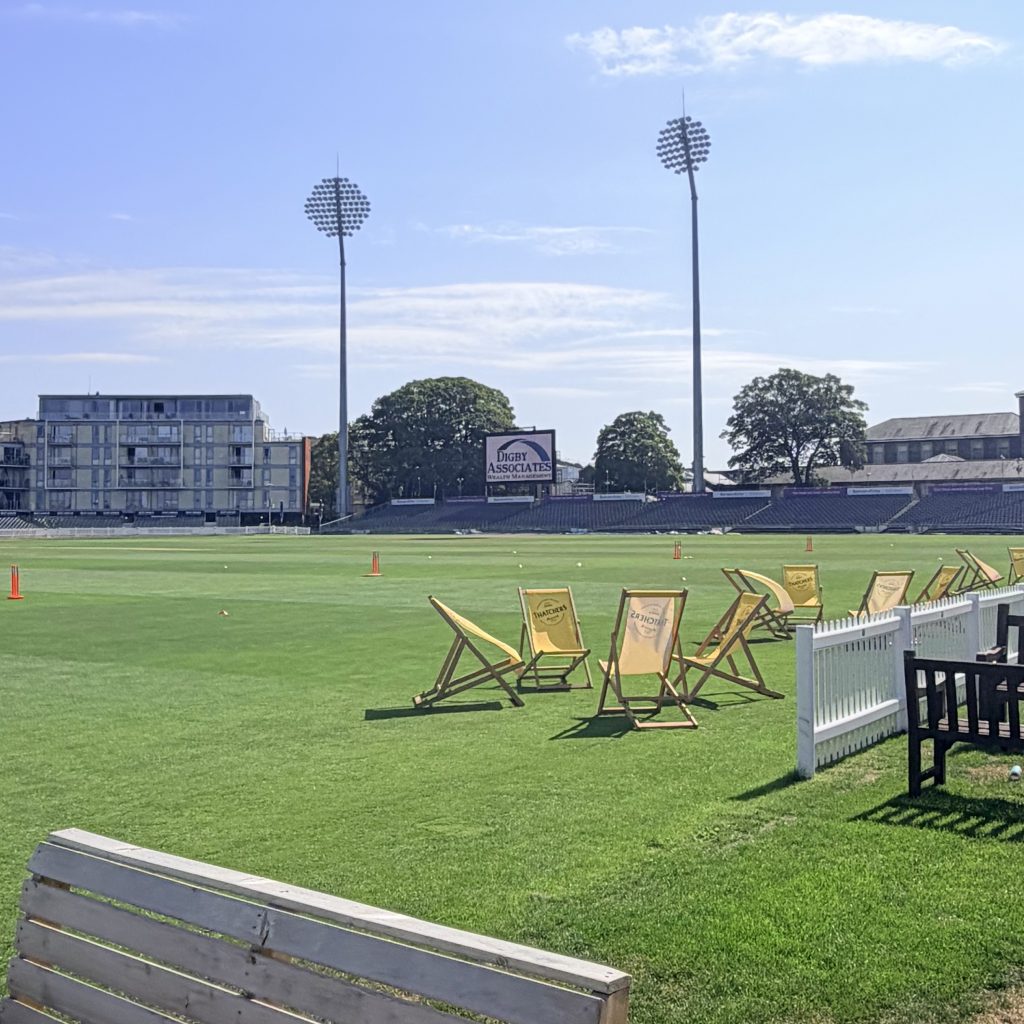
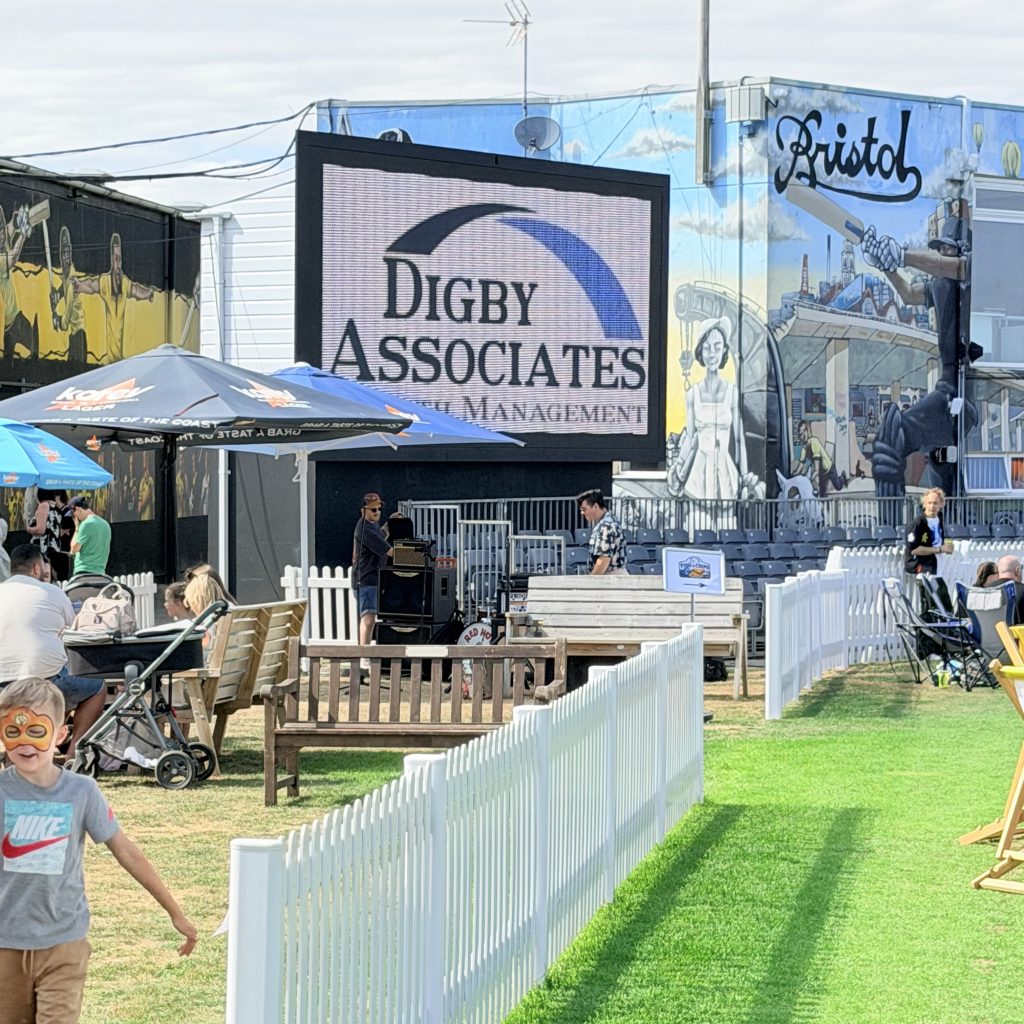
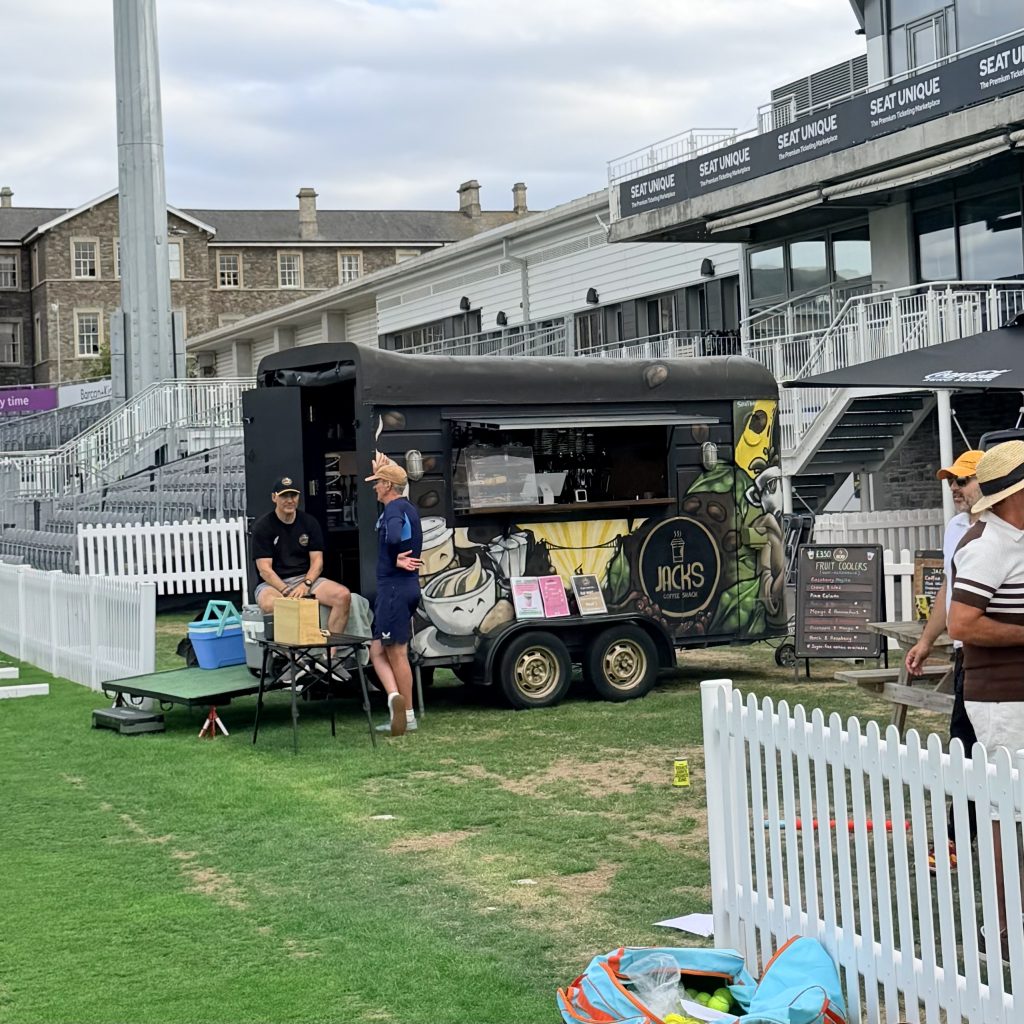
Held at the beautiful Gloucestershire County Cricket Club on Saturday, the Family Fun Day was organised to raise money for good causes while bringing together colleagues, clients, friends and families for an afternoon of fun. It was a fantastic opportunity to catch up with familiar faces, make new memories and support an important cause at the same time.

With glorious weather, a fantastic atmosphere and activities for all ages, it proved to be a wonderful celebration of the people who make Digby Associates what it is.

Bringing People Together

Whether we’re supporting clients through important financial decisions or working together as colleagues, those relationships are built on trust, conversation and genuine care.

Our Family Fun Day was a chance to celebrate those values outside the workplace, bringing together the charity partners, the wider Digby Associates family in a relaxed and enjoyable setting.

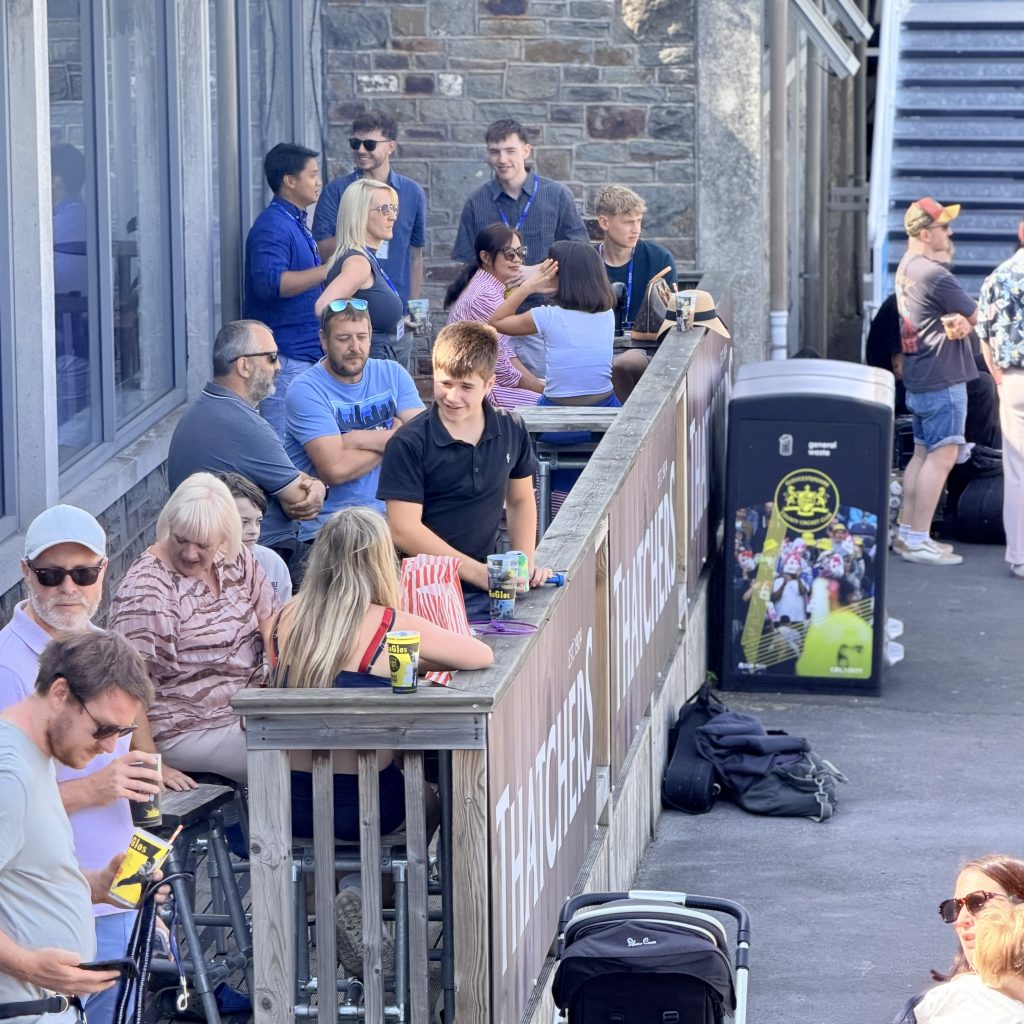
It was fantastic to see so many people there, from young children enjoying the activities to colleagues and clients taking the opportunity to catch up over food and refreshments.

Plenty to Enjoy

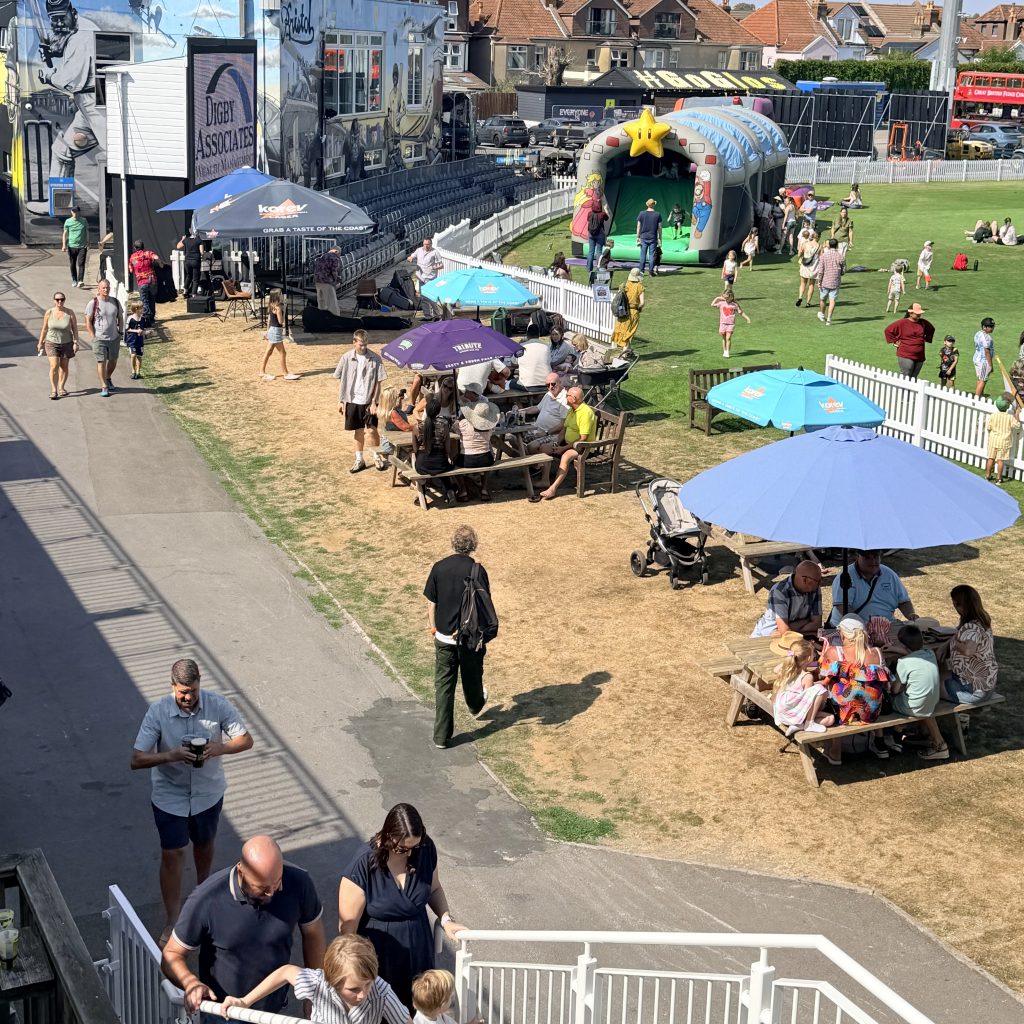
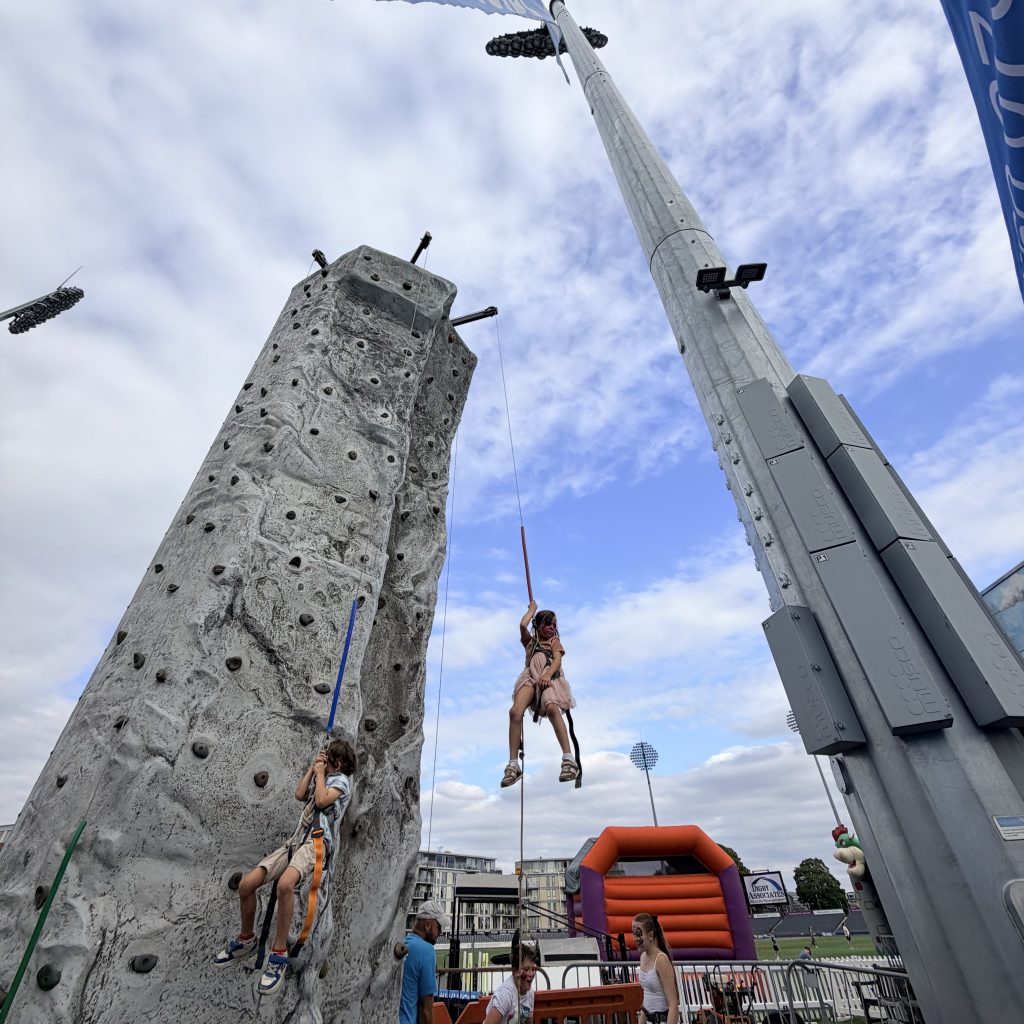
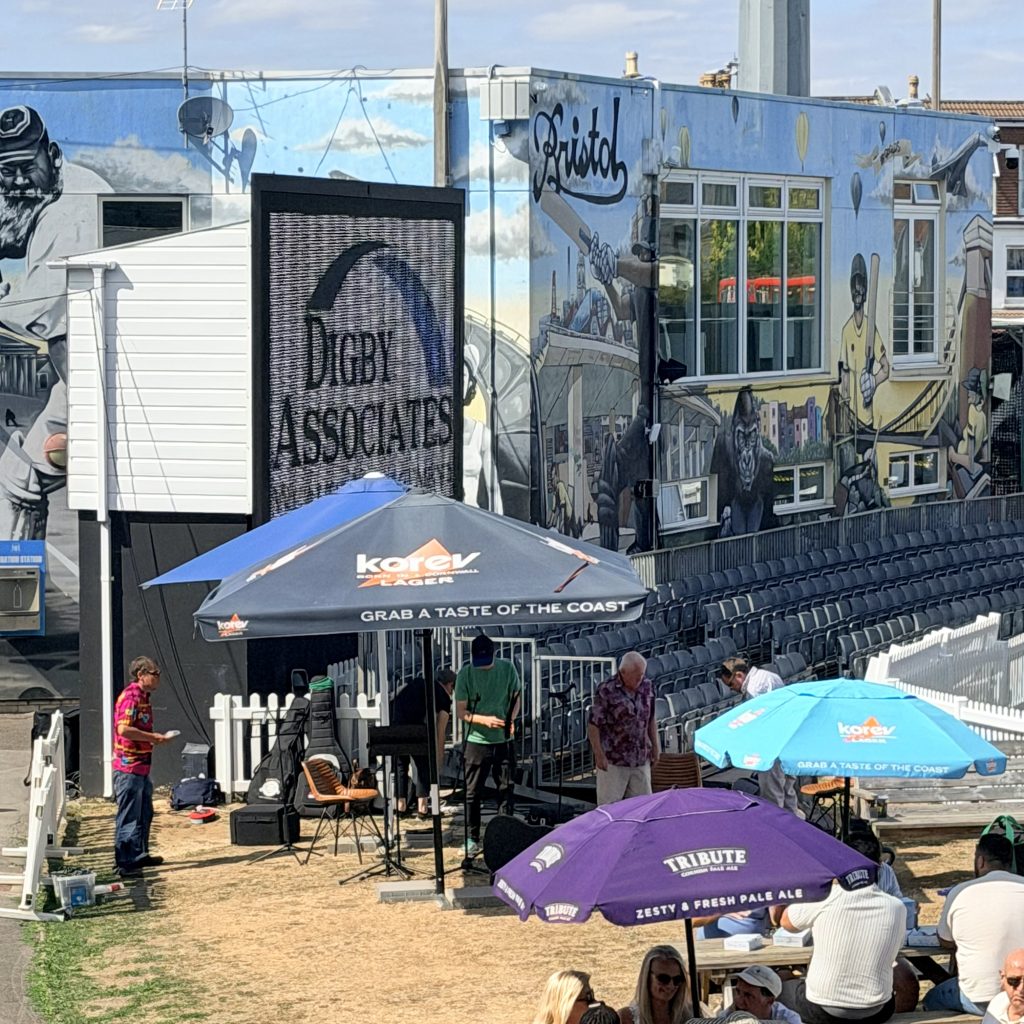
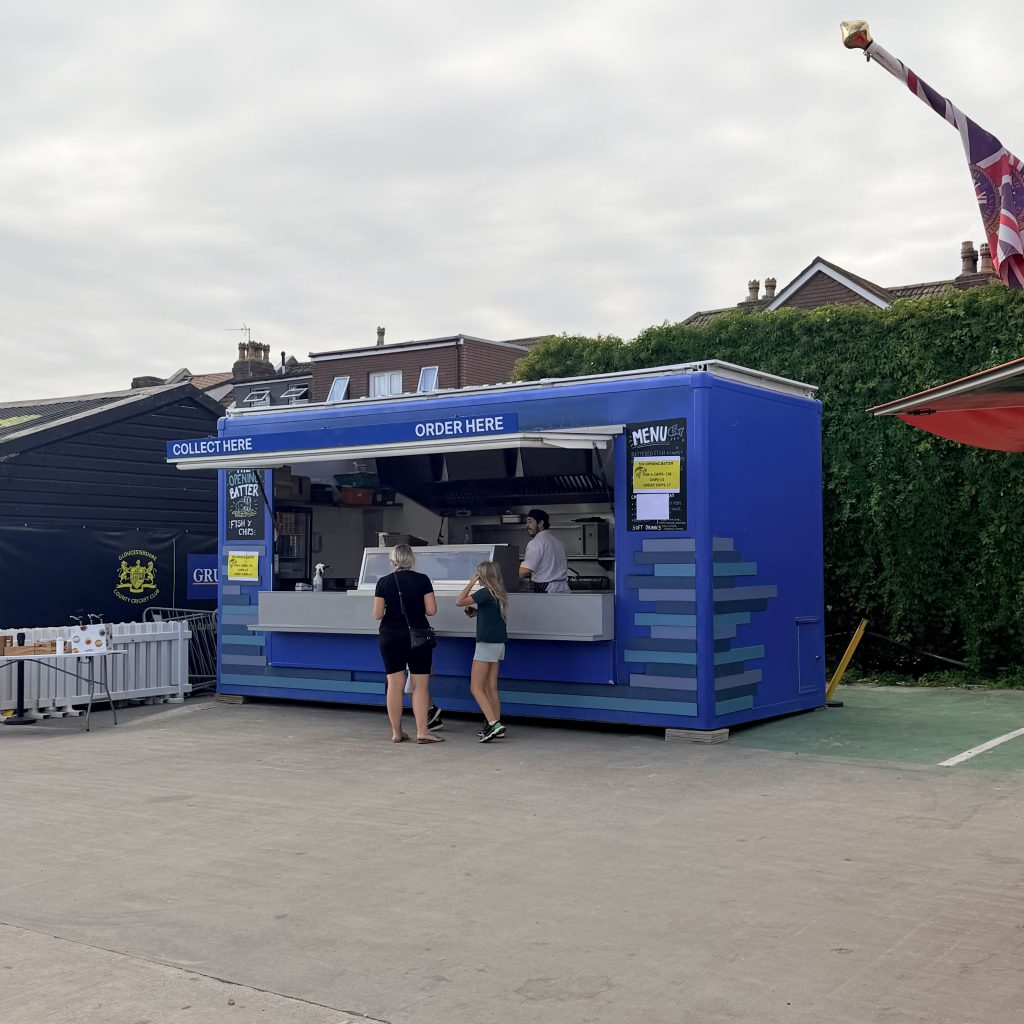
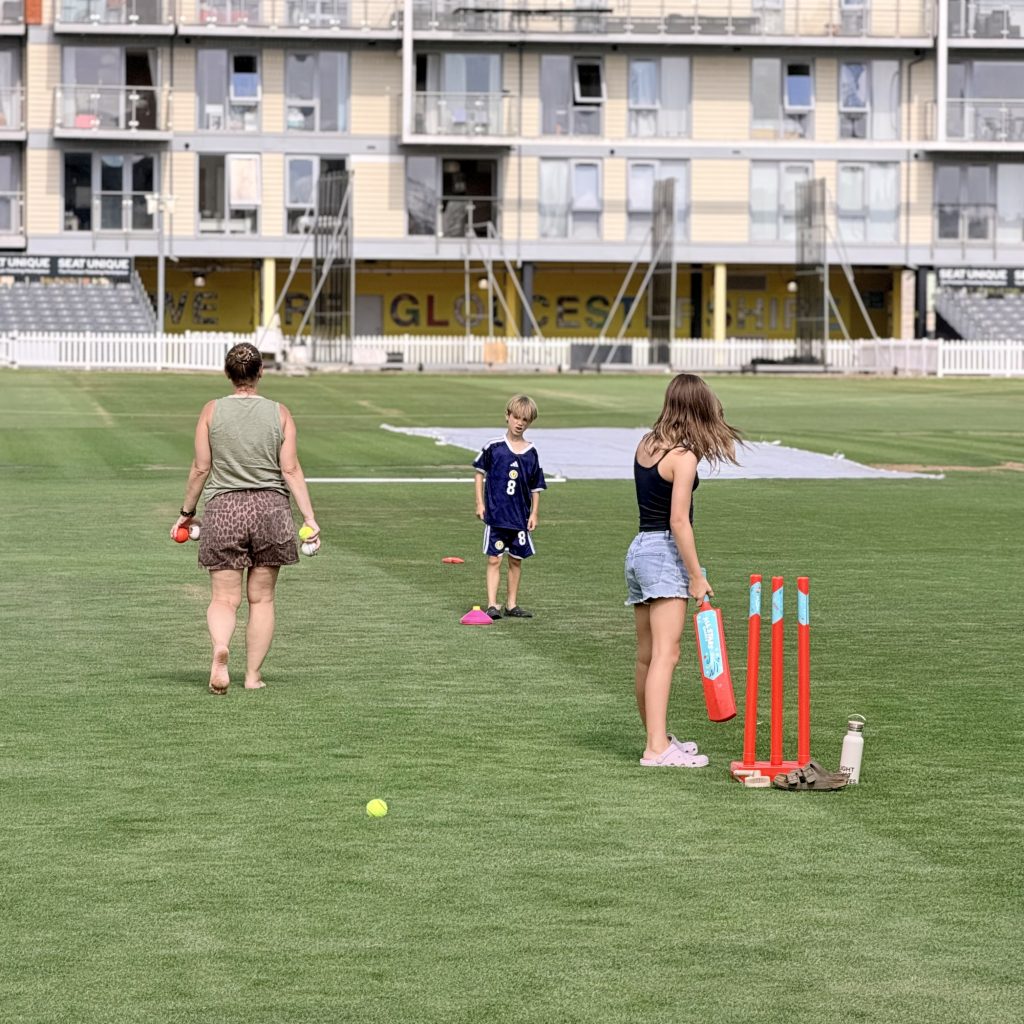
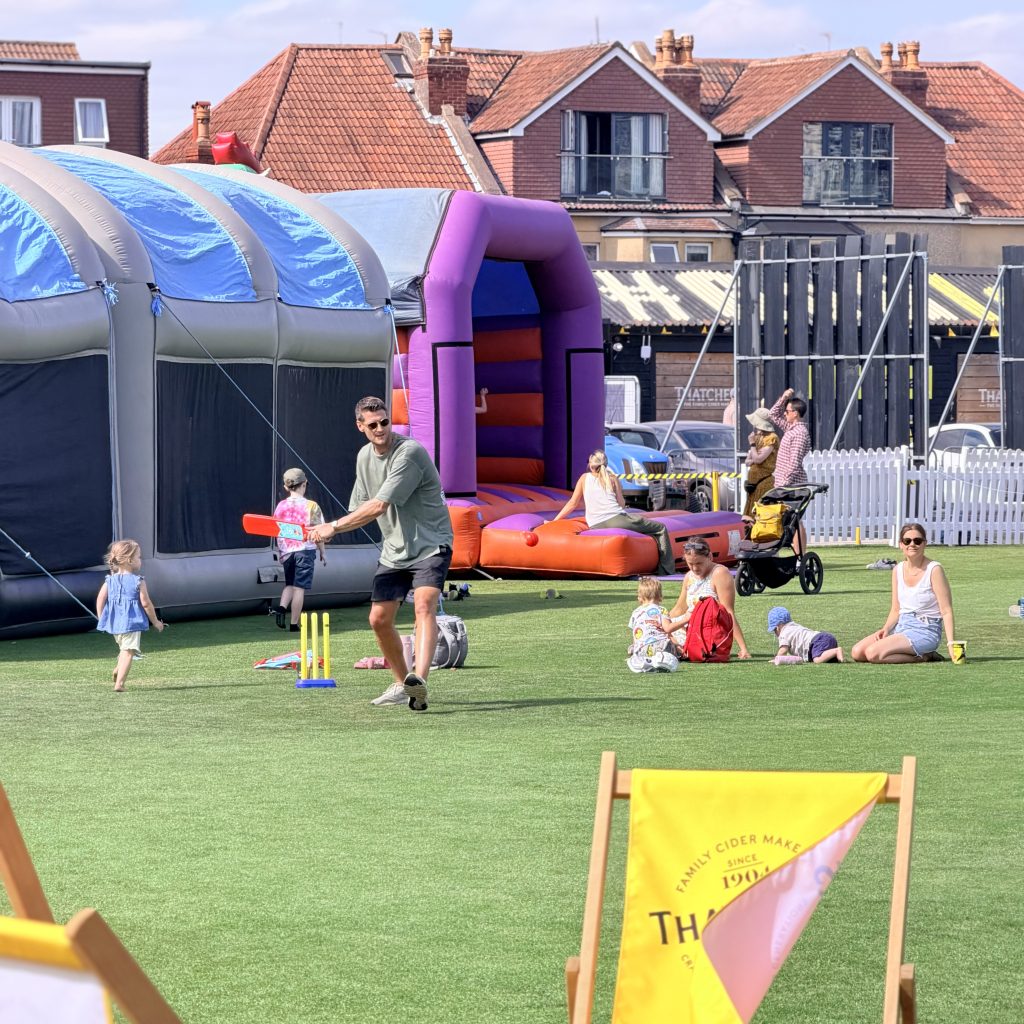
This year we had a really fantastic mix of activities, including Jack’s Coffee Stand, the Fudge Bus from Great British Fudge Company, a climbing wall from Mojo Active, as well as bouncy castles, face painting, a charity raffle with prizes donated by Digby Associates and partner businesses, live music from a local band and plenty of casual cricket activities.

Families enjoyed a wide range of activities, children embraced every opportunity to play, and there was plenty of laughter from start to finish. Gloucestershire County Cricket Club provided the perfect backdrop for the event, creating a relaxed setting where everyone could enjoy the afternoon at their own pace.

Thank You

A huge thank you to everyone who came along and helped make the day such a success.

Thank you also to everyone behind the scenes who organised the event, our charity partners, local businesses that got involved and to Gloucestershire County Cricket Club for being such fantastic hosts.

We hope everyone had as much fun as we did.

Take a look through some of the moments from the day in the gallery below.

Chaise Longue

The Psychology of Financial Confidence

What does it mean to feel financially confident?

For some people, it means having enough savings to deal with an unexpected bill. For others, it is knowing they can retire comfortably, support their family or make a major decision without worrying about every possible outcome.

It is tempting to assume that confidence simply increases as wealth grows. In reality, the relationship is more complicated.

Someone with considerable savings and investments may still worry constantly about running out of money. Another person with more modest resources may feel calm because they understand their position, have a plan and know what they can afford.

Financial confidence is therefore not simply about how much money you have. It is also about how much clarity, control and trust you feel you have over it.

Knowing the Numbers Is Only Part of It

Financial knowledge is valuable. Understanding pensions, savings, investments, mortgages and tax can help us make more informed decisions.

But knowledge alone does not always create confidence.

Many people know they should review their pension, build an emergency fund or organise their finances, yet still avoid doing so. The problem is not necessarily a lack of information. Sometimes the subject feels too complicated, the choices seem overwhelming or there is a fear of discovering something uncomfortable.

Avoidance can then create a cycle. The longer we put something off, the less in control we feel. The less in control we feel, the harder it becomes to take the first step.

Psychologists sometimes describe our belief in our ability to handle a task as self-efficacy. Applied to money, financial self-efficacy is the belief that we can understand our position, make decisions and respond to setbacks without becoming overwhelmed.

This matters because confidence often grows through action, not before it.

Confidence Comes From Clarity

Uncertainty has a habit of filling the space where facts are missing.

Someone approaching retirement may worry that they do not have enough, without knowing what their expected expenditure will be or how their different sources of income fit together. A parent may feel unable to help their children financially because they have never explored what level of gifting would remain affordable. An investor may become anxious during a market fall because they are unclear about why their portfolio was structured in a particular way.

In each case, the worry may be understandable, but it is being shaped partly by unanswered questions.

A clear financial plan cannot remove every uncertainty. Markets will fluctuate, tax rules can change and life rarely follows a perfectly predictable path.

What planning can do is replace vague fear with a clearer view of the options.

There is an important psychological difference between thinking, “I hope I will be all right,” and knowing, “We have considered several possible outcomes and have a plan for each of them.”

Small Decisions Build Confidence

Financial confidence is rarely created by one dramatic decision.

More often, it develops through small actions that demonstrate progress and control. Reviewing household spending, setting up a regular saving habit, consolidating old paperwork or having an overdue conversation about retirement can all make finances feel more manageable.

These actions provide evidence that we are capable of dealing with our money.

Over time, that sense of progress can become self-reinforcing. Greater confidence makes it easier to engage with financial decisions, and regular engagement creates greater clarity.

This does not mean every decision will be perfect. Financial confidence is not the belief that nothing will ever go wrong. It is the belief that if circumstances change, you will be able to understand the problem, seek help and adjust your plans.

Confidence Is Not the Same as Certainty

There is also an important difference between healthy financial confidence and overconfidence.

Healthy confidence involves understanding both what you know and what you do not. It allows room for questions, second opinions and changing course when new information becomes available.

Overconfidence can do the opposite. It may encourage people to underestimate risk, trade investments too frequently, chase recent performance or assume that a run of good results proves they can predict what happens next.

The goal is therefore not maximum confidence. It is well-calibrated confidence.

That means feeling sufficiently informed to make decisions, while remaining realistic about uncertainty and the limits of our knowledge.

Why Comparison Can Undermine Confidence

Money is deeply personal, but modern life makes it difficult to avoid comparison.

We see other people’s homes, holidays, cars and career milestones, usually without seeing the debt, anxiety or difficult choices sitting behind them. Social media can make financial success appear more common, more effortless and more immediate than it really is.

This can distort our sense of progress.

A financial plan built around someone else’s life is unlikely to create lasting confidence. The more useful questions are personal ones. What matters to you? What are you trying to achieve? What level of risk feels appropriate? What would make you feel secure?

Confidence tends to grow when financial decisions are connected to clear personal priorities rather than external expectations.

The Value of Another Perspective

One of the most valuable roles of a financial adviser is not simply to provide information. It is to help people interpret that information in the context of their own lives.

During uncertain periods, it can be difficult to separate a genuine financial problem from an understandable emotional reaction. A trusted adviser can step back, test assumptions and show how different decisions might affect the wider plan.

Sometimes advice identifies an action that needs to be taken. At other times, its greatest value is demonstrating that the plan remains on track and that no immediate change is required.

Reassurance is not about pretending risks do not exist. It comes from understanding those risks and knowing they have been considered properly.

Confidence Is Built, Not Bought

Greater wealth can create more choices, but it does not automatically create peace of mind.

Financial confidence comes from understanding what you have, knowing what it needs to achieve and having a plan that can adapt as life changes.

It is built through clear information, realistic expectations, regular decisions and the willingness to ask for help when it is needed.

holiday spending

Holiday Money This Summer: How Exchange Rates Could Affect Your Spending Abroad

For many of us, the countdown to a summer holiday is well underway. Flights are booked, accommodation is sorted and the suitcase is waiting to be packed.

But before heading to the airport, there is one factor that can have a surprisingly big impact on the overall cost of your trip: the exchange rate.

Even relatively small movements in the value of the pound can affect how much spending money you have once you arrive, influencing everything from restaurant meals and excursions to shopping and everyday purchases.

What Has Been Happening to the Pound?

The good news for UK holidaymakers is that sterling has been relatively resilient in recent weeks.

Against the US dollar, the pound has strengthened to around $1.34, close to its highest levels of the year, helped by changing expectations around interest rates and the wider economic outlook.

The pound has also remained relatively firm against the euro, trading at around EUR 1.17 in recent weeks.

While exchange rates move every day, a stronger pound means British travellers may find their holiday money goes slightly further than it did earlier in the year.

Why Exchange Rates Matter

Exchange rates determine how much foreign currency you receive for every pound you exchange.

Imagine you are taking £1,000 on holiday.

If the exchange rate moves from EUR 1.10 to EUR 1.17, the same £1,000 would give you around EUR 70 more to spend.

That could cover a couple of meals out, a family excursion or a few extra holiday treats.

Small movements in exchange rates can therefore make a noticeable difference, particularly for families travelling abroad.

It Is Not Just About Europe

The strength of the pound also affects holidays further afield.

Travellers visiting the United States, parts of the Caribbean or destinations where prices are linked to the US dollar may also benefit when sterling strengthens.

However, exchange rates are only one part of the picture.

Higher local prices in some destinations mean hotels, restaurants and attractions may still cost more than they did a year or two ago, even if the exchange rate has improved.

Should You Buy Currency Now or Wait?

This is one of the most common questions holidaymakers ask.

The honest answer is that nobody knows exactly where exchange rates will move next.

Currencies respond to a wide range of factors, including inflation, interest rates, economic growth and political developments. Trying to perfectly time the market is therefore extremely difficult.

Instead, some people choose to spread the risk by exchanging part of their money in advance and buying more closer to departure.

Whatever approach you take, it is worth comparing providers. Exchange rates can vary significantly, and the rate available online is often better than the one offered at the airport.

A Few Ways to Make Your Money Go Further

Exchange rates are only one part of holiday spending.

When using a debit or credit card abroad, it is usually better to choose to pay in the local currency rather than pounds sterling. This can help you avoid less favourable conversion rates applied by the retailer or payment terminal.

It is also worth checking whether your bank charges overseas transaction fees. Some accounts offer fee-free spending abroad, while others add a charge each time you use your card.

Leaving all your currency exchange until you reach the airport can also be expensive, as airport exchange desks often offer less competitive rates.

Looking Beyond the Holiday

Exchange rates do not only affect holidays.

They can also influence the price of imported goods, overseas investments and international business activity. Changes in the value of sterling can eventually affect inflation and the cost of everyday products in the UK.

For holidaymakers, however, the impact is much more immediate.

A stronger pound means your spending money can stretch further. A weaker pound means the same holiday may cost more.

Final Thoughts

Exchange rates may not be the first thing you think about when planning a holiday, but they can make a meaningful difference to your overall budget.

Nobody can predict exactly where currencies will move over the coming weeks. However, understanding how exchange rates work, comparing providers and checking card charges before you travel can help you make the most of your money.

After all, if a favourable exchange rate means an extra meal by the sea, another family day out or simply a little less financial stress while you are away, it is worth paying attention before you fly.