Slide5

Passing on Wealth From Surplus Income: What You Need to Know

One of the most useful inheritance tax exemptions is often one of the least understood.

Section 21 of the Inheritance Tax Act 1984 allows people to make regular gifts from surplus income without those gifts being subject to inheritance tax. Unlike many other lifetime gifts, there is no need to survive seven years for the exemption to apply.

For families looking to pass on wealth gradually, this can be an extremely effective planning tool.

What is the exemption?

In simple terms, gifts will usually be exempt from inheritance tax if they:

  • Form part of a normal pattern of giving;
  • are made out of income rather than capital; and
  • do not affect the donor’s usual standard of living.

All three conditions must be met.

What counts as “normal expenditure”?

The gifts must be regular or intended to be regular.

This does not mean they have to be made every month or for the same amount, but there should be a clear pattern or intention behind them.

Common examples include:

  • paying school fees for grandchildren;
  • monthly gifts to children;
  • regular contributions to savings accounts; or
  • paying insurance premiums on behalf of another person.

A one-off payment is less likely to qualify unless there is evidence that it formed part of a wider gifting plan.

Gifts must come from income

The exemption only applies where the gifts are funded from income.

Income might include:

  • salary;
  • pension income;
  • rental income;
  • dividends; or
  • interest received.

Using savings or investment capital will usually prevent the exemption from applying.

HMRC will often look at the donor’s finances as a whole to decide whether the gifts genuinely came from surplus income.

Maintaining your standard of living

The donor must still be able to maintain their usual lifestyle after making the gifts.

If gifts are so large that the donor later needs to rely on savings to meet day-to-day living costs, HMRC may argue that the exemption does not apply.

The key point is that the gifts should come from income that is genuinely surplus to requirements.

Why Section 21 is valuable

The exemption is particularly attractive because:

  • there is no financial limit;
  • gifts are exempt immediately; and
  • there is no seven-year survival requirement.

For individuals with excess income, this can significantly reduce the value of their estate over time.

Example

Mrs Green receives pension and investment income of £120,000 each year. Her annual living costs are around £70,000.

She decides to pay £20,000 each year towards her grandchildren’s school fees.

Provided the payments are made regularly and documented properly, the gifts are likely to fall within the Section 21 exemption because they are made out of surplus income and do not reduce her standard of living.

Good record keeping matters

Claims under Section 21 are often reviewed by HMRC after death, sometimes many years later. Clear records are therefore essential.

It is sensible to keep:

  • details of income received;
  • records of regular expenditure;
  • bank statements;
  • evidence of gifts made; and
  • a written note confirming the intention to make regular gifts.

A simple annual summary of income, expenditure and gifts can be very helpful for executors.

Final thoughts

Section 21 is one of the most effective inheritance tax reliefs available, but it is frequently overlooked.

Used correctly, it allows wealth to be passed down efficiently during lifetime without triggering inheritance tax concerns.

As with most tax planning, careful structuring and good records are essential.
Banner Template

Welcoming Nick Tyler’s Clients to Digby Associates

We are delighted to announce that Nick Tyler’s clients will now be supported by Digby Associates.

Nick has been part of the financial advice profession for 38 years, building a wonderful reputation with clients as a trusted, thoughtful and highly experienced adviser, as well as a genuine friend to many families he has supported over the years.

That is no small legacy and certainly a tough act to follow. We were therefore incredibly proud to be chosen by Nick, following a detailed and thoughtful due diligence process, to continue the work he has built over nearly four decades.

Continuing Trusted Relationships

We understand that relationships between advisers and clients are often built over many years and are founded on trust, consistency and personal understanding.

Our priority is to ensure clients continue to feel well looked after, supported and confident about the future. Clients can expect clear communication, continuity of care and a thoughtful approach to advice that reflects their personal circumstances and long-term goals.

For Nick, finding the right home for his clients was clearly important. Our focus now is to ensure he can continue to bump into former clients knowing they are being looked after well and remain in safe hands.

Building on Strong Foundations

At Digby Associates, we believe good financial advice should feel personal, reassuring and built around care.

We are proud to continue the foundations Nick has created, while providing clients with access to the wider support, resources and expertise available through Digby Associates.

Looking Ahead

This marks another positive step in the continued growth of Digby Associates as we continue to welcome like-minded advisers and clients who value personal service and trusted relationships.

We would like to thank Nick for the confidence he has placed in us and wish him all the very best for the future.

If you would like to learn more about Digby Associates, please visit our About Us page. If you have any questions, our team will be very happy to help.

224085f3-9fff-47c8-8b6d-cc168066b466.jpg

Backing Talent at Gloucestershire Cricket

As the cricket season gets underway, we love the way sport brings people together, inspires ambition and plays an important role in the community.

We are delighted to continue our support of players in Gloucestershire County Cricket Club as the club looks ahead to another exciting season, with fresh talent added to the squad and strong foundations already in place.

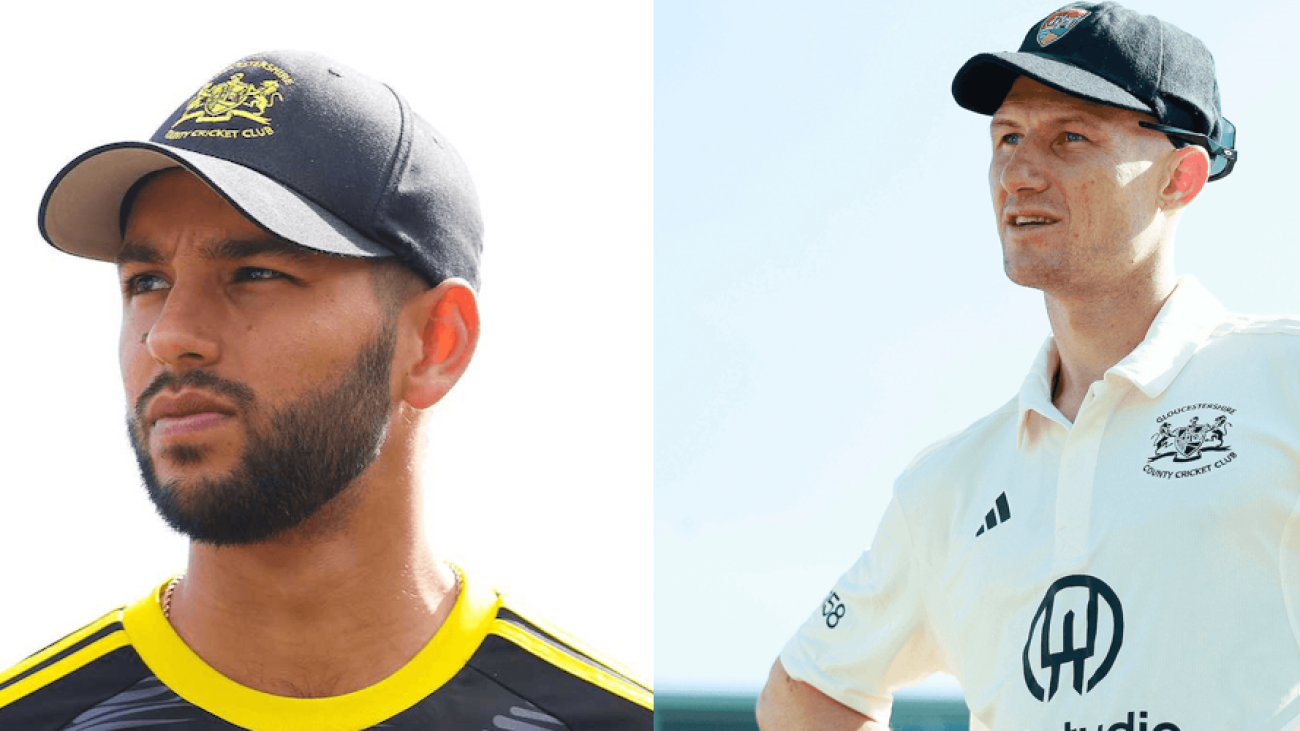
We are proud to be player sponsors of Cameron Bancroft and Daaryoush Ahmed, known as Daz, two players with promising 2026s ahead of them at the club.

A Key Figure at the Club

Since rejoining Gloucestershire in 2024, Cameron Bancroft has become a familiar and highly respected figure at the club. The experienced Australian top-order batter has made a major contribution both on and off the field and was named County Championship captain, underlining the regard in which he is held.

His presence gives the side experience, composure under pressure and a player who sets standards through performance, leadership and craft.

New Energy and Local Promise

Alongside that experience, the emergence of Daaryoush Ahmed is another exciting story for the club.

Bristol-born Ahmed signed a rookie contract with Gloucestershire after impressing with a strong finish to the 2025 season, reflecting both his talent and the opportunities being created for young players coming through the pathway.

For supporters, it is always encouraging to see local talent progress into the professional game, bringing fresh energy and hunger to the squad. Players like Ahmed represent the future of the club and the long-term strength of cricket in the region.

Strong teams are built through a blend of experience and emerging talent. That balance is something Gloucestershire appear to be building, with established performers such as Bancroft alongside promising young players like Ahmed.

As a business rooted in the South West, we are proud to support Gloucestershire County Cricket Club and the positive role it plays across the region.

We wish Cameron, Daz and everyone connected with the club every success for the season ahead, and we look forward to following their progress in the months to come.

Presentation1

Welcoming Graeme Beattie & Carolyn Beattie Clients to Digby Associates

We are pleased to announce that Digby Associates has completed the acquisition of Graeme Beattie and Carolyn Beattie, a respected financial advice business that has supported individuals, families and businesses in Swindon and the surrounding area for many years.

This marks another exciting step in the continued growth of Digby Associates as we expand our presence while remaining committed to the personal service, care and long-term relationships that sit at the heart of our business.

Graeme Beattie has built a strong reputation through practical advice, long-term relationships and a clear commitment to putting clients at the centre of everything he does. Those are values we recognise and share at Digby Associates.

Continuity, Care and Confidence

We understand that any change involving financial advice can feel significant. Our priority is to make this transition as smooth and reassuring as possible for every client.

Clients can expect continuity of service, clear communication and the same focus on thoughtful, personalised advice that has guided their plans to date. We understand that trusted financial relationships are built over many years, through consistency, understanding and confidence in the people advising you. Our priority is to make this transition smooth and reassuring, while protecting the trust that has already been established and continuing to build on it for the future.

Building on Strong Foundations

At Digby Associates, we help individuals and families make confident decisions about their money through advice that is personal, considered and designed to support them over the long term.

This acquisition allows us to build on the excellent foundations created by Graeme Beattie and Carolyn Beattie, while bringing clients access to the wider support, resources and expertise available through Digby Associates.

Looking Ahead

We would like to thank Graeme and everyone involved in building such a respected business. We are proud to welcome clients to Digby Associates and look forward to supporting them in the years ahead.

If you would like to learn more about Digby Associates, please visit our About Us page.

If you are an existing client and have any questions, our team will be happy to help.

98335ad0-ea0c-4576-aeb7-9536e35b77c5

Volunteering Day at St Peter’s Church

We always aim to make a positive contribution to the communities around us, and community volunteering plays an important part in that commitment.

Supporting St Peter’s Church

St Peter’s Church plays an important role within the local community and provides a valued space for residents, visitors and local groups. By helping maintain the church grounds, the volunteers were able to support a space that is used and enjoyed by many people throughout the year.

Giving back to the communities we serve is something we value highly at Digby Associates, and we are always pleased to support initiatives that make a positive local impact.

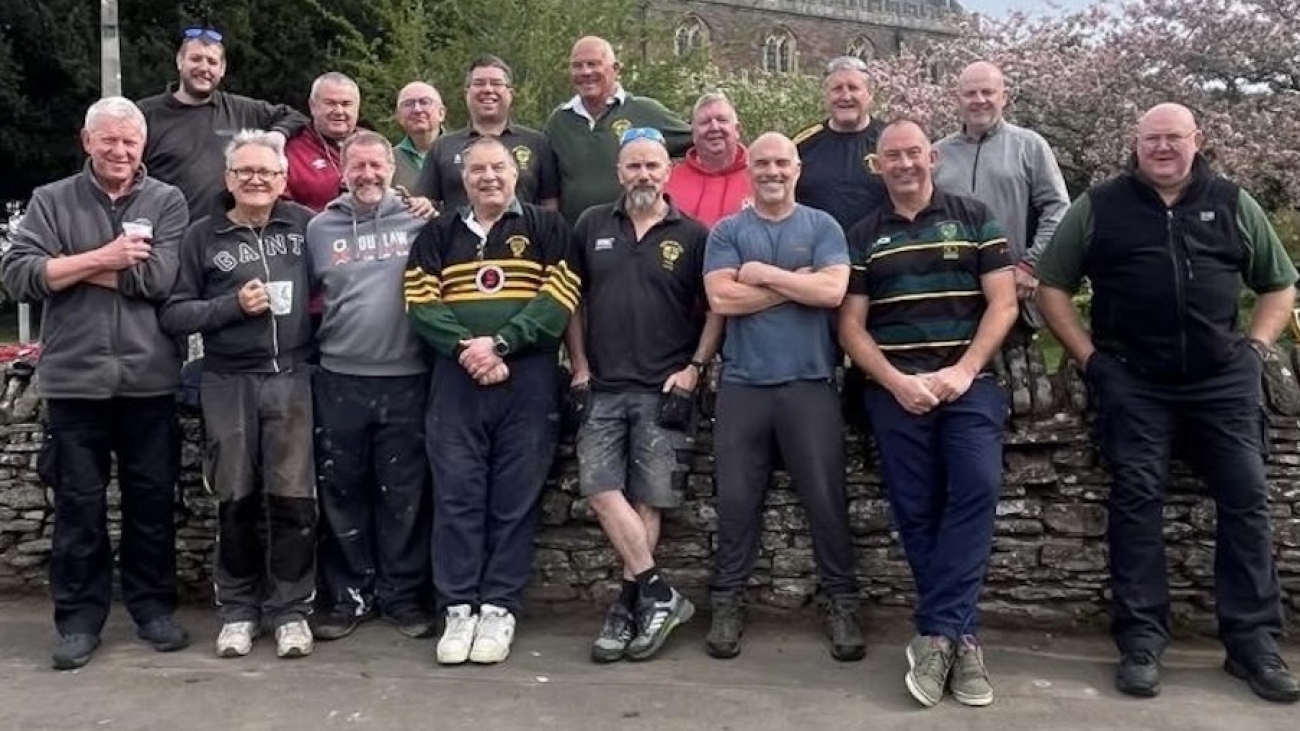
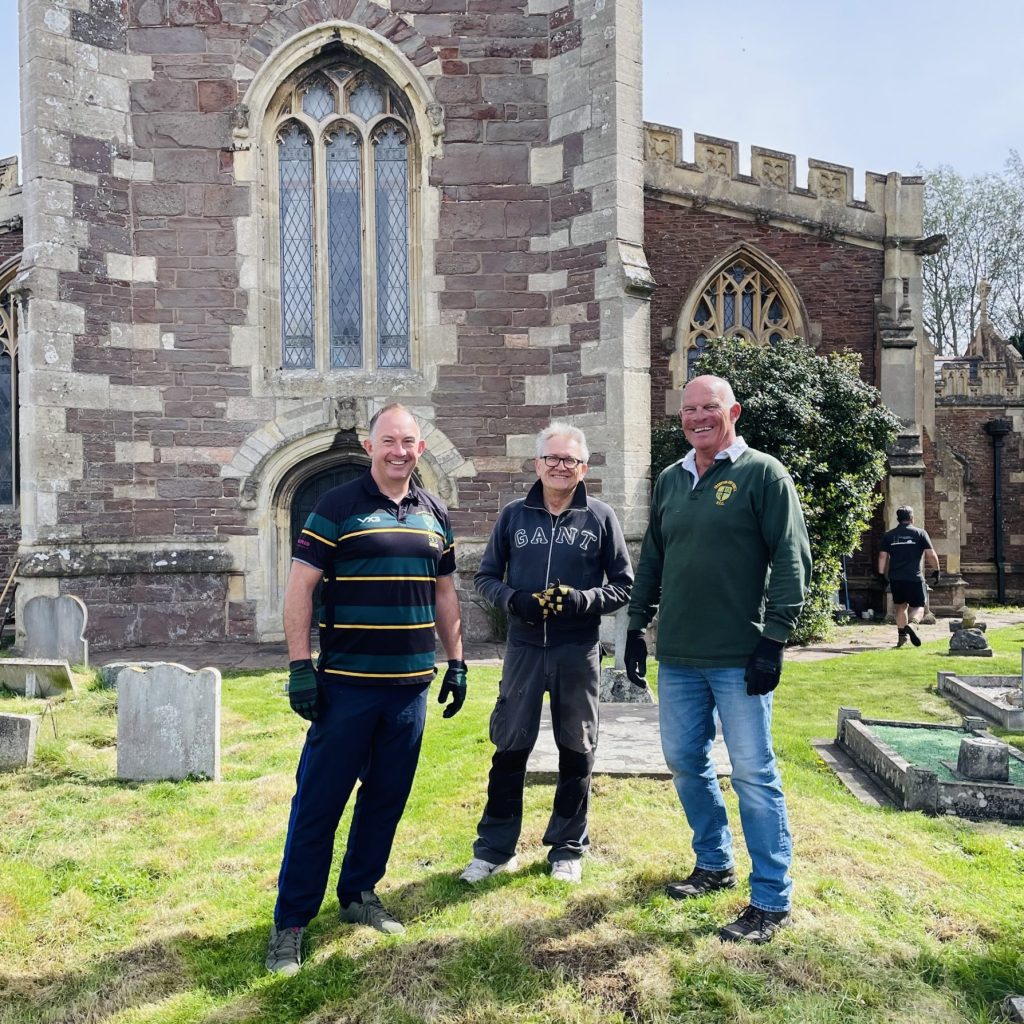
Last week, our Chairman Digby Player organised and took part in a community volunteering day at St Peter’s Church, where a group of Frampton Cotterell RFC retirees, along with a few additional volunteers, came together to help tidy the church grounds.

The group spent the day mowing grass, cutting back overgrowth and improving the churchyard, helping to care for an important local space and keep it looking its best for everyone who uses and enjoys it.

It was a fantastic effort and a reminder of what can be achieved when people come together with a shared purpose. We are proud to support initiatives that strengthen local connections and make a visible difference in the community, and we would like to thank everyone who gave their time so generously.


Banner Template

Make the Most of Your New Tax Year Allowances

The new tax year is now underway, bringing a fresh set of valuable tax-free allowances.

This is a great opportunity to review your financial goals and ensure you’re making the most of the options available to you. By investing early in the tax year, your money has more time to benefit from potential growth.

Your Tax-Efficient Allowances

  • Stocks and Shares ISA: £20,000
  • Lifetime ISA: £4,000 (part of your overall ISA allowance)
  • Personal pension: £60,000 (subject to your earnings)
  • Junior ISA:£9,000
  • Junior personal pension: £3,600 (assuming no earnings)

Taking advantage of these allowances can form an important part of a well-structured financial plan. If you’re unsure how best to use them, seeking professional advice can help you make informed decisions aligned with your long-term objectives.

ISA-Reform-Where-we-are-and-where-we’re-heading.

ISA Reform: Where we are and where we’re heading

Individual Savings Accounts (ISAs) have long been one of the most popular vehicles for UK savers and investors ,offering tax-free interest, dividend income, and capital gains. For over two decades, the rules were relatively stable, but recent government budgets have introduced material reforms. The focus now is on reshaping how ISAs are used rather than scrapping the regime entirely.


ISA Landscape Today (2025/26 Tax Year)

Before we look ahead, here’s the current baseline (the position for tax year 2025/26 and 2026/27):

    • Annual ISA allowance: £20,000. this is the total you can invest each tax year across all ISA types (Cash, Stocks & Shares and Lifetime ISA).
    • Lifetime ISA allowance: £4,000 per year (included within the £20,000).
    • Junior ISA and Child Trust Fund allowance: £9,000 per year.


These rules are unchanged heading into 2026/27,meaning savers still have full flexibility now to use the £20,000 allowance in the way that best suits them.


Key Changes Coming from April 6, 2027 (Tax Year 2027/28

The most significant reforms are due to take effect from 6 April 2027, and they will change how the ISA allowance can be used:

1. Cash ISA Limit Reduced for Under-65s From April 2027:

    • Under-65s will be limited to £12,000 a year into cash ISAs (previously £20,000).
    • The overall annual ISA allowance stays at £20,000, but the remaining £8,000 must be placed into other ISA types (e.g., Stocks & Shares)
    • If you’re 65 or older, you can continue to put up to the full £20,000 into a cash ISA.

This reform is designed to encourage savers to invest more in assets rather than hold cash, in line with the government’s broader strategy to shift capital toward productive investment markets.


2. Lifetime ISA Transition and New First-Time Buyer Product

The current Lifetime ISA (LISA), popular with first-time buyers and for retirement savings will not disappear immediately, but the government is consulting on a re-designed product for first-time buyers.

    • The new product aims to remove the penalty on withdrawals when used to buy a house, giving savers more flexibility.
    • You’ll still be able to open and contribute to existing LISAs until the new product launches.


This reflects a shift in policy thinking: focusing the bonus more tightly on homeownership rather than dual goals (retirement and house purchase).

What This Means for Savers & Investors

Here’s how these reforms could affect you:

1. Cash heavy savers

    • If you prefer low-risk interest-bearing accounts, you’ll need to reassess strategy. With the cash ISA cap falling to £12,000, you might choose to put remaining allowance toward stocks & shares or wrap cash into a Stocks & Shares ISA (though that entails investment risk).

2. Longer term investors

    • Investors eyeing long-term growth might benefit from shifting more into equity-linked ISAs over time to make the most of the full £20,000 allowance. This aligns with the government’s intent behind the reform.

3. Planning Ahead Is Key

The next couple of tax years, especially 2025/26 and 2026/27, offer a final window to use the current cash ISA allowances fully before the new cap arrives in 2027/28 tax year.
The following risk warnings will need to be added to this section, in the same font/size as the main text on the blog:

ISA investors do not pay any personal tax on income or gains, but ISAs may pay unrecoverable tax on income from stocks and shares received by the ISA managers. Tax treatment varies according to individual circumstances and is subject to change. The value of investments and the income they produce can fall as well as rise. You may get back less than you invested.

You will incur a lifetime ISA government withdrawal charge (currently 25%) if you transfer the funds to a different ISA or withdraw the funds before age 60 and you may therefore get back less than you paid into a lifetime ISA.

By saving in a lifetime ISA instead of enrolling in, or contributing to an auto-enrolment pension scheme, occupational pension scheme, or personal pension scheme:

       (i) you may lose the benefit of contributions from your employer (if any) to that scheme; and
      (ii) your current and future entitlement to means tested benefits (if any) may be affected.

Middle-East-conflict-–-what-investors-need-to-know

Middle East conflict – what investors need to know

Geopolitical tensions in the Middle East regularly dominate global news and can understandably raise concerns for investors. However, while conflicts in the region can create short-term market volatility, history shows that their long-term impact on diversified investment portfolios is often more limited than headlines may suggest.

For UK investors, understanding how geopolitical events affect markets can help maintain perspective and avoid reactive decisions that could undermine long-term financial plans.

Why the Middle East matters to global markets

The Middle East plays a crucial role in global energy markets, with several major oil-producing nations located in the region. As a result, conflicts or rising tensions can lead to concerns about disruptions to oil supply or shipping routes.

When markets anticipate potential supply disruption, oil prices can rise. This can influence global inflation expectations and, in turn, affect interest rate outlooks, government bond markets, and equity sectors such as energy, transport and manufacturing.

For UK investors, movements in global energy prices can also feed into domestic inflation, which may influence decisions by the Bank of England and the broader economic outlook.

How markets typically react to geopolitical events

Financial markets tend to react quickly when major geopolitical events occur. Initial uncertainty often leads to short-term volatility in equity markets, currencies and commodities.

However, history suggests that these reactions are often temporary. Once investors gain greater clarity about the scale of the conflict and its economic implications, markets frequently stabilise.

For long-term investors, this highlights the importance of maintaining discipline and avoiding portfolio changes based purely on short-term news flow.

Potential investment impacts

While the overall market impact may be limited over the long term, some areas can be more directly affected.

Energy markets

Energy companies can sometimes benefit from rising oil prices if supply concerns push prices higher. However, higher energy costs can create pressure for industries that rely heavily on fuel.

Inflation and interest rates

If oil prices rise significantly, this can contribute to higher inflation globally. In the UK, inflation pressures may influence interest rate decisions by the Bank of England, which can affect both equity and bond markets.

Defence and security sectors

Periods of heightened geopolitical tension can lead to increased defence spending globally, which may support companies operating in the defence and aerospace sectors.

Safe-haven assets

During periods of uncertainty, investors sometimes move towards assets perceived as safer, such as gold or high-quality government bonds.

Why diversification remains important

One of the most effective ways to manage geopolitical uncertainty is through diversification. Spreading investments across different asset classes, sectors and geographic regions can help reduce exposure to any single event.

A well-diversified portfolio is designed to withstand a range of economic and geopolitical scenarios. While some regions or sectors may experience short-term volatility, others may remain resilient or even benefit.

For many investors, maintaining a balanced and globally diversified portfolio remains the most effective way to navigate uncertain environments.

Focus on the long term

Periods of geopolitical tension can feel unsettling, particularly when markets react sharply in the short term. However, reacting emotionally to headlines can lead to decisions that disrupt carefully constructed financial plans.

Investors who stay focused on long-term objectives, maintain diversified portfolios and follow a disciplined investment strategy are often better positioned to navigate periods of market uncertainty.

What investors should do now

Rather than reacting to headlines, investors may benefit from focusing on a few key principles:

  • Maintain a long-term investment perspective
  • Ensure portfolios remain well diversified
  • Avoid making reactive decisions based on short-term market movements
  • Review investment strategies periodically with a financial adviser

A well-structured financial plan is designed to account for uncertainty, including geopolitical events that cannot be predicted.


Important information

This article is for general information only and does not constitute financial advice. The value of investments and the income from them can go down as well as up and you may not get back the amount originally invested. Past performance is not a reliable indicator of future results.

The information contained in this article is based on current understanding of market conditions and may change. Investors should seek personalised financial advice before making investment decisions.

Digby Offices-11

Preparing for Tax Year End Planning (UK Guide)

The UK tax year ends on 5 April each year. A little planning before this date can help you reduce your tax bill, use valuable allowances, and avoid last-minute stress.
Here’s a simple guide to getting organised before the deadline.

1. Use Your ISA Allowance

Each tax year, you can invest up to £20,000 into ISAs. This allowance doesn’t roll over. You could consider:

  • A Cash ISA
  • A Stocks & Shares ISA
  • A Junior ISA for children

If you don’t use your allowance before 5 April, you lose it. ISAs remain one of the most tax-efficient ways to grow savings, as investments are free from income tax and capital gains tax.

2. Review Pension Contributions

Pension contributions can reduce your taxable income and may give you valuable tax relief. For most people, the annual allowance is £60,000 (subject to earnings and tapering rules). Contributions must be paid before 5 April to count for this tax year.

Making a pension contribution could:

  • Reduce higher-rate tax liability
  • Help bring income below key thresholds
  • Boost long-term retirement savings

If you’re unsure how much you can contribute, guidance from HM Revenue & Customs can clarify the current rules or speak with us.

3. Consider Capital Gains Tax (CGT)

Everyone has an annual Capital Gains Tax exemption. If you’ve sold investments or assets this year, check whether you’ve used it.

Before year end, you might:

  • Realise gains within your allowance
  • Offset gains with losses
  • Transfer assets between spouses to use both allowances

Tax rules can change, so planning ahead is important.

4. Make Use of Inheritance Tax (IHT) Gifting Allowances

You can give away up to £3,000 each tax year free from inheritance tax. If unused, you may be able to carry forward one previous year’s allowance.

Other small gift exemptions may also apply. Regular gifting from surplus income can also be effective, if structured correctly.

5. Dividend and Income Planning (Business Owners)

If you’re a company director or business owner, review:

  • Dividend payments
  • Salary levels
  • Pension contributions from the business

Small adjustments before 5 April can make a significant difference to your overall tax position.

6. Check for Tax Traps

Some common thresholds to watch:

  • The £100,000 income level (where personal allowance starts reducing)
  • Child Benefit high-income charge
  • Pension tapering for very high earners

Even a small pension contribution before year end can sometimes restore lost allowances.

7. Don’t Leave It Too Late

Providers can become very busy in March and early April. ISA transfers, pension contributions, and investment transactions can take time to process.

Starting early gives you more options and reduces the risk of missing deadlines.

Final Thoughts

Tax year end isn’t about rushing into decisions , it’s about making sure you don’t waste valuable allowances.

A short review now could:

  • Reduce your tax bill
  • Increase long-term savings
  • Improve overall financial efficiency

If you’d like help reviewing your position before tax year end, speak with us to ensure everything is structured correctly and in line with current rules.

Intergenerational-financial-planning

Intergenerational financial planning: “We’ll deal with it later” Usually means “too late”

Let’s be honest.

Most people don’t grow up dreaming of meetings about pensions, inheritance tax, or long-term financial planning. For many in the next generation, financial advice sits somewhere between doing a tax return and organising the garage, important, but very easy to put off.

And yet, one day, it suddenly matters.

The great wealth transfer

Over the next couple of decades, a huge amount of wealth will move from one generation to the next. Property, pensions, investments, businesses etc.

The problem?
Many people receiving that wealth:

  • Don’t fully understand it
  • Haven’t been part of the conversation
  • Don’t have a relationship with an adviser they trust

So, what happens? They switch advisers… or worse, stop taking advice altogether.

Not ideal when real money and real decisions are involved.

Why the next generation switches off.

Younger adults don’t avoid advice because they’re careless, they avoid it because it often feels:

  • Too formal
  • Too technical
  • Too “this will matter when you’re 65”

Add in a healthy dose of jargon and a long PDF, and disengagement is almost guaranteed.

At Digby Associates, the average age of our advisers is 36.

That means:

  • We remember renting, student loans, career changes and childcare costs
  • We know that life rarely follows a neat financial timeline
  • We’re used to explaining complex things in plain English (without sounding like a textbook)

We don’t believe financial planning should feel like a lecture, it should feel like a conversation.

Conversations are more relaxed

Questions feel easier to ask (including the “basic” ones)

Financial planning feels relevant now, not “one day”

It also means we’re naturally focused on long-term relationships. We’re not just planning for the next review , we’re planning for the next 20 or 30 years.

Intergenerational planning without the awkwardness

Intergenerational financial planning doesn’t mean forcing family meetings around the kitchen table (unless you want to).

Done well, it’s about:

  • Gradually involving the next generation
  • Building confidence before responsibility
  • Making sure everyone understands what exists and why
  • Avoiding nasty surprises later

And yes, it’s possible to talk about money without it being uncomfortable.

Planning that grows with you

Families want to know that:

  • Their children won’t feel lost when wealth transfers
  • Decisions won’t be rushed under pressure
  • Advice will still feel relevant years from now

With an adviser team whose average age is 36, Digby Associates is built to grow with your family, not just advise one generation.

Disclaimer: Estate Planning and Inheritance Tax Planning are not regulated by the Financial Conduct Authority.

Approver Quilter Financial Services Ltd. January 2026