Is the Cheapest Pension Really the Best Pension

Is the Cheapest Pension Really the Best Pension?

When we buy most things, price is an obvious place to start.

If two products appear to do the same job, choosing the cheaper one seems perfectly sensible.

But pensions are slightly different.

The Government and Financial Conduct Authority are currently developing a new Value for Money framework for workplace pensions. One of the ideas behind it is surprisingly simple: judging a pension purely by what it costs doesn’t necessarily tell you whether it is delivering good value.

The proposals are intended to encourage greater consideration of the outcomes savers actually receive, including investment performance and the quality of services provided, rather than focusing predominantly on charges. GOV.UK

And that raises a much broader question.

What does good value actually mean when it comes to your money?

Cost Matters, But It Isn’t the Whole Story

Charges matter because every pound taken in fees is a pound that isn’t invested for your future.

Over many years, seemingly small differences in costs can add up.

But looking at cost in isolation can be misleading.

Imagine two pensions. One costs slightly less than the other, but the more expensive pension offers a different investment strategy, better functionality or services that are more appropriate for the person using it.

Simply looking at the headline charge wouldn’t tell you which represented better value.

The same principle applies much more widely across financial planning.

The cheapest option and the best-value option are not necessarily the same thing.

What Are You Actually Paying For?

This is where the conversation becomes more interesting.

With any financial product or service, it’s worth looking beyond the headline percentage and asking what you are actually receiving in return.

With a pension, that might include the investment options available, how those investments have performed, the quality of administration, the flexibility available when you eventually want to access your money and whether the pension continues to suit your circumstances.

And when financial advice is involved, value becomes broader still.

An adviser isn’t simply there to select an investment.

They might help someone understand whether they’re saving enough, make use of appropriate tax allowances, structure their retirement income, avoid unnecessary tax, plan for their family or simply provide reassurance when markets become uncomfortable.

Some of those things are relatively easy to measure.

Others aren’t.

The Value of Avoiding the Wrong Decision

There’s another part of financial value that rarely appears neatly on a statement.

It’s the decisions you don’t make.

Selling investments during a market fall. Taking too much income from a pension too early. Holding money in an unsuitable place for years. Missing an allowance. Making a decision based on a frightening headline rather than your long-term plan.

Good financial planning isn’t only about trying to make your money grow.

Sometimes its value comes from helping you avoid decisions that could take you further away from what you’re trying to achieve.

Value Is Personal

Perhaps the most important point is that value will not look identical for everyone.

Someone in their thirties building a pension may care predominantly about long-term growth, appropriate investment choices and costs. Investments usually fluctuate in value. Over shorter periods, this means the value of investments can go up and down. Historically, investors who remain invested for longer periods have been more likely to achieve positive returns, although this is not guaranteed.

Someone approaching retirement may place much greater value on understanding how much they can afford to spend and how their different pensions, savings and investments can work together.

Someone later in retirement might be thinking about family, inheritance and how their wealth should eventually be passed on.

The numbers matter in every case.

But so does what those numbers are there to achieve.

Looking Beyond the Price Tag

The Government’s proposed Value for Money framework is specifically concerned with workplace pensions, but the principle behind it is a useful one for all of us.

Price matters.

Performance matters.

Service matters.

And, ultimately, outcomes matter.

When you’re making decisions that could affect your finances for decades, the better question isn’t always:

“What’s the cheapest option?”

It might be:

“What am I getting for what I’m paying, and is it helping me achieve what I actually want?”

That is a much more useful definition of value.

The Government’s current consultation on the Value for Money framework can be found here: Value for Money Framework consultation on GOV.UK
Cash Is Paying Again. So Why Would Anyone Invest

Cash Is Paying Again. So Why Would Anyone Invest?

For a long time, keeping large amounts of money in cash came with an obvious drawback: interest rates were extremely low.

That has changed. Some fixed savings accounts are currently offering rates above 5%, while Moneyfacts reports that fixed savings rates have strengthened again. At its latest meeting on 17 September, the Bank of England held Bank Rate at 3.75%, although three members of the Monetary Policy Committee voted to increase it to 4%.

For savers who remember earning next to nothing on cash, that can make today’s rates look particularly attractive. And it raises a perfectly reasonable question: if I can earn a decent return without taking investment risk, why would I invest at all?

The answer comes down to what the money is actually for.

Cash Has an Important Job

Cash should form part of most financial plans because money that may be needed at short notice generally needs to be accessible and relatively predictable. That could include an emergency fund, money set aside for a house move, a holiday or other known expenses over the next few years.

If you are planning to replace the car next summer, for example, exposing that money to short-term market movements may not make much sense. There is real value in knowing that £20,000 will still be there when you need it. But that does not necessarily mean cash is the best home for money you may not need for another 10, 20 or 30 years, where a longer time horizon can change what is appropriate.

A Good Interest Rate Isn’t the Same as Long-Term Growth

Today’s savings rates look attractive partly because of what came before them. For much of the period following the financial crisis, interest rates were exceptionally low, so the current environment feels very different. But cash rates move over time, often in response to changes in the Bank of England’s Bank Rate and wider economic conditions.

At its September meeting, the Bank of England held Bank Rate at 3.75%, although three of the nine members of the Monetary Policy Committee voted for an increase to 4%. The Bank also highlighted increased risks to the inflation outlook, which is a useful reminder that the direction of interest rates is never guaranteed.


An attractive savings rate today therefore tells you relatively little about what cash might earn over the next decade. Investment decisions, by contrast, are generally made with a much longer time horizon in mind, so it is important not to let a particularly attractive short-term savings rate drive a decision about money intended for many years into the future. Investments are designed to help grow your money for the future over the longer term. You should keep in mind that both are exposed to market movements, meaning values can go down as well as up, and you may not receive back the full amount invested or saved into a pension.

Inflation Still Matters

There is another number worth considering alongside the interest rate on your savings account: inflation. UK inflation currently stands at 3.1%, according to the Bank of England. If your savings are earning 4% while prices are rising by roughly 3%, the purchasing power of your money is not actually increasing by the full 4%.

That does not make cash a bad option, but it does mean the headline interest rate does not tell the whole story. Over longer periods, the objective of investing is generally not simply to preserve the number sitting in an account, but to give money the opportunity to grow faster than inflation. That potential for higher long-term growth comes with risk, of course, and the value of investments can fall as well as rise, particularly over shorter periods.

The Question Shouldn’t Be Cash or Investments

This is where financial planning becomes more useful than simply comparing rates. The question is rarely just whether you should hold cash or invest. A more useful question is how much of your money needs to remain in cash, and how much could be working towards longer-term goals.

The answer will depend on your circumstances. Someone approaching retirement may understandably want a larger cash reserve than somebody in their thirties with decades before they expect to access their pension. Likewise, someone planning to buy a house next year will have very different priorities from someone investing for grandchildren who are still at primary school. The right balance depends on what the money is for, when it may be needed and how comfortable you are with investment risk.

Don’t Let Today’s Rate Make a 20-Year Decision

Periods of higher savings rates can create an interesting temptation. Cash feels safe, the return is visible and, compared with markets that move every day and occasionally produce uncomfortable headlines, it can seem entirely rational to leave long-term money sitting in cash while waiting for a “better time” to invest.

The difficulty is that nobody reliably knows when that better time will arrive. A decision made because of today’s savings rate can end up shaping what happens to your money for many years, which is why separating money by purpose and timescale can be so useful. Cash may be more appropriate for money you are likely to need in the near term, while investments can be better suited to money that has time to ride through the inevitable ups and downs of markets.

Different Money, Different Jobs

Cash and investments are not really competitors because they serve different purposes. Cash can provide certainty, accessibility and peace of mind, while investments offer the potential for longer-term growth. For many people, a sensible financial plan will therefore include a combination of both, with each playing a different role depending on when the money may be needed and what it is intended to achieve.

So rather than asking whether today’s attractive savings rates mean investing no longer makes sense, the more useful question might be:

What job do I need this particular pot of money to do?

Once you know that, deciding where it should sit becomes much easier.


Approver Quilter Financial Services Limited September 2026

exec-77ad60a0-8cf3-429d-9f17-1e662663f974

Digby Downloads: Are You Asking the Right Question?

One of the nice things about the summer holidays is that I occasionally get to revisit the client-facing side of the business.

These days, as Non-Advising Principal, most of my time is spent working on the business rather than meeting with clients. However, with colleagues taking some well-earned holidays, I had the opportunity to sit in on a few client meetings this week.

Three in one day, in fact.

It almost felt like the old days.

Something struck me as I drove home afterwards.

All three clients had investments elsewhere alongside the work we do for them. That’s becoming increasingly common. Let’s call the platforms Harry Lippup and Adrian Jerome Bellingham. I suspect you know who I mean! And before anyone thinks I’m criticising them, I’m not. They’re excellent businesses and very good at what they’re designed to do. They give people easy access to investments, clear valuations and plenty of information.

But they also reminded me of something important.

Every so often someone will ask, “What does a financial adviser offer that I can’t do myself?”

It’s a fair question.

If all you need is somewhere to buy investments, many platforms do an excellent job.

But financial planning has never really been about simply finding a home for your money.

It’s about asking the right questions.

I remember a conversation from several years ago with someone who proudly told me he had built up around £60,000 in an ISA. He then questioned the value of financial advice.

I asked whether he had ever contributed to a pension.

The answer was no.

He was 60 years old.

Now, that wasn’t advice, and it certainly wasn’t a recommendation. No adviser could make a recommendation without first understanding a client’s circumstances, objectives and attitude to risk.

But it illustrated an important point.

He wasn’t asking the right question.

He was focused on the performance of his investments.

A financial planner would first consider whether the money was held in the most appropriate place for his circumstances and objectives.

Those are two very different conversations.

That’s often the difference between having access to investments and working with a professional who can challenge your thinking and help you explore the bigger picture. Sometimes the greatest opportunity isn’t improving investment performance. It’s taking a step back and looking at the wider financial picture.

The same principle applies to retirement planning.

A client may believe they need £2,000 a month to live comfortably in retirement.

Through cashflow modelling and careful planning, an adviser may identify that their circumstances could support a higher level of expenditure while remaining aligned with their long-term objectives.

That can lead to a very different conversation.

Rather than focusing solely on whether retirement is affordable, the discussion can become about how someone wants to spend their retirement, whether that’s travelling more, helping family members or making the most of the wealth they’ve accumulated over time.

One of the things I’ve observed throughout my career is that people rarely seek professional financial planning because they want access to another investment platform.

More often, they’re looking for guidance, insight and reassurance.

Reassurance that they’re making informed decisions.

Confidence that they’ve considered the opportunities available to them.

And sometimes reassurance that they may be able to enjoy life more than they originally thought.

Investment performance will always matter.

But in my experience, much of the value of financial planning comes long before investments are discussed.

It comes from asking better questions.


Approver Quilter Financial Services Ltd. September 2026

The New Luxury Isn’t More Stuff. It’s More Time.

The New Luxury Isn’t More Stuff. It’s More Time.

For a long time, success was easy to picture. A bigger house, a newer car, better holidays and more visible signs that things were going well. But for many people, particularly once careers become established and family life gets busier, the thing that starts to feel most valuable is something much less tangible: time.

Time with children before they grow up. Time to travel while you are healthy enough to enjoy it. Time to exercise, see friends, care for parents or simply have a Friday afternoon when nobody needs anything from you. Increasingly, financial planning is not just about accumulating more. It is about creating more choice over how you spend your time.

When earning more doesn’t always feel like having more

One of the strange things about modern life is that income can rise while life still feels increasingly squeezed. A more senior job may bring a larger salary, but it can also bring longer hours, greater responsibility and less freedom. A bigger house can be wonderful, but it may also mean a larger mortgage and more pressure to maintain the income required to pay for it.

Over time, some people reach a point where they start asking a different question. Instead of focusing on how they can earn more, they begin to ask how much they actually need. That can be a surprisingly powerful shift because it changes the role money plays. Rather than simply being something to accumulate, it becomes a tool for creating greater flexibility.

What would you do with an extra day?

Imagine someone told you that from next year, every Friday was yours. No work, no emails and no meetings. What would you do with it?

Some people would spend more time with family. Others might take up something they have been putting off for years, travel more or simply enjoy having a little more space in the week. The interesting thing is that these are not really financial goals, but money can determine whether they are possible.

That is where financial planning becomes less about numbers on a statement and more about designing the life those numbers are supposed to support. Knowing what you can afford can sometimes open up options that had previously felt unrealistic.

Financial freedom doesn’t have to start at retirement

We often talk about financial independence as though it is a single destination. You work full time, save as much as you can, retire and then finally gain complete control over your time.

Real life does not have to work like that.

Financial freedom can arrive gradually. It might mean moving from five days a week to four, taking a three-month sabbatical, changing to a job you enjoy more even if it pays slightly less, taking a longer holiday, or deciding in your late fifties that you no longer need to chase the next promotion.

None of those decisions necessarily requires someone to be extraordinarily wealthy. What they do require is an understanding of what is affordable, what needs to be protected and how different choices could affect the longer-term picture.

The danger of waiting for “one day”

There is an understandable tendency to postpone enjoyment. One day we will travel more. One day we will slow down. One day we will spend more time with the grandchildren. One day we will finally use some of the money we have spent decades building.

Planning for the future is important, but there is also a risk in assuming the future will always provide the same opportunities that exist today. Health changes, families change, children grow up and priorities shift. The aim of good financial planning should not be to spend everything now, but neither should it be to preserve every possible pound for later.

The challenge is finding the balance between enjoying life today and protecting the future you still want.

Sometimes the most useful number is “enough”

This is why one of the most valuable things financial planning can provide is clarity around what “enough” actually looks like.

How much income do you really need? How much should you keep in reserve? What would happen if you worked one day less each week? Could you retire earlier than you thought? Could you help your children now without compromising your own future?

Once those questions have answers, money can begin to feel less like something that simply needs to be accumulated and more like something that gives you choices.

Sometimes those choices are about buying something. But sometimes the thing you are buying is time.

A different definition of wealth

A healthy financial position will always matter, as will savings, pensions and investments. But perhaps wealth is broader than the value of everything you own.

It can also mean having enough flexibility to work a little less, take the trip, help your family, retire earlier or simply decide that you have enough.

Because the real value of money is not just what it allows you to own. It is what it allows you to do.

And increasingly, perhaps the greatest luxury of all is having more control over your own time.

lifestyle inflation

Lifestyle Inflation: Why Earning More Doesn’t Always Mean Feeling Better Off

A pay rise is usually something to celebrate.

After months or years of hard work, seeing your salary increase should, in theory, leave you feeling more financially secure. Yet many people are surprised to find that, a year later, they don’t feel much better off than they did before.

So, what happened?

Often, the answer is something known as lifestyle inflation.

What Is Lifestyle Inflation?

Lifestyle inflation happens when our spending gradually rises alongside our income.

It rarely happens overnight. Instead, it creeps in quietly.

Perhaps you start eating out a little more often. You upgrade your car sooner than planned, subscribe to another streaming service, book a more expensive holiday or move into a larger home.

None of these decisions are necessarily wrong. In fact, one of the rewards of working hard is being able to enjoy the things that matter to you.

The challenge is when every pay rise is absorbed into higher day-to-day spending, leaving little improvement in your long-term financial position.

It’s More Common Than You Might Think

Behavioural economists have long recognised a phenomenon known as hedonic adaptation, sometimes referred to as the hedonic treadmill. It describes our tendency to quickly become accustomed to improvements in our circumstances. A pay rise, a newer car or a bigger home may initially feel like a significant step up, but over time those things become our new normal and the satisfaction they bring begins to fade. The concept is explored in the Behavioural Economics Guide to Hedonic Adaptation.

Economist Richard Easterlin’s work on income and happiness also found that as our income rises, our expectations often rise alongside it, meaning yesterday’s luxury can soon feel like today’s necessity. You can read more in his paper, Income and Happiness: Towards a Unified Theory.

This helps explain why earning more does not always lead to feeling wealthier. Without consciously deciding where additional income should go, higher earnings can gradually be absorbed into higher everyday spending, leaving little improvement in long-term financial security.

The result is that, despite earning more than ever before, many people continue to feel as though they’re living from one payday to the next.

A Different Way to Think About a Pay Rise

Rather than asking, “What can I spend this on?”, it can be worth asking a different question:

“What opportunity does this extra income give me?”

It might allow you to:

  • build an emergency fund more quickly;
  • increase your pension contributions;
  • invest for the future;
  • reduce your mortgage sooner; or
  • save towards a goal that’s been on hold.

Of course, it’s important to enjoy your success too. The aim isn’t to avoid spending altogether, but to strike a balance between enjoying today and preparing for tomorrow.

The 50:50 Approach

One simple strategy some people find helpful is to split any pay rise.

For example, if your take-home pay increases by £200 a month, you might choose to enjoy £100 of that increase while directing the other £100 towards savings, investments or your pension.

This allows your lifestyle to improve without missing the opportunity to strengthen your long-term financial security.

Over time, even relatively modest amounts can make a meaningful difference.

Small Changes Can Have a Big Impact

Imagine receiving a pay rise every few years throughout your career.

If each increase resulted in just a small boost to your pension contributions or regular savings, those additional amounts could benefit from years, or even decades, of compound growth.

It’s one of the reasons financial planning is often about consistency rather than dramatic decisions.

Small improvements, repeated over time, can produce significant results.

You should always remember Investing can help your money grow over time, although the value of investments can go down as well as up.

Making It Automatic

One of the easiest ways to avoid lifestyle inflation is to remove the decision altogether.

If you decide to increase your pension contributions or monthly savings, consider arranging for the money to leave your account shortly after you’re paid.

When saving happens automatically, you’re less likely to miss the money and less tempted to spend it elsewhere.

It’s Not About Spending Less

Lifestyle inflation isn’t something to fear.

There’s nothing wrong with enjoying the rewards of your hard work, taking better holidays or treating yourself and your family.

The key is making those choices deliberately rather than allowing spending to increase without really noticing.

Financial confidence often comes not from earning more, but from knowing your additional income is helping you move closer to the goals that matter most.

Final Thoughts

A pay rise creates an opportunity, but what happens next is often more important than the increase itself.

Rather than allowing every extra pound to disappear into everyday spending, taking a moment to think about your longer-term priorities can have a lasting impact.

After all, the most valuable pay rise isn’t always the one that changes your lifestyle the most. Sometimes, it’s the one that changes your future.

Pensioner Poverty

Pensioner Poverty in the UK: Why It Still Matters

For many people, retirement is something to look forward to. After years of working and saving, it is a chance to enjoy more time with family, pursue hobbies and live life at a gentler pace.

However, the reality is not the same for everyone.

Recent government figures show that around 1.9 million pensioners in the UK are living in relative poverty after housing costs, equivalent to around 16% of all pensioners. While the increase compared with the previous year was not statistically significant, the figures are a reminder that financial security in retirement cannot be taken for granted.

What Does Pensioner Poverty Mean?

When people hear the word “poverty”, they often imagine people without enough to eat or somewhere to live.

The official measure is slightly different.

Relative poverty refers to households whose income is below 60% of the UK median income after housing costs. It is designed to show how people’s incomes compare with the rest of society, rather than simply whether they can meet their basic needs.

While many pensioners own their homes outright, others continue to rent or face rising living costs, making housing an important factor in retirement finances.

Why Are Some Pensioners Struggling?

There is rarely one single reason.

For some, retirement income simply hasn’t kept pace with increasing household costs.

Others may have spent time out of the workplace caring for family, worked part-time for much of their career or been unable to build significant private pension savings.

Life events can also have a lasting financial impact. Divorce, bereavement, ill health or retiring earlier than expected can all affect income later in life.

Research from Age UK consistently shows that single pensioners, particularly older women, are among those most at risk of financial hardship in retirement.

The Importance of Planning Early

One of the clearest lessons is that retirement planning is becoming increasingly important.

The State Pension provides an important foundation, but for some people it is unlikely to provide the retirement lifestyle they hope for on its own.

Building workplace pensions, making additional retirement savings where possible and reviewing retirement plans regularly can all make a significant difference over the long term.

Even small contributions made consistently over many years can have a meaningful impact thanks to investment growth and compound returns.

It’s Never Too Late to Review Your Plans

While starting early has advantages, reviewing your finances is valuable at any stage of life.

For those approaching retirement, understanding how different pensions, investments and savings work together can help provide greater clarity about future income.

For those already retired, reviewing expenditure, tax allowances, benefits and pension arrangements may identify opportunities to improve financial security.

For example, many pensioners who are entitled to Pension Credit do not claim it, despite it potentially increasing income and unlocking access to additional support. Information about eligibility is available through Pension Credit on GOV.UK.

Where investing forms part of your plans, it’s important to remember that while investments can help your money grow over time, their value can go down as well as up.

Looking Ahead

Retirement should be about having choices and confidence, not worrying about whether your income will last.

While government support plays an important role, personal planning remains one of the most effective ways to improve financial resilience in later life.

Whether you are in the journey into retirement, taking time to understand your current position and review your long-term plans can help ensure that your finances continue to support the lifestyle you want.

After all, good financial planning is not simply about building wealth. It is about creating the confidence to enjoy it when the time comes.


Approver Quilter Financial Services Limited. Aug 2026

September

September: Britain’s Second New Year

For many of us, January is seen as the time for fresh starts. We set New Year’s resolutions, join gyms, promise to get organised and think about the year ahead.

But ask many people when life really starts to feel “back to normal”, and they’ll often say September.

The summer holidays are over. Children return to school. Commutes become busier. Diaries begin to fill up again, and routines that paused for a few weeks begin to reappear.

In many ways, September feels like Britain’s second New Year.

It also makes it an excellent time to take stock of your finances.

A Natural Reset

Behavioural psychologists have identified what they call the “fresh start effect”. Research suggests that people are more motivated to adopt new habits following what researchers describe as “temporal landmarks”. These are moments that create the feeling of a new chapter, whether that’s a birthday, the start of a new job, New Year’s Day or the beginning of a new school year.

September provides exactly that.

It offers a natural opportunity to pause, reflect and think about where you are today, and where you’d like to be in the future.

A Good Time for a Financial Health Check

Just as many of us use September to organise wardrobes, calendars or the children’s school bags, it can also be a useful time to organise our finances.

That doesn’t necessarily mean making dramatic changes.

Sometimes it’s simply about asking a few straightforward questions.

  • Are you still saving enough towards your long-term goals?
  • Have your spending habits changed over the summer?
  • Is your emergency fund where you’d like it to be?
  • Have you reviewed your pension recently?
  • Are your investments still aligned with your objectives?

Small reviews carried out regularly can often be more valuable than major changes every few years.

Life Doesn’t Stand Still

One of the reasons financial planning is an ongoing process is that life rarely stands still.

Children become financially independent. Careers evolve. Retirement moves closer. Parents grow older. Priorities change.

The financial plan that suited you five years ago may no longer reflect your circumstances today.

September can provide a useful reminder to check whether your plans are still supporting the life you’re trying to build.

Looking Ahead, Not Just Looking Back

The final few months of the year often disappear surprisingly quickly.

Before long, Christmas arrives, followed by another New Year and another list of resolutions.

Taking stock in September gives you the opportunity to make considered decisions before life becomes busier again.

Whether that’s increasing pension contributions, reviewing your investments, updating your Will or simply putting a little more aside each month, small actions now can have a meaningful impact over time.

Final Thoughts

Financial planning isn’t something that should only happen when markets move dramatically or tax rules change.

Sometimes, the best time to review your finances is simply when life gives you a natural opportunity to pause and take stock.

September offers exactly that. Before the final few months of the year gather pace, it can be the perfect moment to ask a simple question:

“Am I still on track for the future I want?”

If you’re not sure of the answer, that’s often the best place to start the conversation.


Source: The concept of the Fresh Start Effect was introduced by researchers at the Wharton School, including Katherine Milkman, who found that temporal landmarks such as the start of a new month, birthday or school year can motivate people to pursue goals and adopt positive behaviours. Read more in the paper The Fresh Start Effect: Temporal Landmarks Motivate Aspirational Behaviour published in Management Science: https://pubsonline.informs.org/doi/10.1287/mnsc.2014.1901


Approver Quilter Financial Services Limited. Aug 2026

Banner Template

Inflation Is Rising Again. What Does It Actually Mean for Your Money?

After several months of encouraging news, UK inflation has begun to edge upwards again.

The latest figures show the Consumer Prices Index (CPI) rose to 2.9% in July, up from 2.6% in June. Much of the increase has been driven by higher household energy bills following a rise in the energy price cap, itself linked to higher wholesale energy prices after recent tensions in the Middle East.

For many people, hearing that “inflation is rising” immediately brings back memories of the cost of living crisis.

But does this latest increase mean we’re heading back to those levels of inflation?

Not necessarily.

What Is Inflation?

Inflation measures how quickly the prices of goods and services are increasing over time.

If inflation is running at 2.9%, something that cost £100 a year ago would, on average, now cost £102.90.

The Bank of England’s target is 2%, which is generally considered a healthy level that supports economic growth without allowing prices to rise too quickly.

While the latest figure is above that target, it remains well below the levels experienced during the inflation surge of 2022 and 2023.

Why Has Inflation Increased?

The biggest factor this time is energy.

Higher wholesale gas prices have fed through into household bills following a 13% increase in the energy price cap in July. Energy costs affect almost every part of the economy, from heating our homes to transporting goods around the country, so increases can have a wider knock-on effect on prices.

There were also smaller contributions from areas such as furniture and clothing, where seasonal discounts were less pronounced than usual.

The important point is that this rise has been driven largely by external factors rather than a broad-based surge in domestic demand.

What Could It Mean for Interest Rates?

Whenever inflation rises, attention quickly turns to the Bank of England.

Higher inflation can sometimes lead to higher interest rates as policymakers try to slow spending and bring price growth back under control.

However, the picture is more balanced than it first appears.

Although headline inflation has increased, core inflation remained at 2.6%, while wage growth has continued to slow and the labour market has shown signs of cooling. In its latest Monetary Policy Report, the Bank of England said there were “clear signs of underlying disinflation” and “little evidence so far” that higher energy prices had led to broader inflationary pressures. As a result, many economists believe the Bank may not need to respond as aggressively as it did during the previous inflation spike.

What Does This Mean for Households?

For most households, the immediate impact is likely to be felt through higher energy bills and continued pressure on everyday living costs.

However, it’s worth remembering that inflation affects everyone differently.

Someone who spends more on travel or energy may notice the increase more than someone whose spending is concentrated elsewhere.

While individual prices will continue to rise and fall, it is usually long-term trends rather than month-to-month movements that matter most when making financial decisions.

Staying Focused on the Long Term

Inflation is one of those economic indicators that naturally attracts headlines.

But history shows that it moves in cycles.

There will always be periods when inflation rises and periods when it falls. Trying to make significant financial decisions based on a single month’s data rarely proves beneficial.

Instead, it is often more helpful to focus on the things you can control:

  • reviewing your household budget;
  • maintaining appropriate emergency savings;
  • ensuring your investments remain aligned with your long-term objectives; and
  • reviewing your financial plan regularly as circumstances change.

Final Thoughts

The latest inflation figures are a reminder that economic conditions continue to evolve.

While rising prices are never welcome, today’s environment looks very different from the inflation shock experienced just a few years ago.

For most people, the best approach remains the same: understand what is changing, avoid reacting to short-term headlines and keep your long-term financial plan under regular review.

cookie

Why Good Financial Habits Should Require Less Willpower

Most of us know roughly what we should be doing with our money.

Pay the bills on time. Build an emergency fund. Save regularly. Contribute towards retirement. Put money aside for larger annual costs.

The difficult part is doing all of those things consistently while managing work, family and everything else competing for our attention.

This is where financial automation can be particularly useful. By arranging for certain decisions to happen automatically, we can reduce the amount of time, effort and willpower required to stay on track.

The aim is not to remove all thought from managing money. It is to make sensible financial habits the default, rather than something we have to remember to do every month.

Why Willpower Is Not Always Enough

It is easy to assume that good money management is simply a matter of discipline.

In reality, even the most organised people can forget a payment, postpone transferring money into savings or gradually spend what remains in their account before reaching the end of the month.

Every financial decision requires a small amount of mental effort. Individually, those decisions may feel insignificant, but together they can contribute to what is sometimes called decision fatigue.

Automation reduces the number of decisions we need to make repeatedly. Once an appropriate system has been established, it can continue working quietly in the background.

Instead of deciding each month whether to save, the money moves automatically. Instead of hoping enough remains for an annual insurance premium or family holiday, a smaller amount can be set aside throughout the year.

The Power of Making Something the Default

One of the clearest demonstrations of this principle can be found in workplace pensions.

Before automatic enrolment, employees generally had to make an active decision to join a workplace pension. Many did not, even where saving for retirement would have been beneficial.

Automatic enrolment changed the starting position. Eligible employees were placed into a pension unless they chose to leave, making long-term saving the default rather than an additional task.

In 2024, 89% of eligible employees in Great Britain were saving into a workplace pension. It is a powerful example of how changing the system around a decision can sometimes have a greater effect than repeatedly asking people to make the right choice.

The same principle can be applied to other areas of personal finance.

Paying Yourself First

Many people intend to save whatever is left at the end of the month.

The difficulty is that there is not always very much left.

An alternative is to arrange for money to move into savings shortly after income arrives. This is sometimes described as paying yourself first.

The amount does not need to be large. What matters initially is creating a regular habit that reflects what you can genuinely afford.

Over time, automated contributions can help build an emergency fund, prepare for a specific purchase or support a longer-term goal. They also place the money slightly further out of reach, reducing the temptation to spend it impulsively.

Preparing for the Costs That Do Not Arrive Monthly

Not every expense fits neatly into a monthly budget.

Christmas, holidays, car maintenance, insurance renewals and home repairs can all feel unexpected, despite being reasonably predictable.

Creating separate savings pots and making regular transfers into them can turn one large future bill into a series of smaller, more manageable amounts.

This does not necessarily reduce the overall cost, but it can reduce the financial shock when payment is due.

It can also make spending more enjoyable. A holiday paid for from money deliberately set aside may feel very different from one followed by several months of credit card repayments.

Automating Long-Term Saving and Investing

Regular contributions can also support longer-term financial planning.

Making contributions at set intervals removes the pressure of trying to identify the perfect moment to invest. Markets will naturally rise and fall, and regular investing means money is added across a range of different market conditions.

However, investments can fall as well as rise, and regular contributions do not guarantee a positive return. The amount invested, the level of risk and the investments selected should remain appropriate for your circumstances and goals.

Automation should support a considered financial plan, not replace one.

Making More of a Pay Rise

A pay rise is another point at which automation can be useful.

As income increases, spending often rises with it. This is sometimes known as lifestyle inflation. It may happen gradually, without us consciously deciding to change how we live.

Before becoming accustomed to the full increase, some people choose to direct a proportion of it towards savings, pensions or investments.

That still leaves room to enjoy the benefits of earning more, while also using part of the increase to strengthen future financial security.

What Should Not Be Left on Autopilot?

Automation can be helpful, but it should not mean ignoring your finances completely.

Direct Debits can continue long after a service has stopped providing value. Savings accounts can become uncompetitive. Insurance policies may no longer reflect your needs, and investment arrangements should be reviewed as circumstances and objectives change.

Credit card payments also require particular care. Automatically paying only the minimum amount can keep an account technically up to date while allowing interest and debt to build over time.

A sensible approach is to automate the regular activity, then review the wider arrangements periodically.

Think of it less as switching your finances off and more as installing a system that still requires occasional maintenance.

Small Systems, Repeated Over Time

Financial progress rarely comes from one dramatic decision.

More often, it is the result of small actions repeated consistently over many years.

Automating bills, savings and long-term contributions cannot remove every financial concern. Nor can it compensate for a budget that is already stretched beyond what is affordable.

But where there is room to save, it can make positive habits easier to maintain and reduce the likelihood that important goals are continually postponed.

Banner Template

A Fantastic Day at the Digby Associates Family Fun Day

There is something special about bringing people together away from the office, and this year’s Digby Associates Family Fun Day was exactly that.

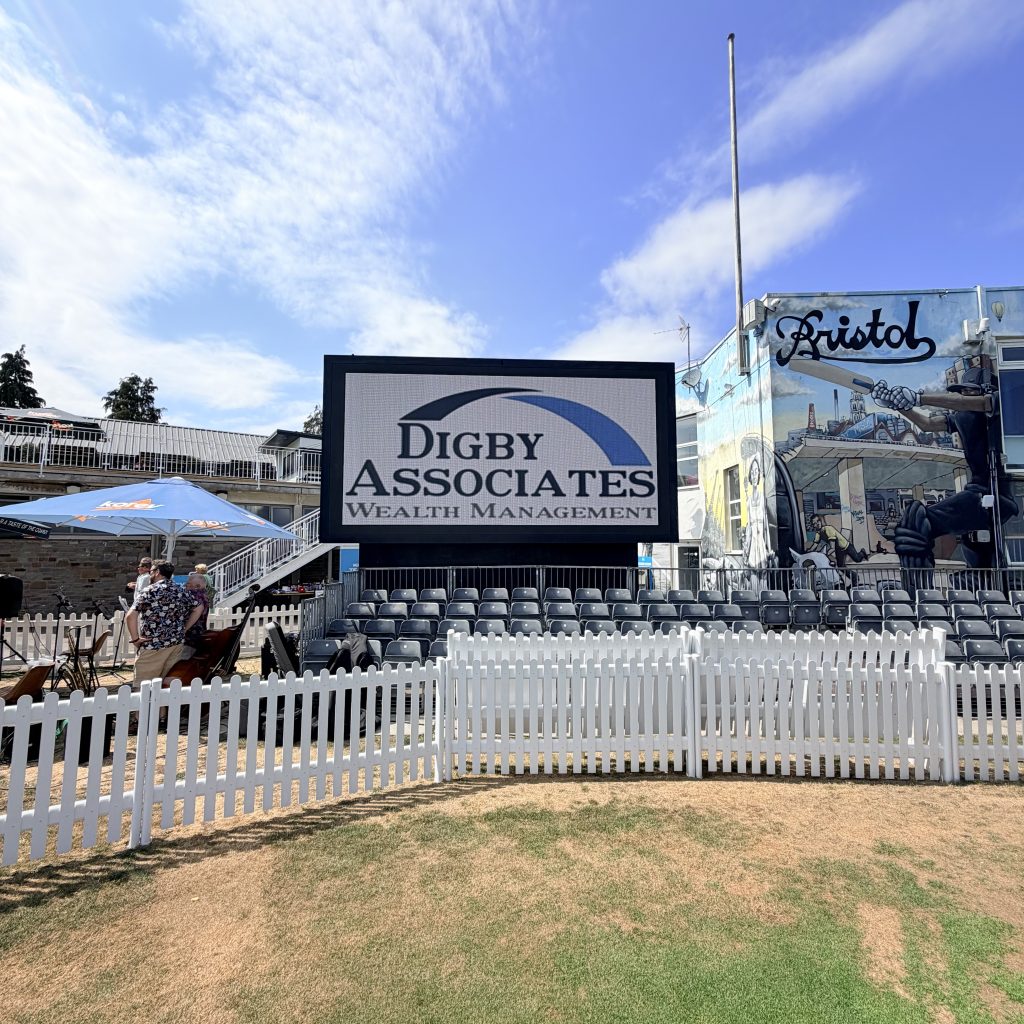
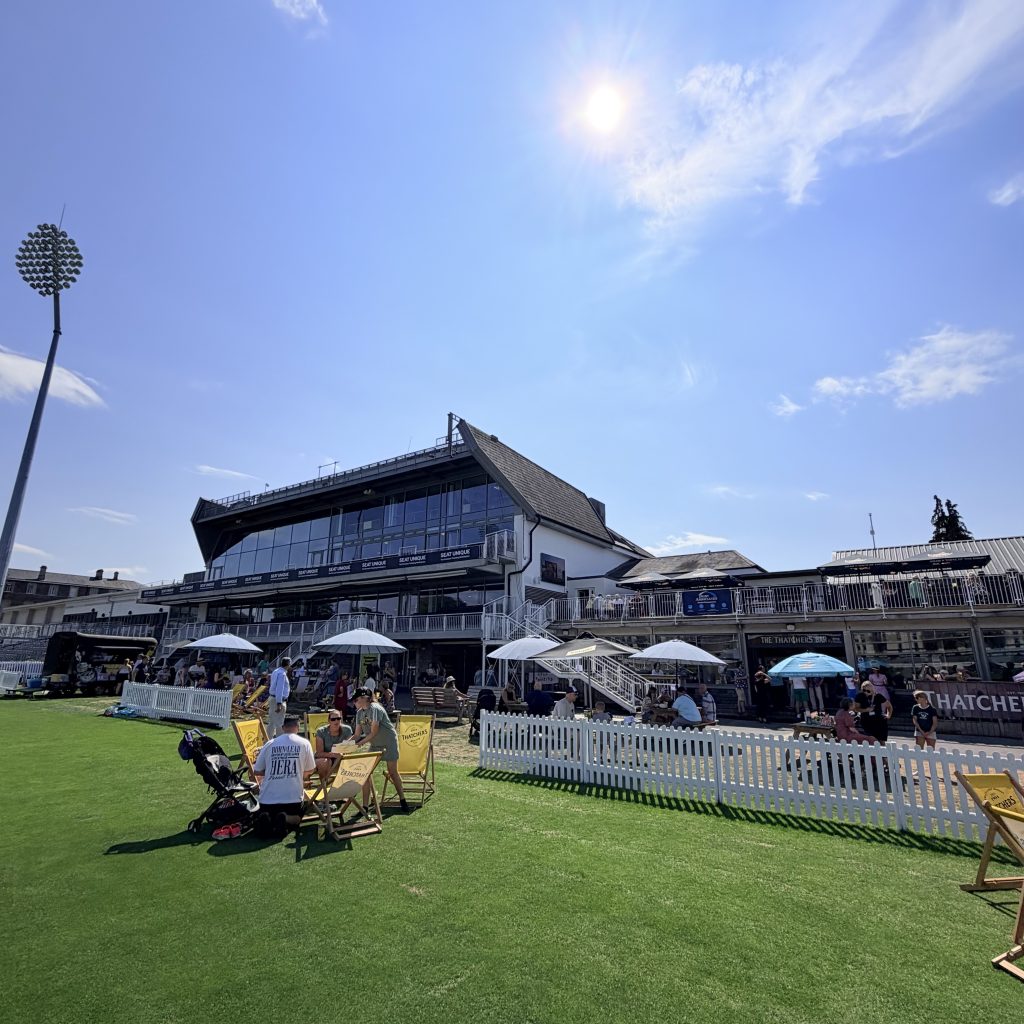
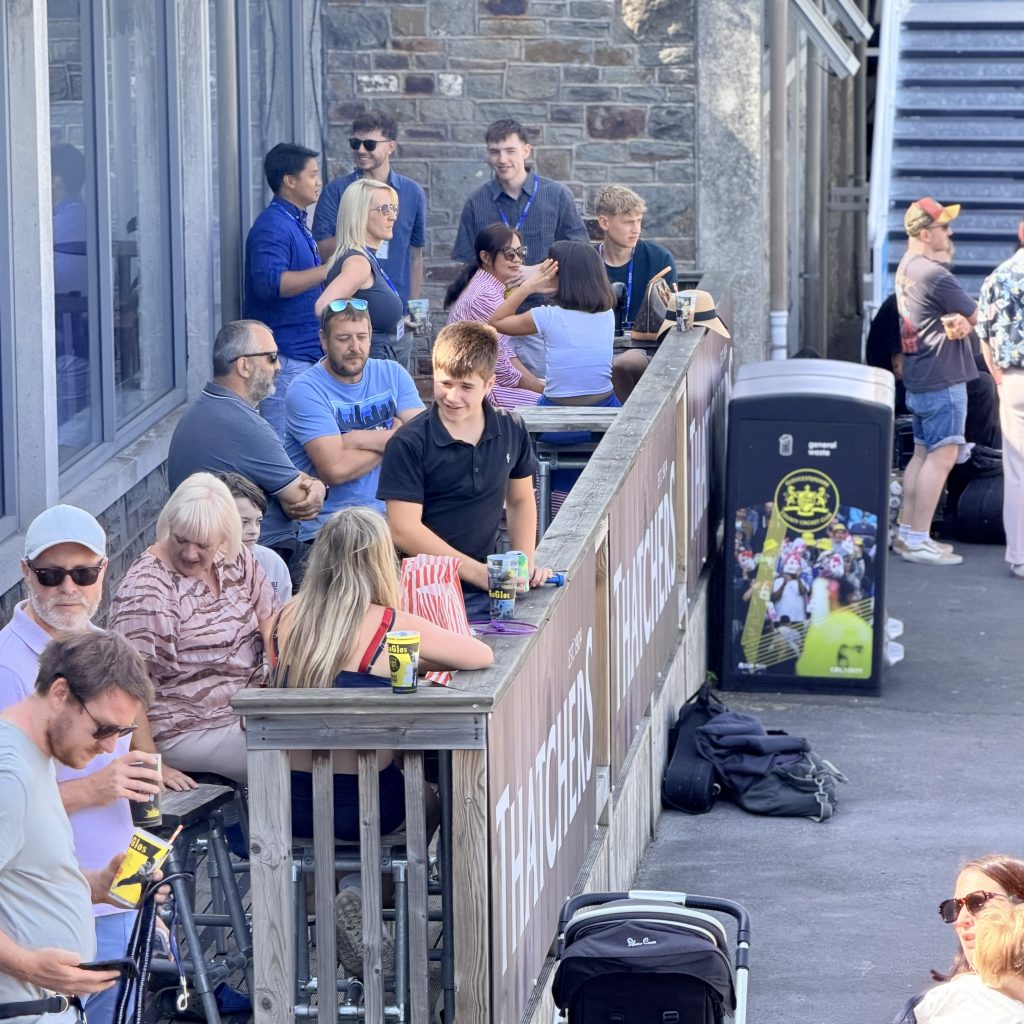
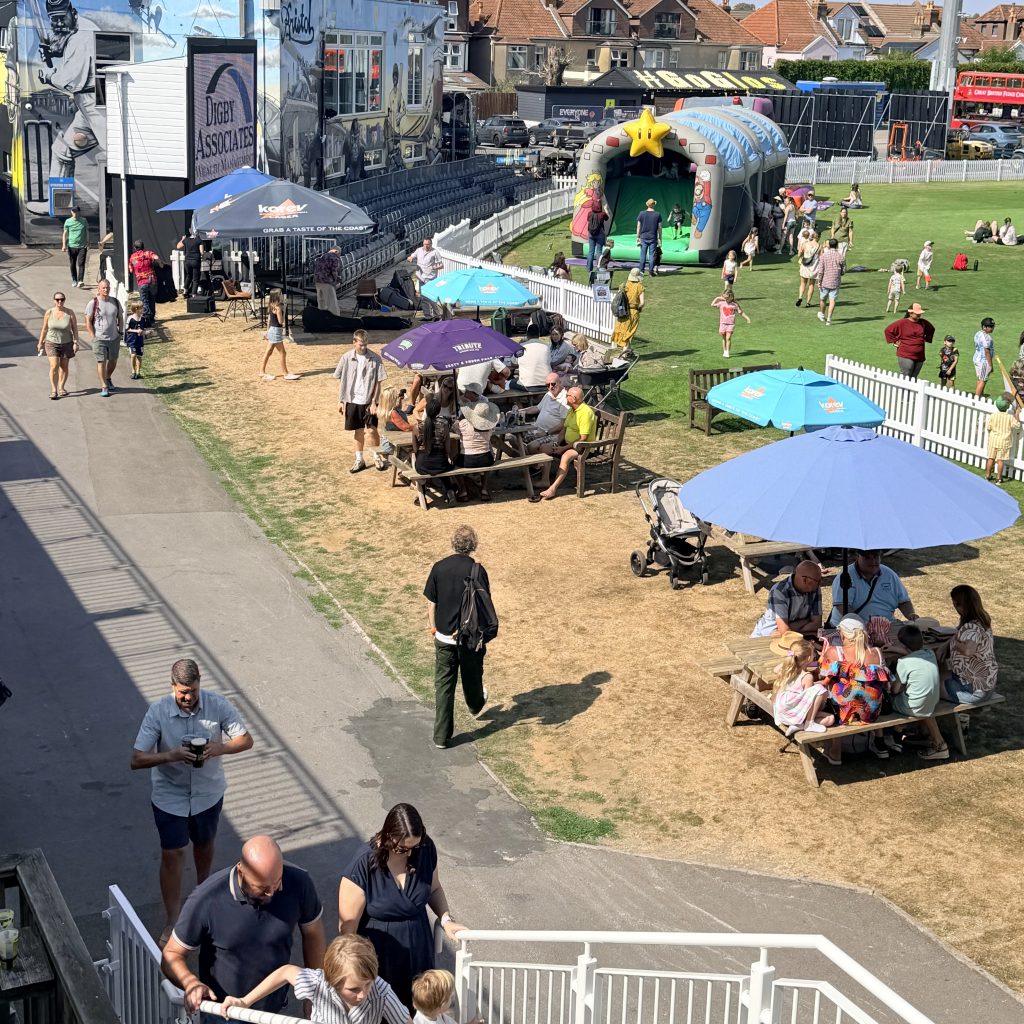
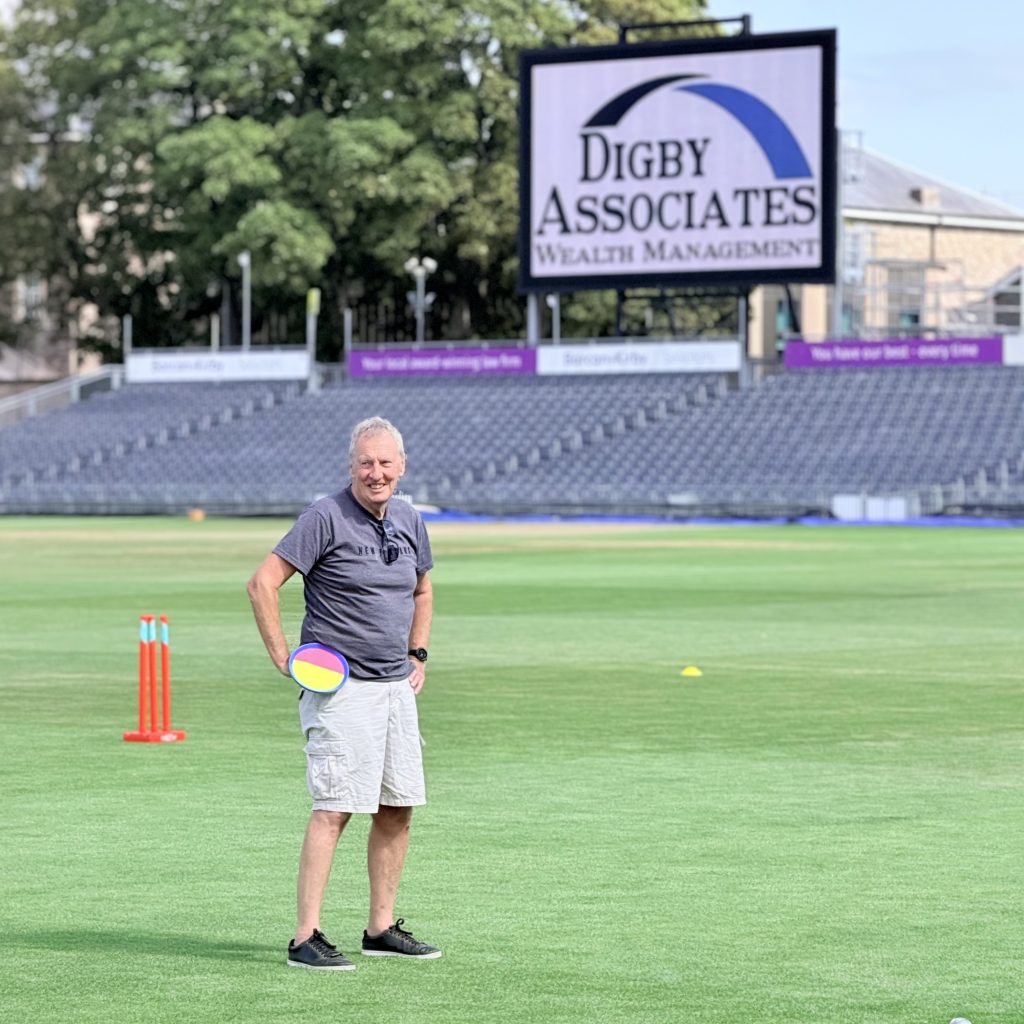
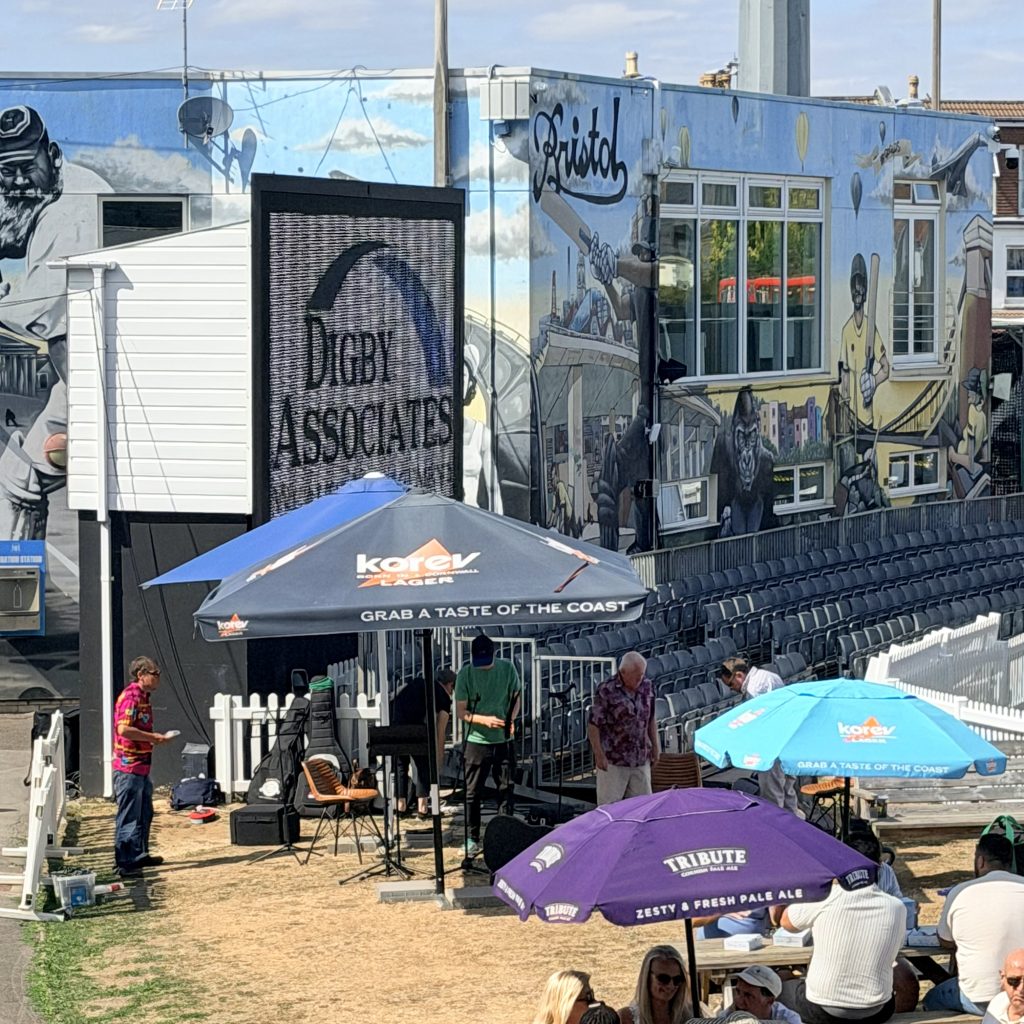
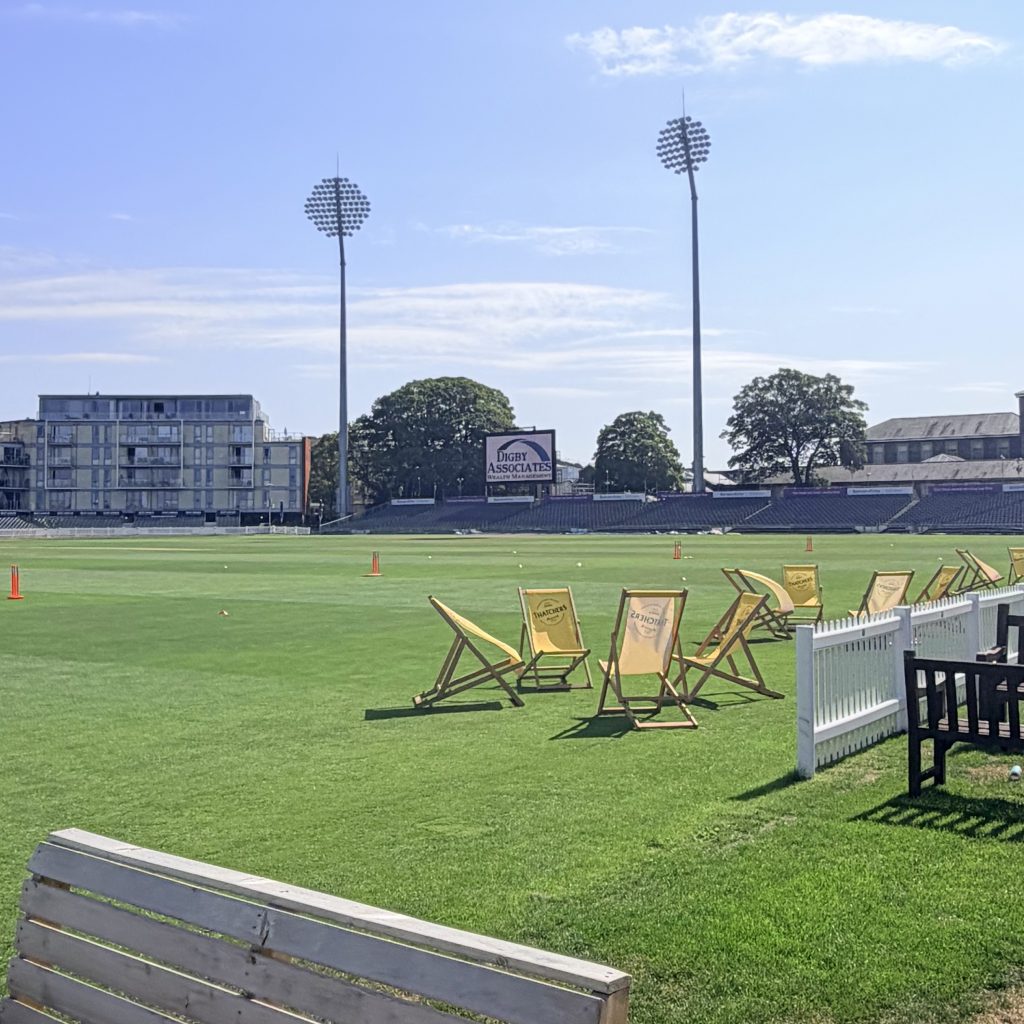
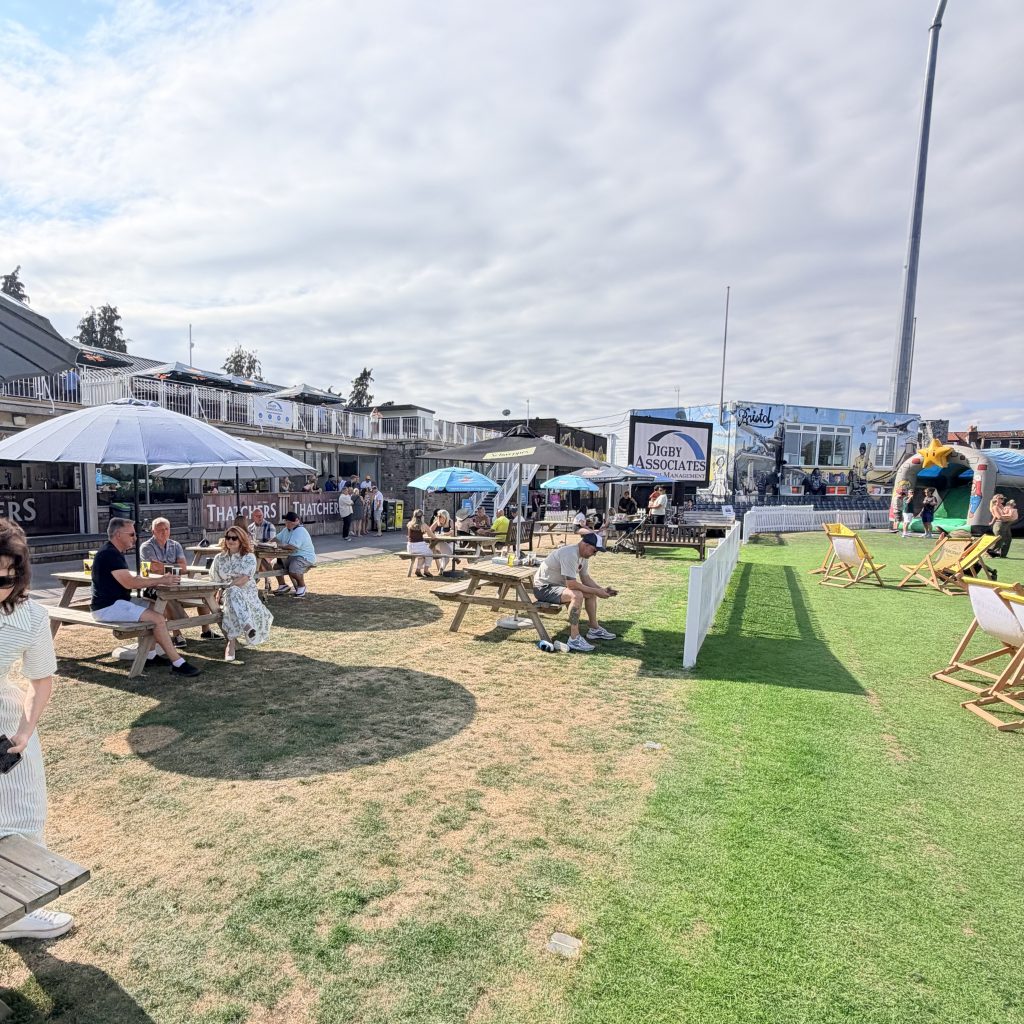
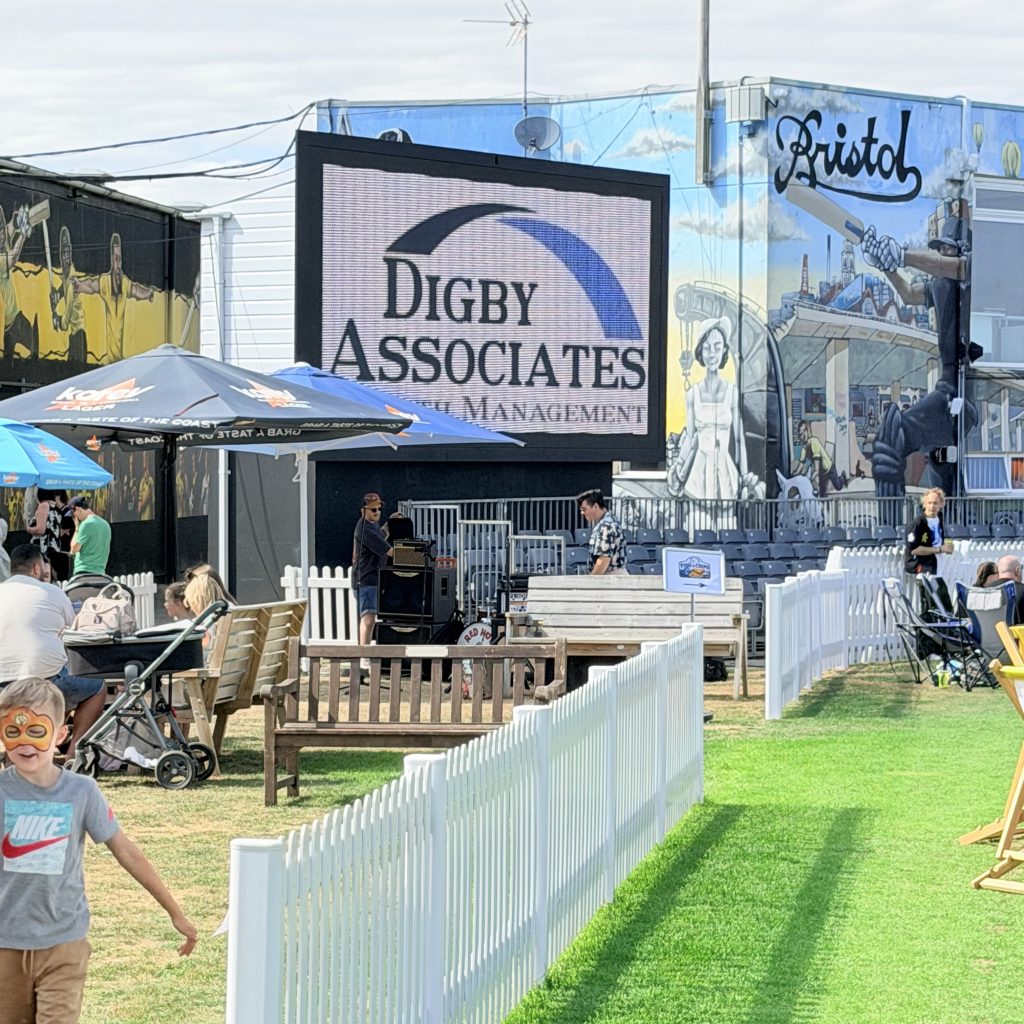
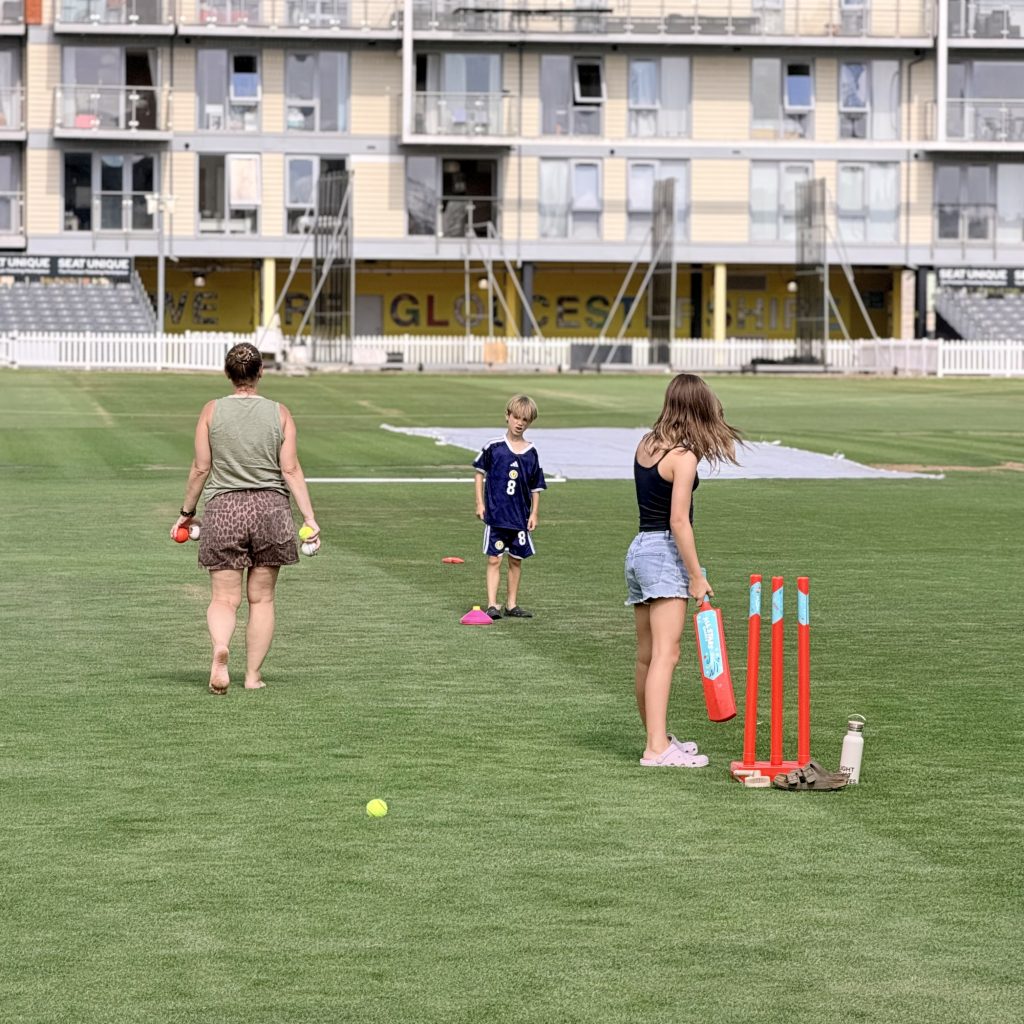
Held at the beautiful Gloucestershire County Cricket Club on Saturday, the Family Fun Day was organised to raise money for good causes while bringing together colleagues, clients, friends and families for an afternoon of fun. It was a fantastic opportunity to catch up with familiar faces, make new memories and support an important cause at the same time.

With glorious weather, a fantastic atmosphere and activities for all ages, it proved to be a wonderful celebration of the people who make Digby Associates what it is.

Bringing People Together

Whether we’re supporting clients through important financial decisions or working together as colleagues, those relationships are built on trust, conversation and genuine care.

Our Family Fun Day was a chance to celebrate those values outside the workplace, bringing together the charity partners, the wider Digby Associates family in a relaxed and enjoyable setting.

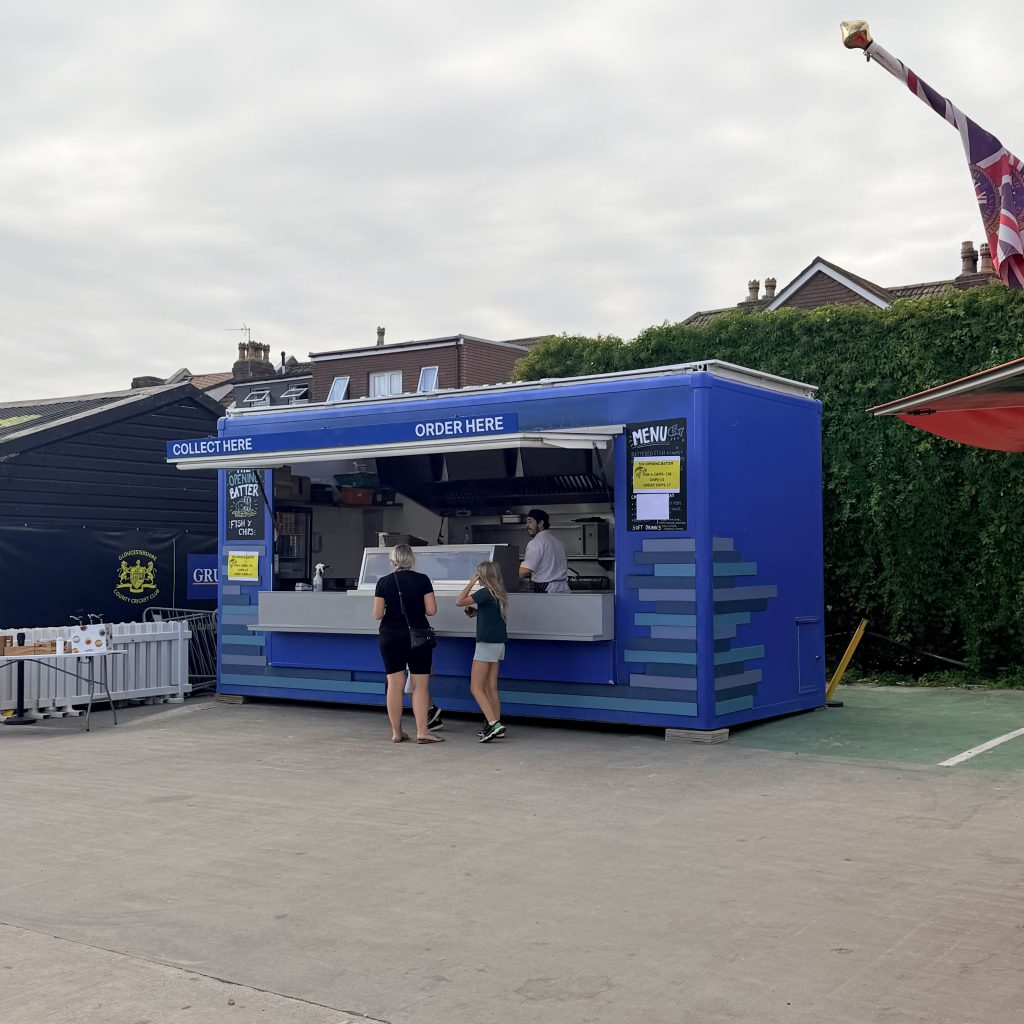
It was fantastic to see so many people there, from young children enjoying the activities to colleagues and clients taking the opportunity to catch up over food and refreshments.

Plenty to Enjoy

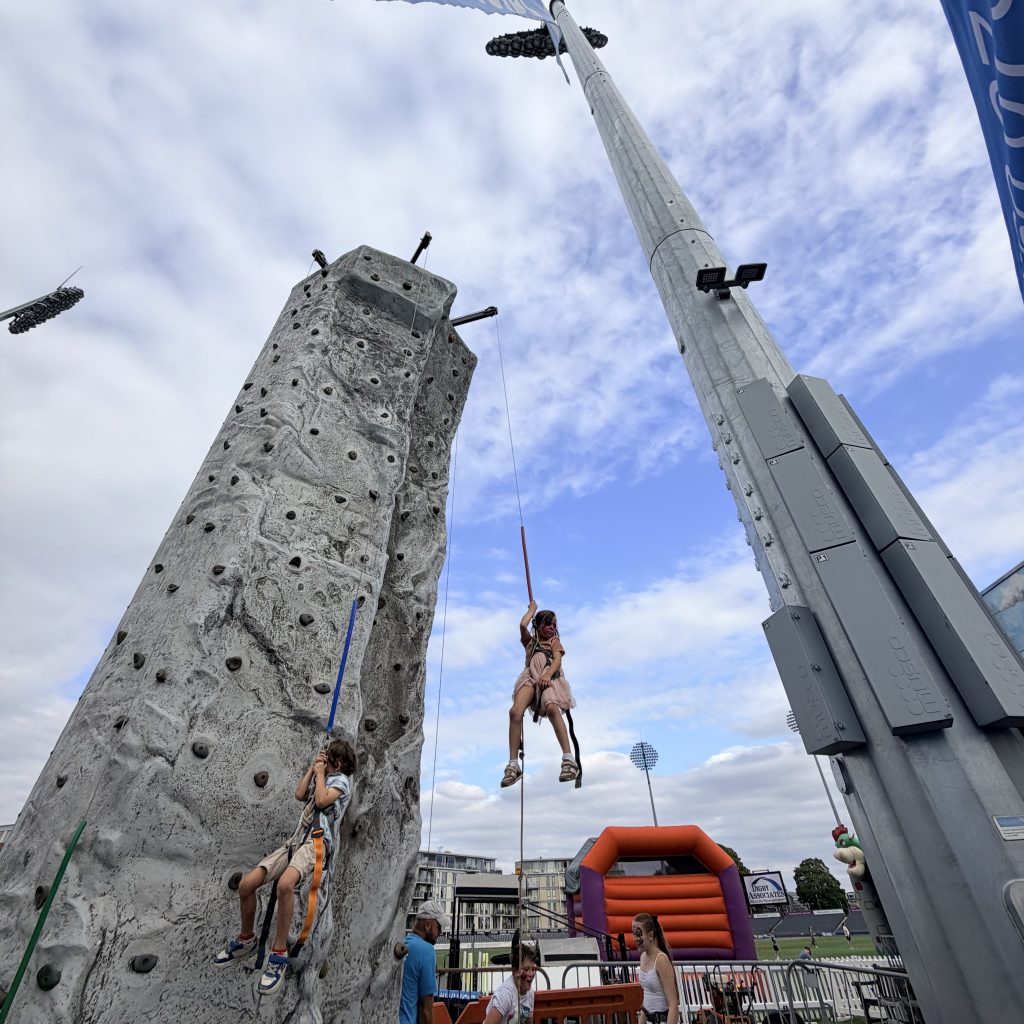
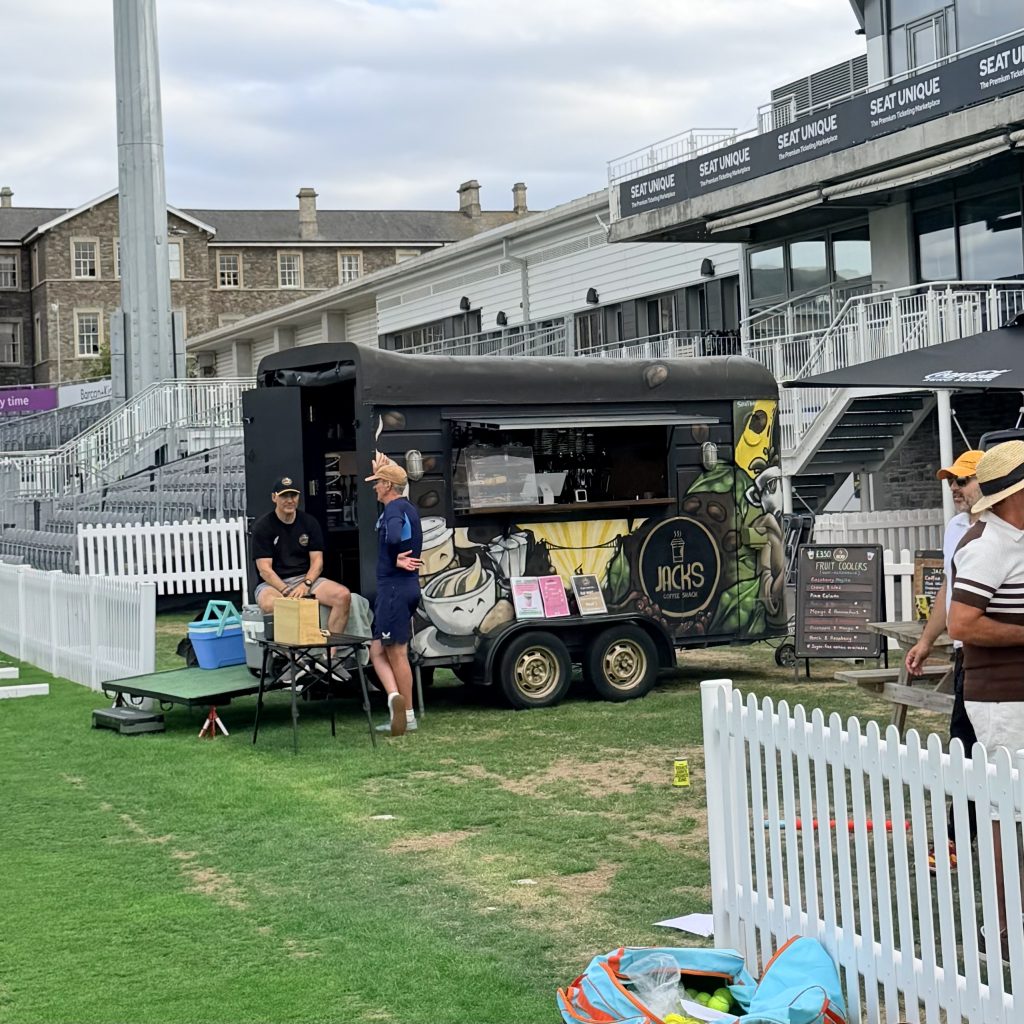
This year we had a really fantastic mix of activities, including Jack’s Coffee Stand, the Fudge Bus from Great British Fudge Company, a climbing wall from Mojo Active, as well as bouncy castles, face painting, a charity raffle with prizes donated by Digby Associates and partner businesses, live music from a local band and plenty of casual cricket activities.

Families enjoyed a wide range of activities, children embraced every opportunity to play, and there was plenty of laughter from start to finish. Gloucestershire County Cricket Club provided the perfect backdrop for the event, creating a relaxed setting where everyone could enjoy the afternoon at their own pace.

Thank You

A huge thank you to everyone who came along and helped make the day such a success.

Thank you also to everyone behind the scenes who organised the event, our charity partners, local businesses that got involved and to Gloucestershire County Cricket Club for being such fantastic hosts.

We hope everyone had as much fun as we did.

Take a look through some of the moments from the day in the gallery below.