Pensioner Poverty

Pensioner Poverty in the UK: Why It Still Matters

For many people, retirement is something to look forward to. After years of working and saving, it is a chance to enjoy more time with family, pursue hobbies and live life at a gentler pace.

However, the reality is not the same for everyone.

Recent government figures show that around 1.9 million pensioners in the UK are living in relative poverty after housing costs, equivalent to around 16% of all pensioners. While the increase compared with the previous year was not statistically significant, the figures are a reminder that financial security in retirement cannot be taken for granted.

What Does Pensioner Poverty Mean?

When people hear the word “poverty”, they often imagine people without enough to eat or somewhere to live.

The official measure is slightly different.

Relative poverty refers to households whose income is below 60% of the UK median income after housing costs. It is designed to show how people’s incomes compare with the rest of society, rather than simply whether they can meet their basic needs.

While many pensioners own their homes outright, others continue to rent or face rising living costs, making housing an important factor in retirement finances.

Why Are Some Pensioners Struggling?

There is rarely one single reason.

For some, retirement income simply hasn’t kept pace with increasing household costs.

Others may have spent time out of the workplace caring for family, worked part-time for much of their career or been unable to build significant private pension savings.

Life events can also have a lasting financial impact. Divorce, bereavement, ill health or retiring earlier than expected can all affect income later in life.

Research from Age UK consistently shows that single pensioners, particularly older women, are among those most at risk of financial hardship in retirement.

The Importance of Planning Early

One of the clearest lessons is that retirement planning is becoming increasingly important.

The State Pension provides an important foundation, but for some people it is unlikely to provide the retirement lifestyle they hope for on its own.

Building workplace pensions, making additional retirement savings where possible and reviewing retirement plans regularly can all make a significant difference over the long term.

Even small contributions made consistently over many years can have a meaningful impact thanks to investment growth and compound returns.

It’s Never Too Late to Review Your Plans

While starting early has advantages, reviewing your finances is valuable at any stage of life.

For those approaching retirement, understanding how different pensions, investments and savings work together can help provide greater clarity about future income.

For those already retired, reviewing expenditure, tax allowances, benefits and pension arrangements may identify opportunities to improve financial security.

For example, many pensioners who are entitled to Pension Credit do not claim it, despite it potentially increasing income and unlocking access to additional support. Information about eligibility is available through Pension Credit on GOV.UK.

Where investing forms part of your plans, it’s important to remember that while investments can help your money grow over time, their value can go down as well as up.

Looking Ahead

Retirement should be about having choices and confidence, not worrying about whether your income will last.

While government support plays an important role, personal planning remains one of the most effective ways to improve financial resilience in later life.

Whether you are in the journey into retirement, taking time to understand your current position and review your long-term plans can help ensure that your finances continue to support the lifestyle you want.

After all, good financial planning is not simply about building wealth. It is about creating the confidence to enjoy it when the time comes.


Approver Quilter Financial Services Limited. Aug 2026
September

September: Britain’s Second New Year

For many of us, January is seen as the time for fresh starts. We set New Year’s resolutions, join gyms, promise to get organised and think about the year ahead.

But ask many people when life really starts to feel “back to normal”, and they’ll often say September.

The summer holidays are over. Children return to school. Commutes become busier. Diaries begin to fill up again, and routines that paused for a few weeks begin to reappear.

In many ways, September feels like Britain’s second New Year.

It also makes it an excellent time to take stock of your finances.

A Natural Reset

Behavioural psychologists have identified what they call the “fresh start effect”. Research suggests that people are more motivated to adopt new habits following what researchers describe as “temporal landmarks”. These are moments that create the feeling of a new chapter, whether that’s a birthday, the start of a new job, New Year’s Day or the beginning of a new school year.

September provides exactly that.

It offers a natural opportunity to pause, reflect and think about where you are today, and where you’d like to be in the future.

A Good Time for a Financial Health Check

Just as many of us use September to organise wardrobes, calendars or the children’s school bags, it can also be a useful time to organise our finances.

That doesn’t necessarily mean making dramatic changes.

Sometimes it’s simply about asking a few straightforward questions.

  • Are you still saving enough towards your long-term goals?
  • Have your spending habits changed over the summer?
  • Is your emergency fund where you’d like it to be?
  • Have you reviewed your pension recently?
  • Are your investments still aligned with your objectives?

Small reviews carried out regularly can often be more valuable than major changes every few years.

Life Doesn’t Stand Still

One of the reasons financial planning is an ongoing process is that life rarely stands still.

Children become financially independent. Careers evolve. Retirement moves closer. Parents grow older. Priorities change.

The financial plan that suited you five years ago may no longer reflect your circumstances today.

September can provide a useful reminder to check whether your plans are still supporting the life you’re trying to build.

Looking Ahead, Not Just Looking Back

The final few months of the year often disappear surprisingly quickly.

Before long, Christmas arrives, followed by another New Year and another list of resolutions.

Taking stock in September gives you the opportunity to make considered decisions before life becomes busier again.

Whether that’s increasing pension contributions, reviewing your investments, updating your Will or simply putting a little more aside each month, small actions now can have a meaningful impact over time.

Final Thoughts

Financial planning isn’t something that should only happen when markets move dramatically or tax rules change.

Sometimes, the best time to review your finances is simply when life gives you a natural opportunity to pause and take stock.

September offers exactly that. Before the final few months of the year gather pace, it can be the perfect moment to ask a simple question:

“Am I still on track for the future I want?”

If you’re not sure of the answer, that’s often the best place to start the conversation.


Source: The concept of the Fresh Start Effect was introduced by researchers at the Wharton School, including Katherine Milkman, who found that temporal landmarks such as the start of a new month, birthday or school year can motivate people to pursue goals and adopt positive behaviours. Read more in the paper The Fresh Start Effect: Temporal Landmarks Motivate Aspirational Behaviour published in Management Science: https://pubsonline.informs.org/doi/10.1287/mnsc.2014.1901


Approver Quilter Financial Services Limited. Aug 2026
Banner Template

Inflation Is Rising Again. What Does It Actually Mean for Your Money?

After several months of encouraging news, UK inflation has begun to edge upwards again.

The latest figures show the Consumer Prices Index (CPI) rose to 2.9% in July, up from 2.6% in June. Much of the increase has been driven by higher household energy bills following a rise in the energy price cap, itself linked to higher wholesale energy prices after recent tensions in the Middle East.

For many people, hearing that “inflation is rising” immediately brings back memories of the cost of living crisis.

But does this latest increase mean we’re heading back to those levels of inflation?

Not necessarily.

What Is Inflation?

Inflation measures how quickly the prices of goods and services are increasing over time.

If inflation is running at 2.9%, something that cost £100 a year ago would, on average, now cost £102.90.

The Bank of England’s target is 2%, which is generally considered a healthy level that supports economic growth without allowing prices to rise too quickly.

While the latest figure is above that target, it remains well below the levels experienced during the inflation surge of 2022 and 2023.

Why Has Inflation Increased?

The biggest factor this time is energy.

Higher wholesale gas prices have fed through into household bills following a 13% increase in the energy price cap in July. Energy costs affect almost every part of the economy, from heating our homes to transporting goods around the country, so increases can have a wider knock-on effect on prices.

There were also smaller contributions from areas such as furniture and clothing, where seasonal discounts were less pronounced than usual.

The important point is that this rise has been driven largely by external factors rather than a broad-based surge in domestic demand.

What Could It Mean for Interest Rates?

Whenever inflation rises, attention quickly turns to the Bank of England.

Higher inflation can sometimes lead to higher interest rates as policymakers try to slow spending and bring price growth back under control.

However, the picture is more balanced than it first appears.

Although headline inflation has increased, core inflation remained at 2.6%, while wage growth has continued to slow and the labour market has shown signs of cooling. In its latest Monetary Policy Report, the Bank of England said there were “clear signs of underlying disinflation” and “little evidence so far” that higher energy prices had led to broader inflationary pressures. As a result, many economists believe the Bank may not need to respond as aggressively as it did during the previous inflation spike.

What Does This Mean for Households?

For most households, the immediate impact is likely to be felt through higher energy bills and continued pressure on everyday living costs.

However, it’s worth remembering that inflation affects everyone differently.

Someone who spends more on travel or energy may notice the increase more than someone whose spending is concentrated elsewhere.

While individual prices will continue to rise and fall, it is usually long-term trends rather than month-to-month movements that matter most when making financial decisions.

Staying Focused on the Long Term

Inflation is one of those economic indicators that naturally attracts headlines.

But history shows that it moves in cycles.

There will always be periods when inflation rises and periods when it falls. Trying to make significant financial decisions based on a single month’s data rarely proves beneficial.

Instead, it is often more helpful to focus on the things you can control:

  • reviewing your household budget;
  • maintaining appropriate emergency savings;
  • ensuring your investments remain aligned with your long-term objectives; and
  • reviewing your financial plan regularly as circumstances change.

Final Thoughts

The latest inflation figures are a reminder that economic conditions continue to evolve.

While rising prices are never welcome, today’s environment looks very different from the inflation shock experienced just a few years ago.

For most people, the best approach remains the same: understand what is changing, avoid reacting to short-term headlines and keep your long-term financial plan under regular review.

cookie

Why Good Financial Habits Should Require Less Willpower

Most of us know roughly what we should be doing with our money.

Pay the bills on time. Build an emergency fund. Save regularly. Contribute towards retirement. Put money aside for larger annual costs.

The difficult part is doing all of those things consistently while managing work, family and everything else competing for our attention.

This is where financial automation can be particularly useful. By arranging for certain decisions to happen automatically, we can reduce the amount of time, effort and willpower required to stay on track.

The aim is not to remove all thought from managing money. It is to make sensible financial habits the default, rather than something we have to remember to do every month.

Why Willpower Is Not Always Enough

It is easy to assume that good money management is simply a matter of discipline.

In reality, even the most organised people can forget a payment, postpone transferring money into savings or gradually spend what remains in their account before reaching the end of the month.

Every financial decision requires a small amount of mental effort. Individually, those decisions may feel insignificant, but together they can contribute to what is sometimes called decision fatigue.

Automation reduces the number of decisions we need to make repeatedly. Once an appropriate system has been established, it can continue working quietly in the background.

Instead of deciding each month whether to save, the money moves automatically. Instead of hoping enough remains for an annual insurance premium or family holiday, a smaller amount can be set aside throughout the year.

The Power of Making Something the Default

One of the clearest demonstrations of this principle can be found in workplace pensions.

Before automatic enrolment, employees generally had to make an active decision to join a workplace pension. Many did not, even where saving for retirement would have been beneficial.

Automatic enrolment changed the starting position. Eligible employees were placed into a pension unless they chose to leave, making long-term saving the default rather than an additional task.

In 2024, 89% of eligible employees in Great Britain were saving into a workplace pension. It is a powerful example of how changing the system around a decision can sometimes have a greater effect than repeatedly asking people to make the right choice.

The same principle can be applied to other areas of personal finance.

Paying Yourself First

Many people intend to save whatever is left at the end of the month.

The difficulty is that there is not always very much left.

An alternative is to arrange for money to move into savings shortly after income arrives. This is sometimes described as paying yourself first.

The amount does not need to be large. What matters initially is creating a regular habit that reflects what you can genuinely afford.

Over time, automated contributions can help build an emergency fund, prepare for a specific purchase or support a longer-term goal. They also place the money slightly further out of reach, reducing the temptation to spend it impulsively.

Preparing for the Costs That Do Not Arrive Monthly

Not every expense fits neatly into a monthly budget.

Christmas, holidays, car maintenance, insurance renewals and home repairs can all feel unexpected, despite being reasonably predictable.

Creating separate savings pots and making regular transfers into them can turn one large future bill into a series of smaller, more manageable amounts.

This does not necessarily reduce the overall cost, but it can reduce the financial shock when payment is due.

It can also make spending more enjoyable. A holiday paid for from money deliberately set aside may feel very different from one followed by several months of credit card repayments.

Automating Long-Term Saving and Investing

Regular contributions can also support longer-term financial planning.

Making contributions at set intervals removes the pressure of trying to identify the perfect moment to invest. Markets will naturally rise and fall, and regular investing means money is added across a range of different market conditions.

However, investments can fall as well as rise, and regular contributions do not guarantee a positive return. The amount invested, the level of risk and the investments selected should remain appropriate for your circumstances and goals.

Automation should support a considered financial plan, not replace one.

Making More of a Pay Rise

A pay rise is another point at which automation can be useful.

As income increases, spending often rises with it. This is sometimes known as lifestyle inflation. It may happen gradually, without us consciously deciding to change how we live.

Before becoming accustomed to the full increase, some people choose to direct a proportion of it towards savings, pensions or investments.

That still leaves room to enjoy the benefits of earning more, while also using part of the increase to strengthen future financial security.

What Should Not Be Left on Autopilot?

Automation can be helpful, but it should not mean ignoring your finances completely.

Direct Debits can continue long after a service has stopped providing value. Savings accounts can become uncompetitive. Insurance policies may no longer reflect your needs, and investment arrangements should be reviewed as circumstances and objectives change.

Credit card payments also require particular care. Automatically paying only the minimum amount can keep an account technically up to date while allowing interest and debt to build over time.

A sensible approach is to automate the regular activity, then review the wider arrangements periodically.

Think of it less as switching your finances off and more as installing a system that still requires occasional maintenance.

Small Systems, Repeated Over Time

Financial progress rarely comes from one dramatic decision.

More often, it is the result of small actions repeated consistently over many years.

Automating bills, savings and long-term contributions cannot remove every financial concern. Nor can it compensate for a budget that is already stretched beyond what is affordable.

But where there is room to save, it can make positive habits easier to maintain and reduce the likelihood that important goals are continually postponed.

Banner Template

A Fantastic Day at the Digby Associates Family Fun Day

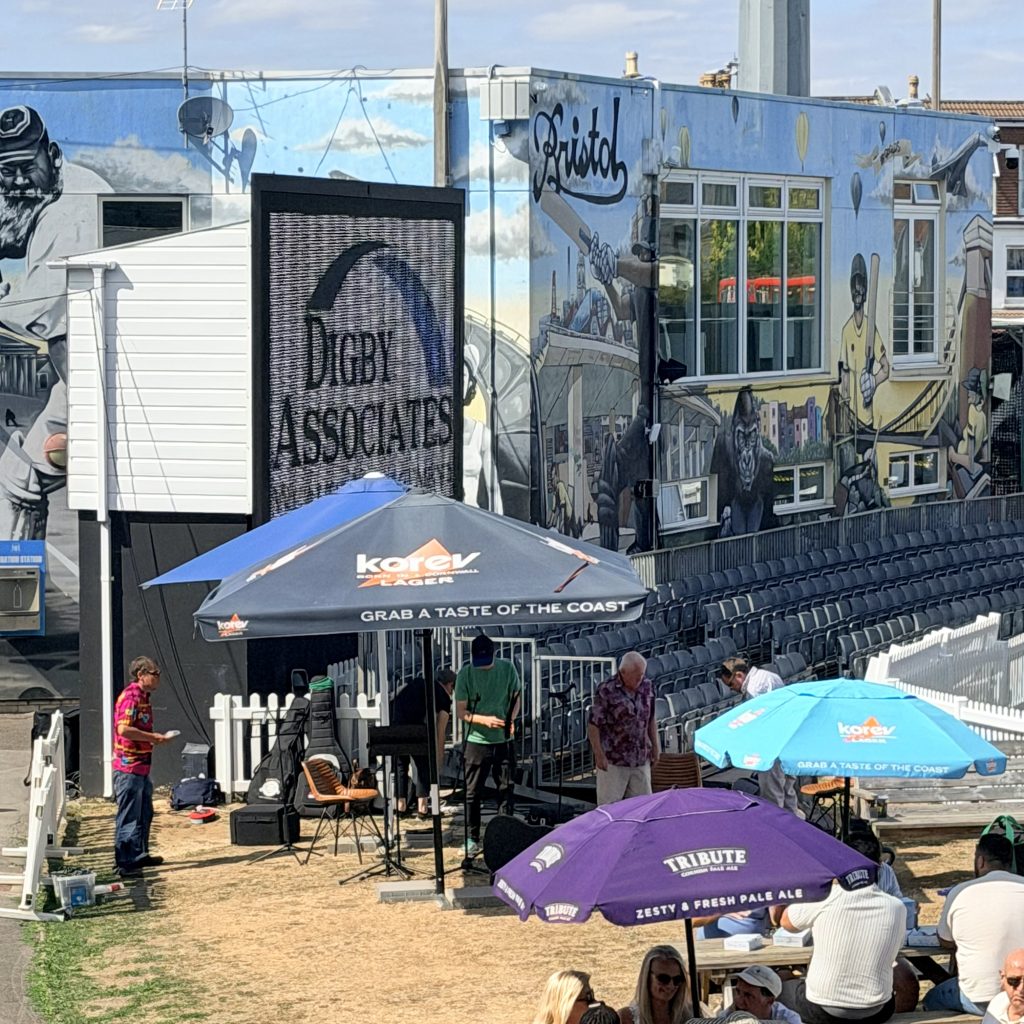
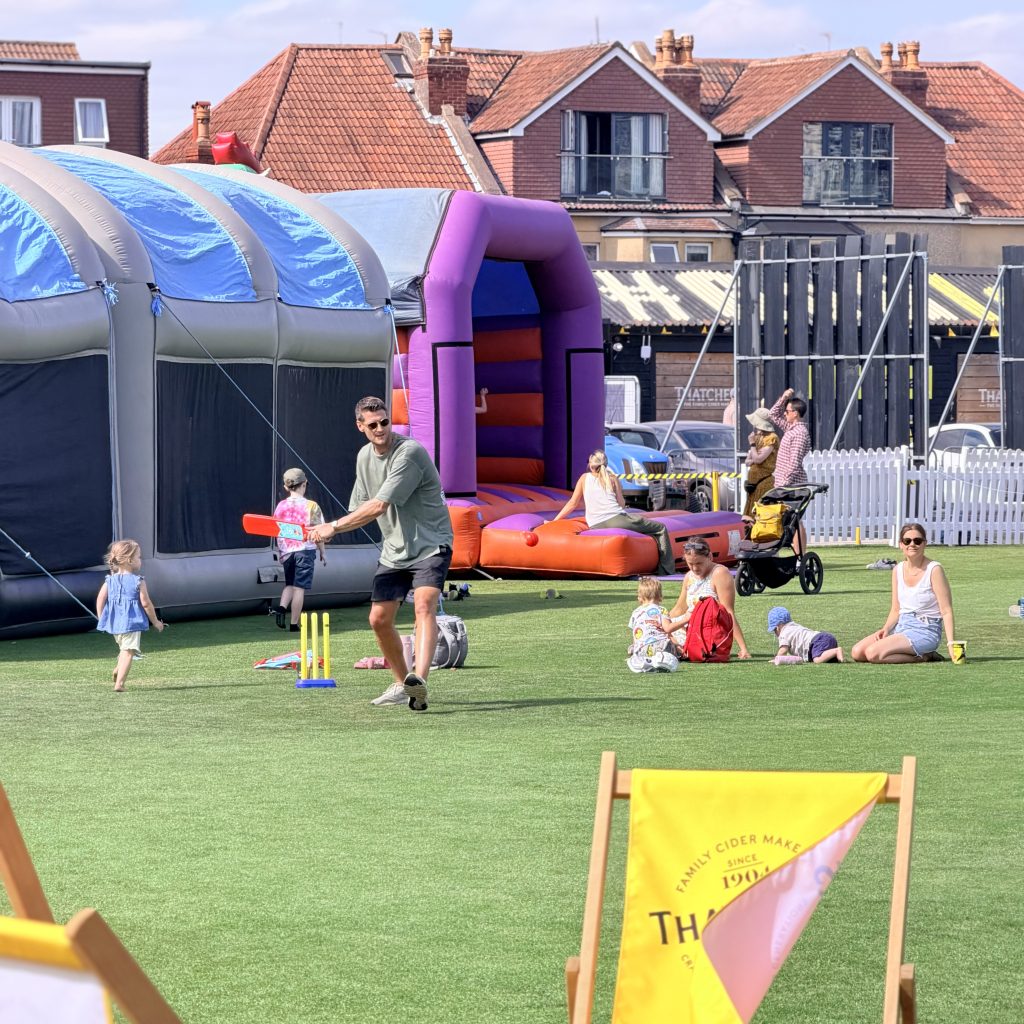
There is something special about bringing people together away from the office, and this year’s Digby Associates Family Fun Day was exactly that.

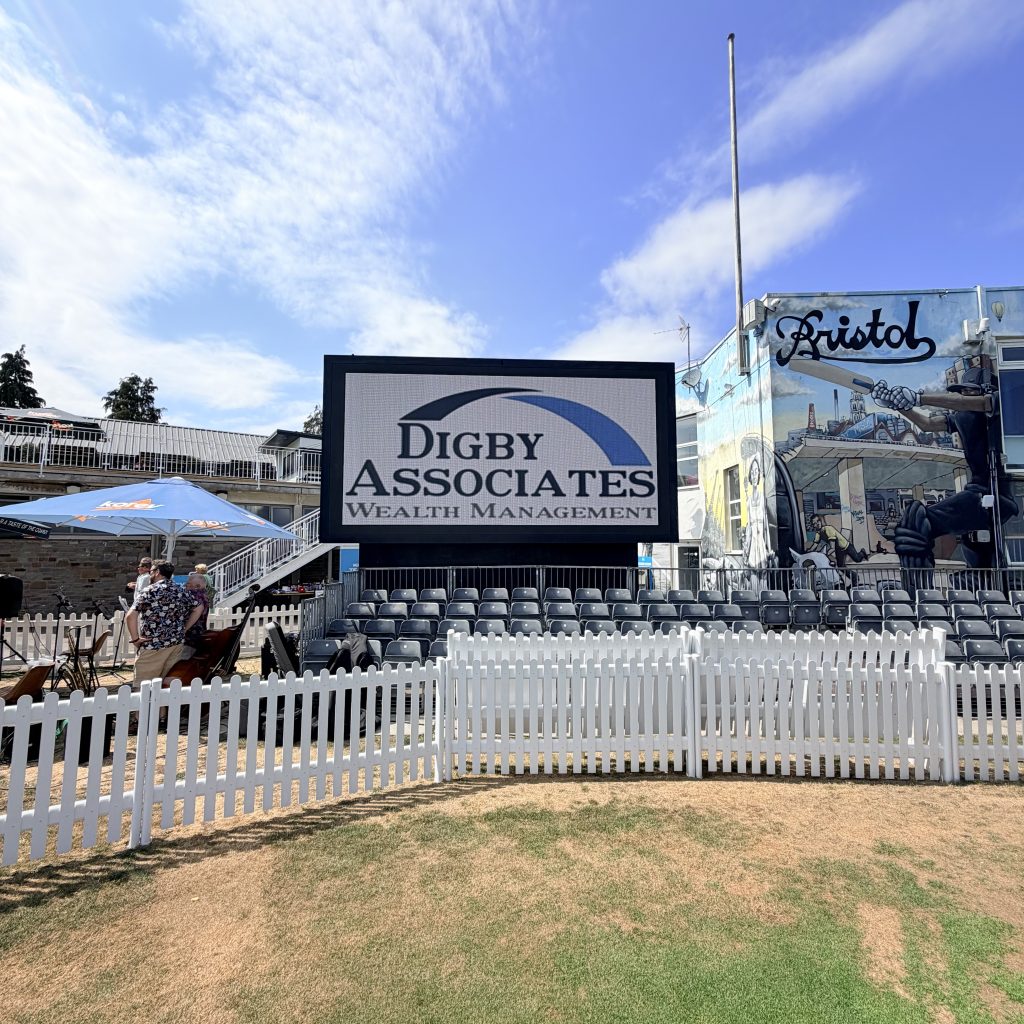
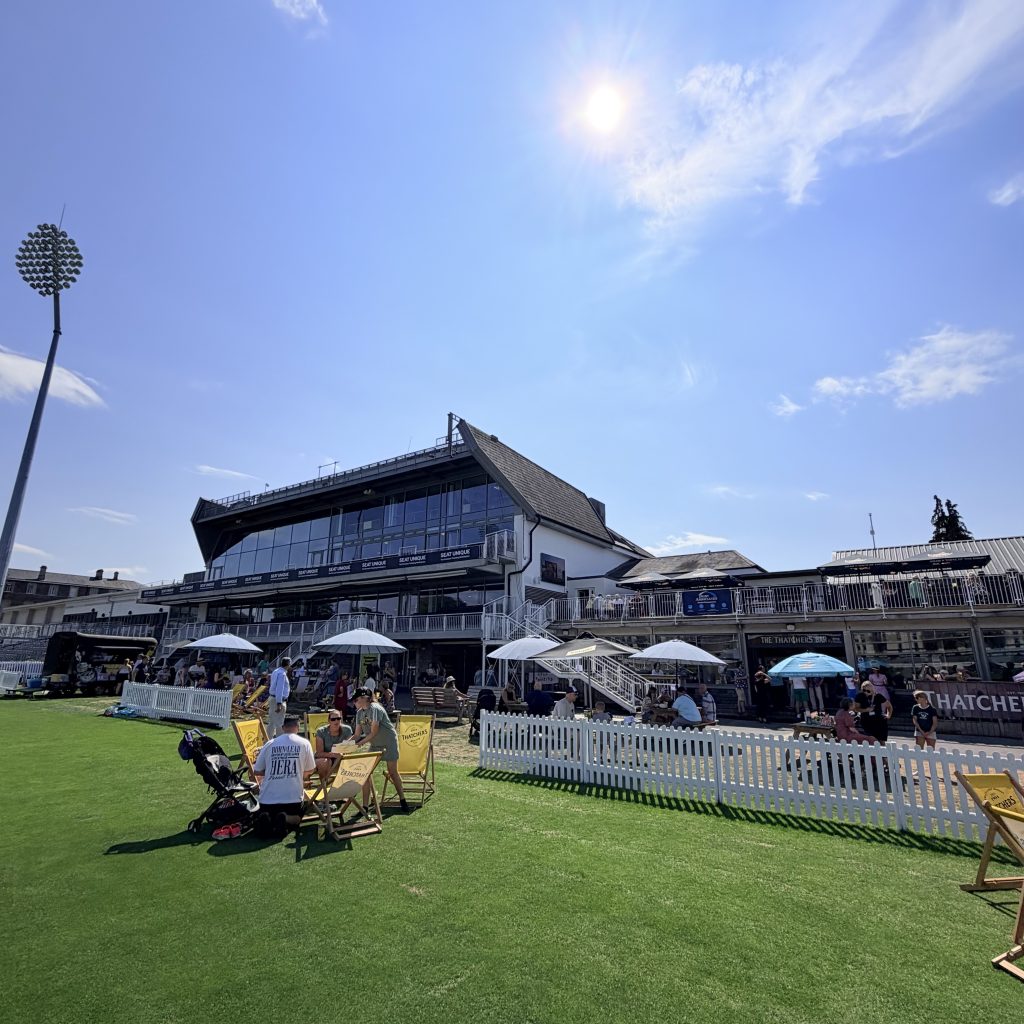
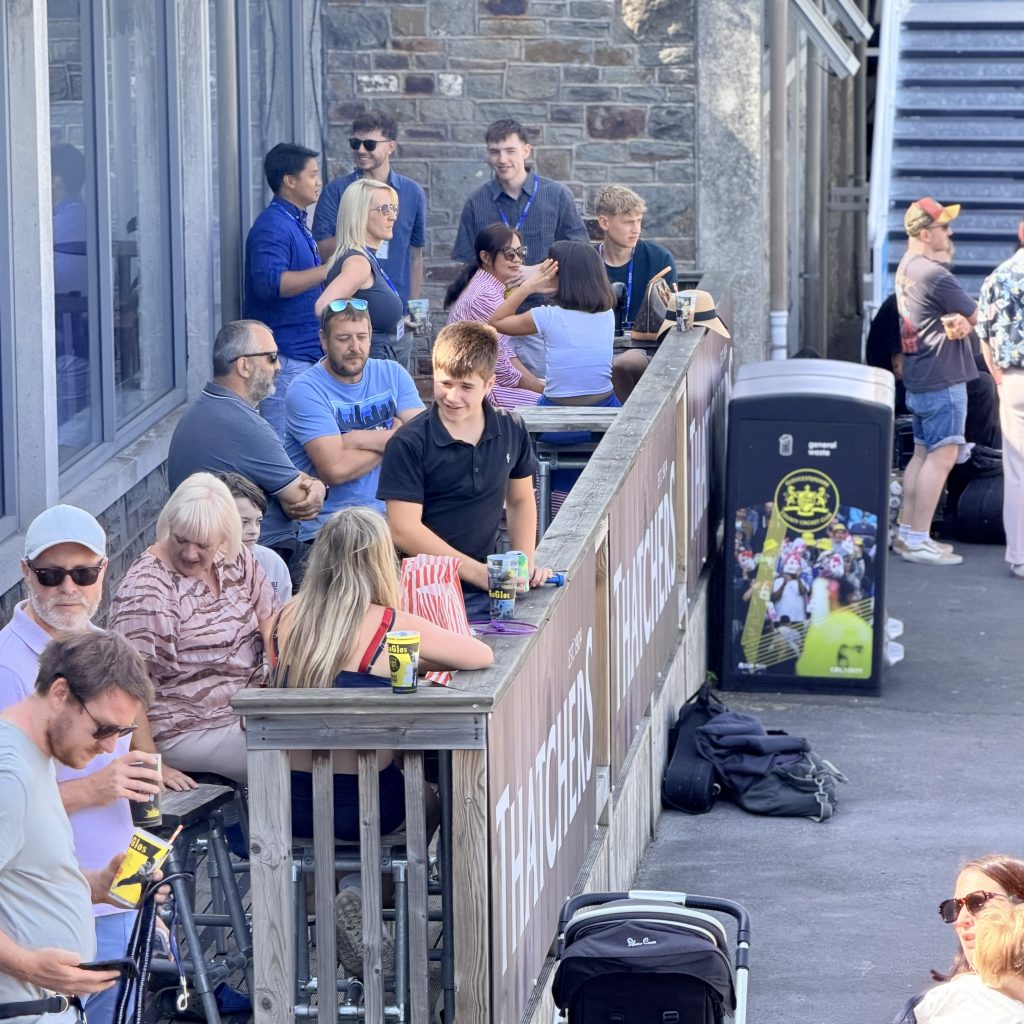
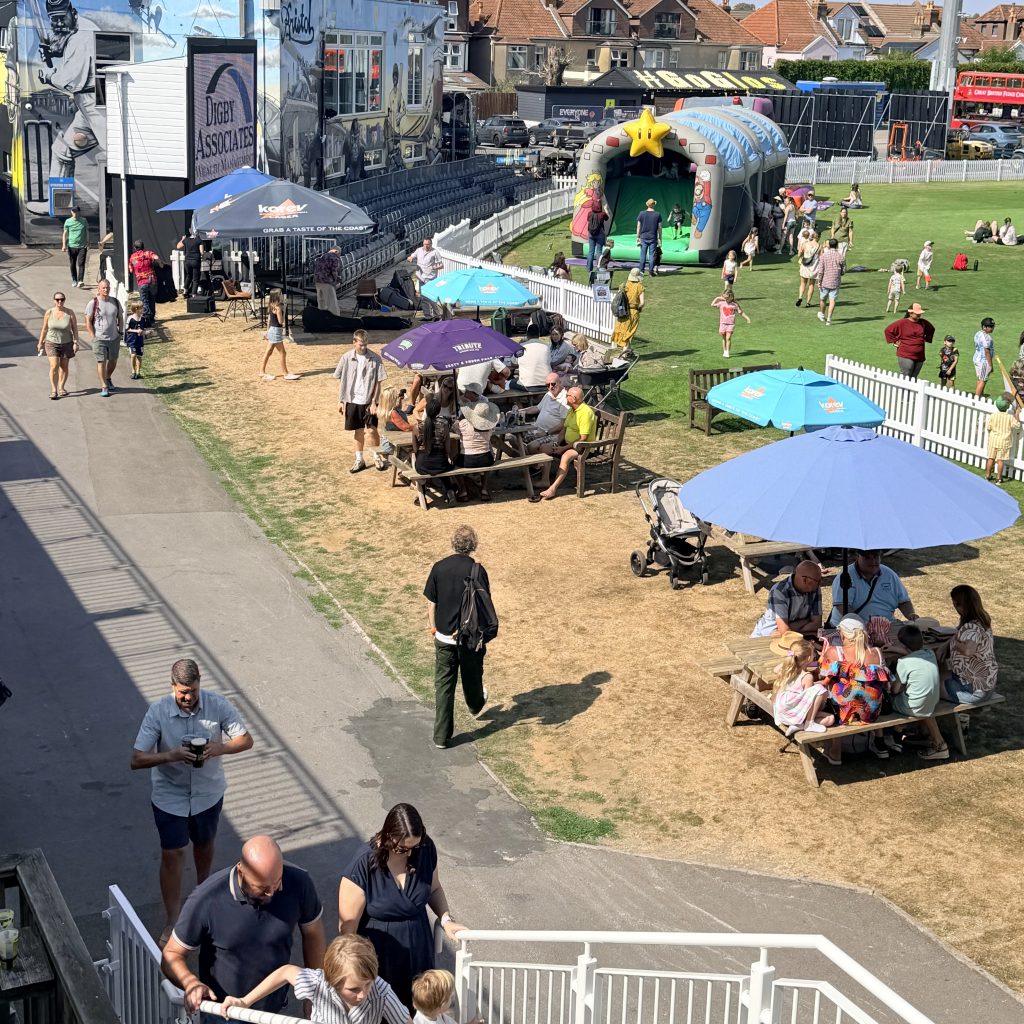
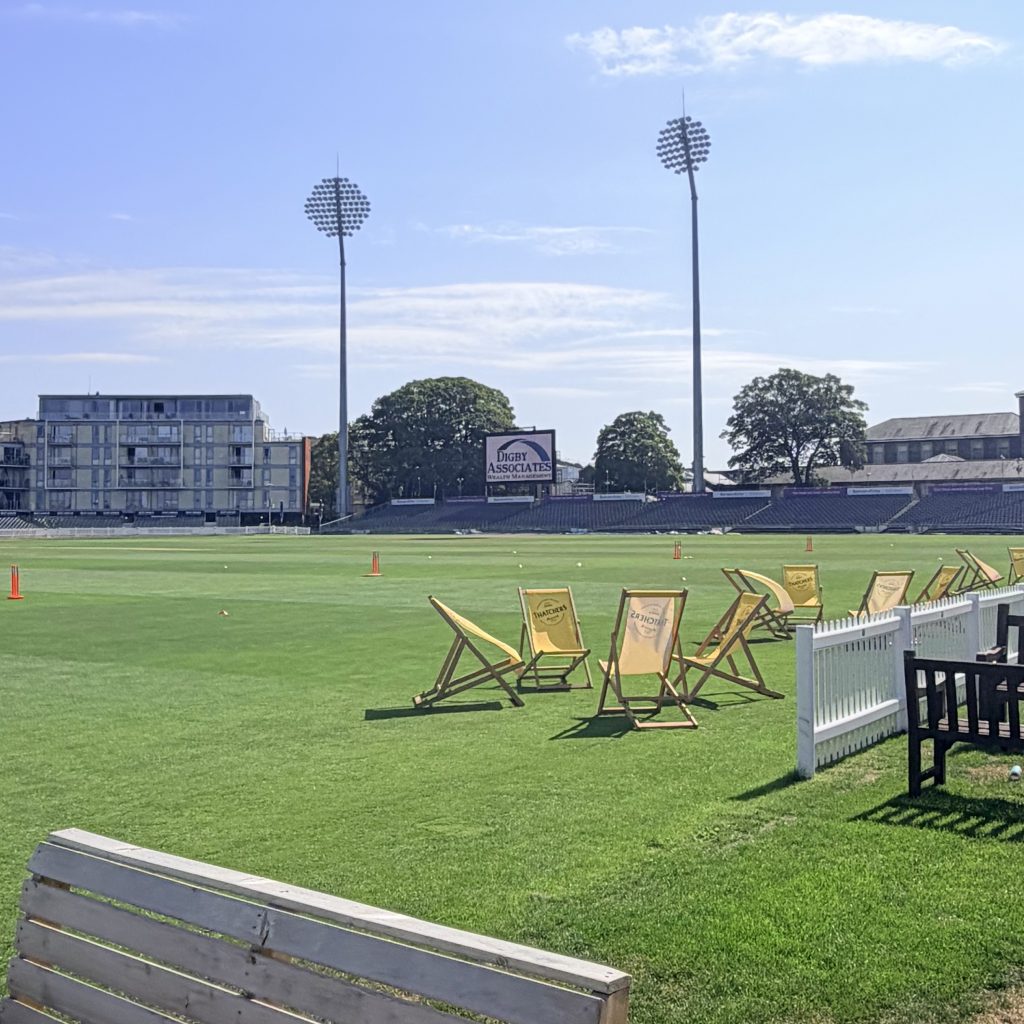
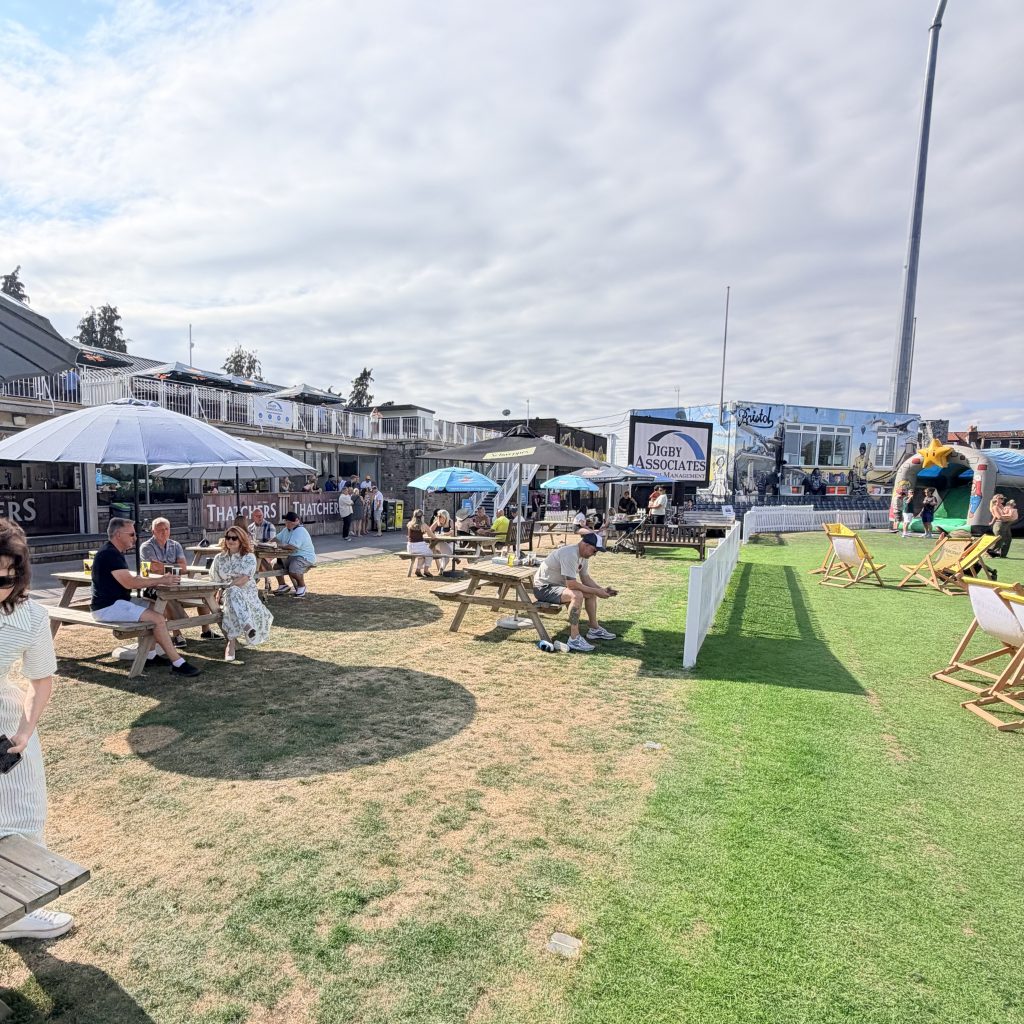
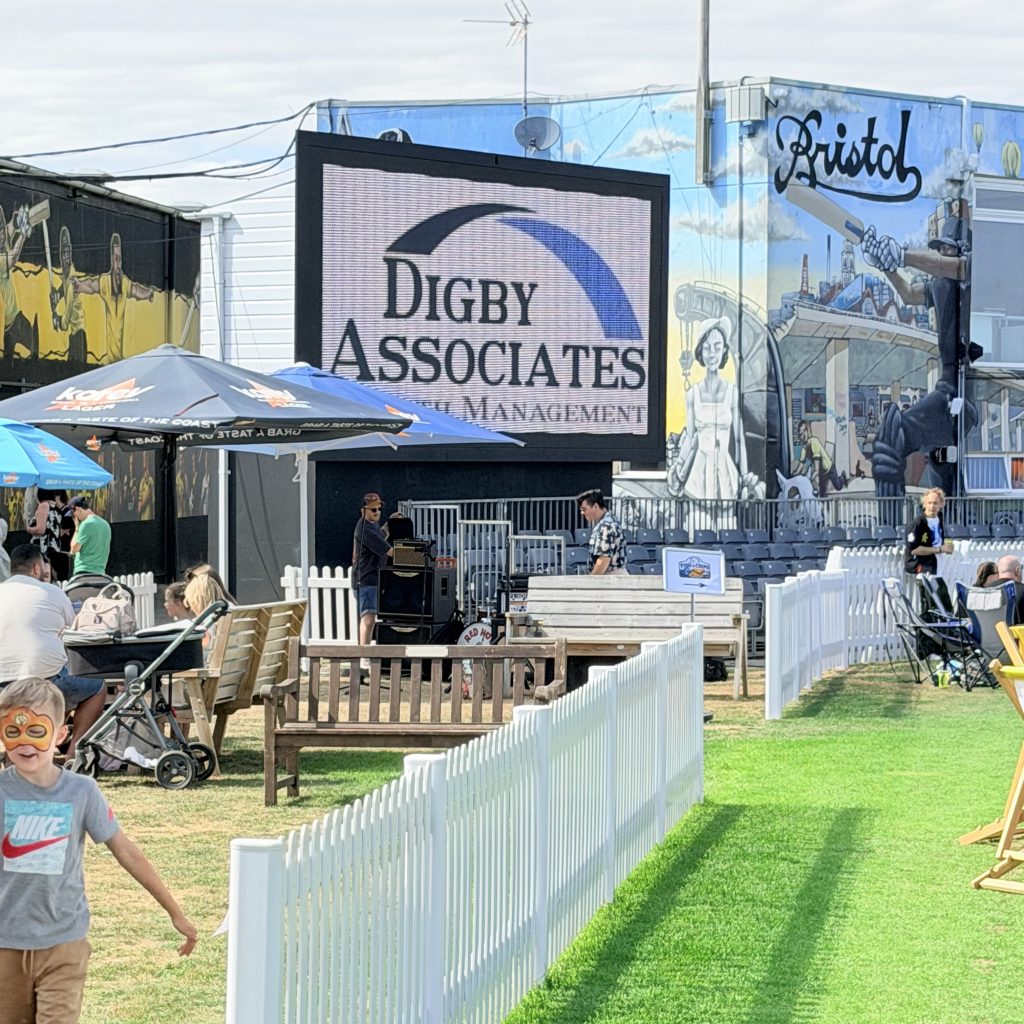
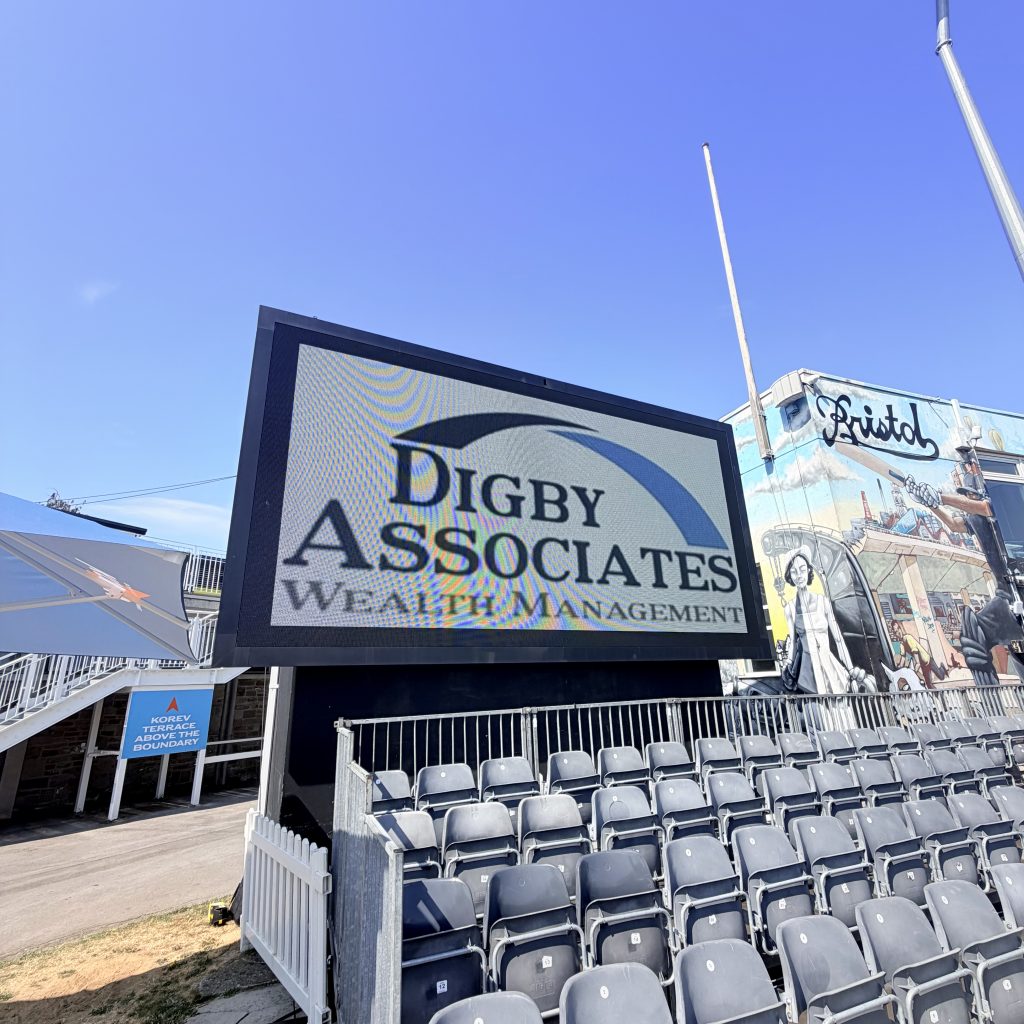
Held at the beautiful Gloucestershire County Cricket Club on Saturday, the Family Fun Day was organised to raise money for good causes while bringing together colleagues, clients, friends and families for an afternoon of fun. It was a fantastic opportunity to catch up with familiar faces, make new memories and support an important cause at the same time.

With glorious weather, a fantastic atmosphere and activities for all ages, it proved to be a wonderful celebration of the people who make Digby Associates what it is.

Bringing People Together

Whether we’re supporting clients through important financial decisions or working together as colleagues, those relationships are built on trust, conversation and genuine care.

Our Family Fun Day was a chance to celebrate those values outside the workplace, bringing together the charity partners, the wider Digby Associates family in a relaxed and enjoyable setting.

It was fantastic to see so many people there, from young children enjoying the activities to colleagues and clients taking the opportunity to catch up over food and refreshments.

Plenty to Enjoy

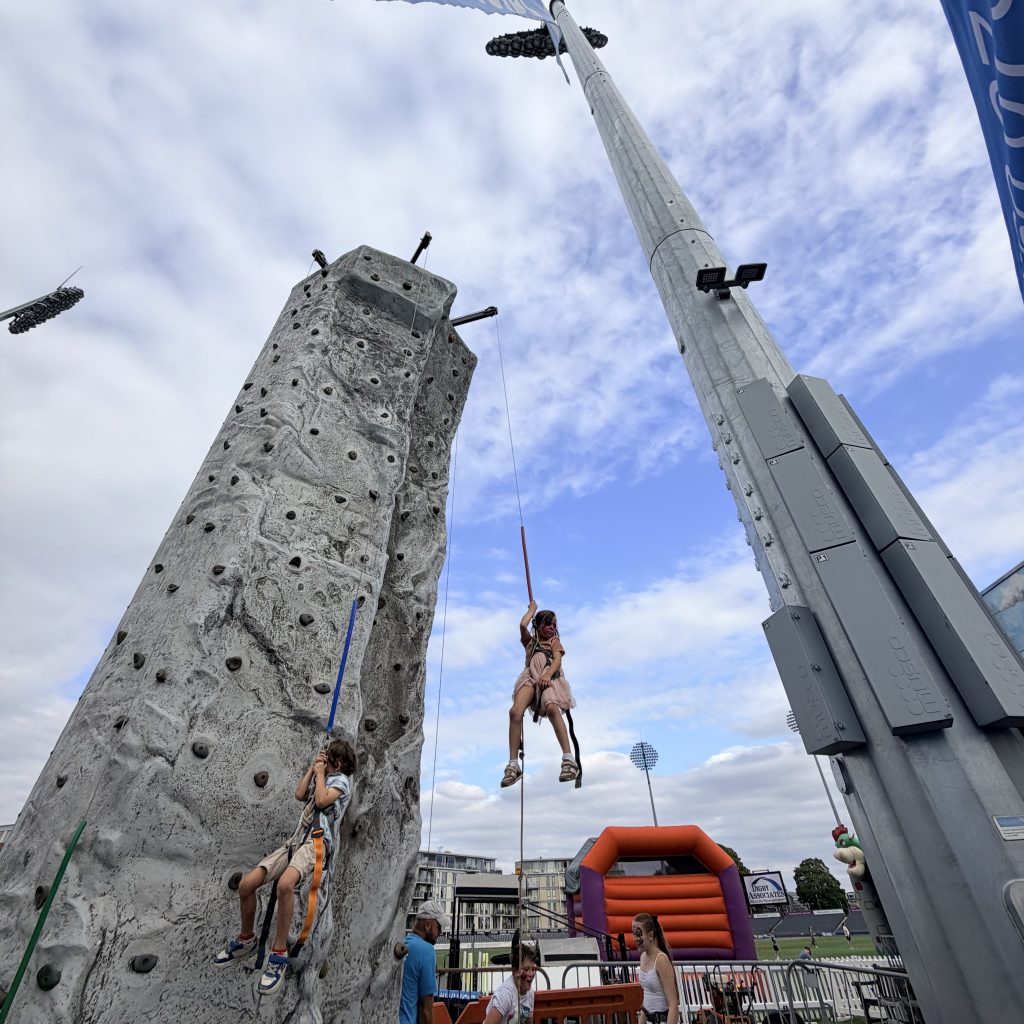
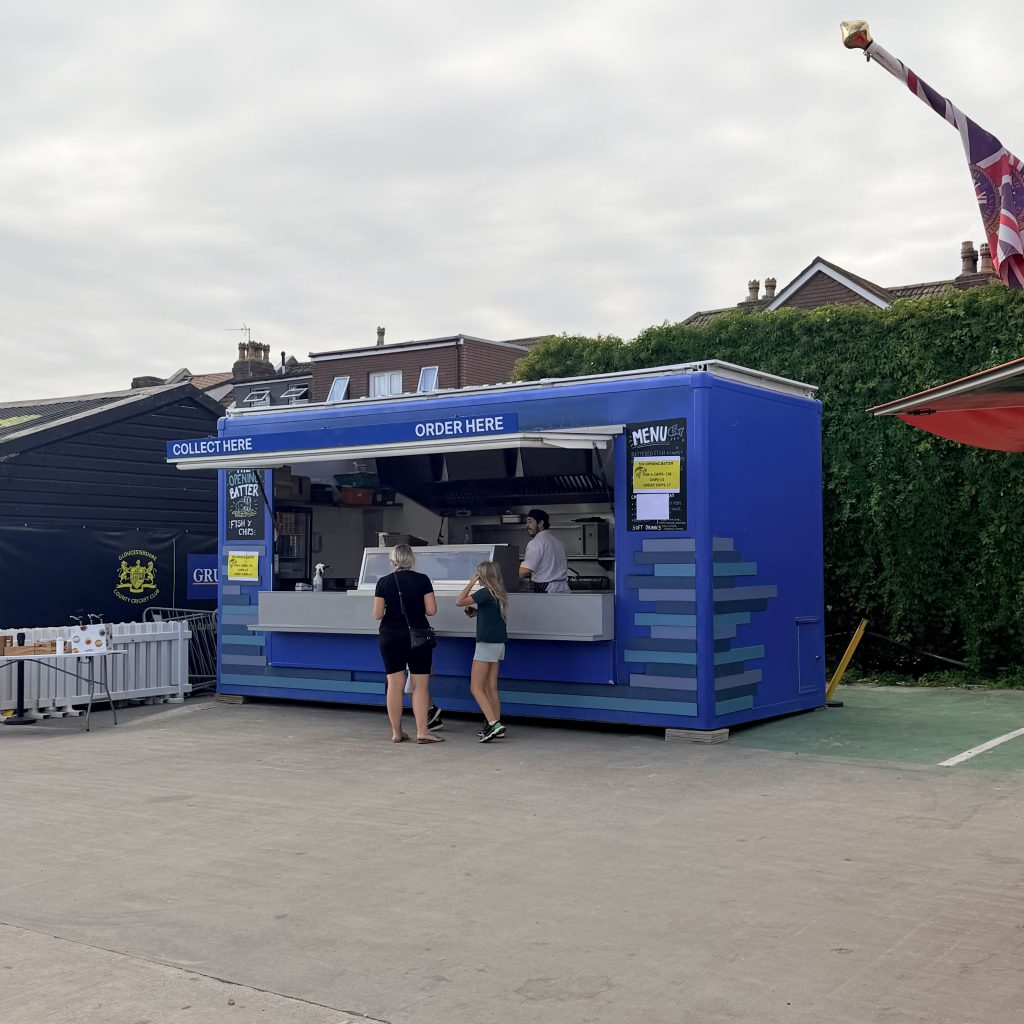
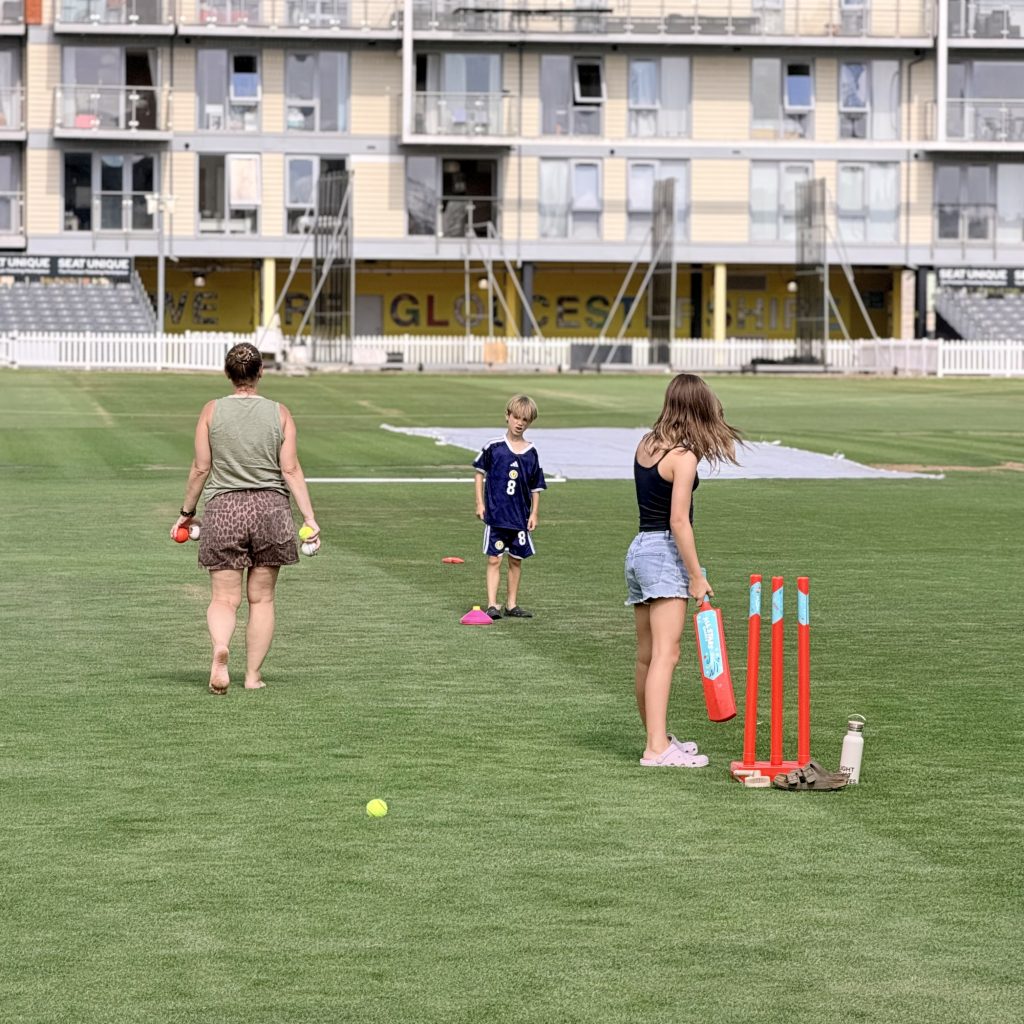
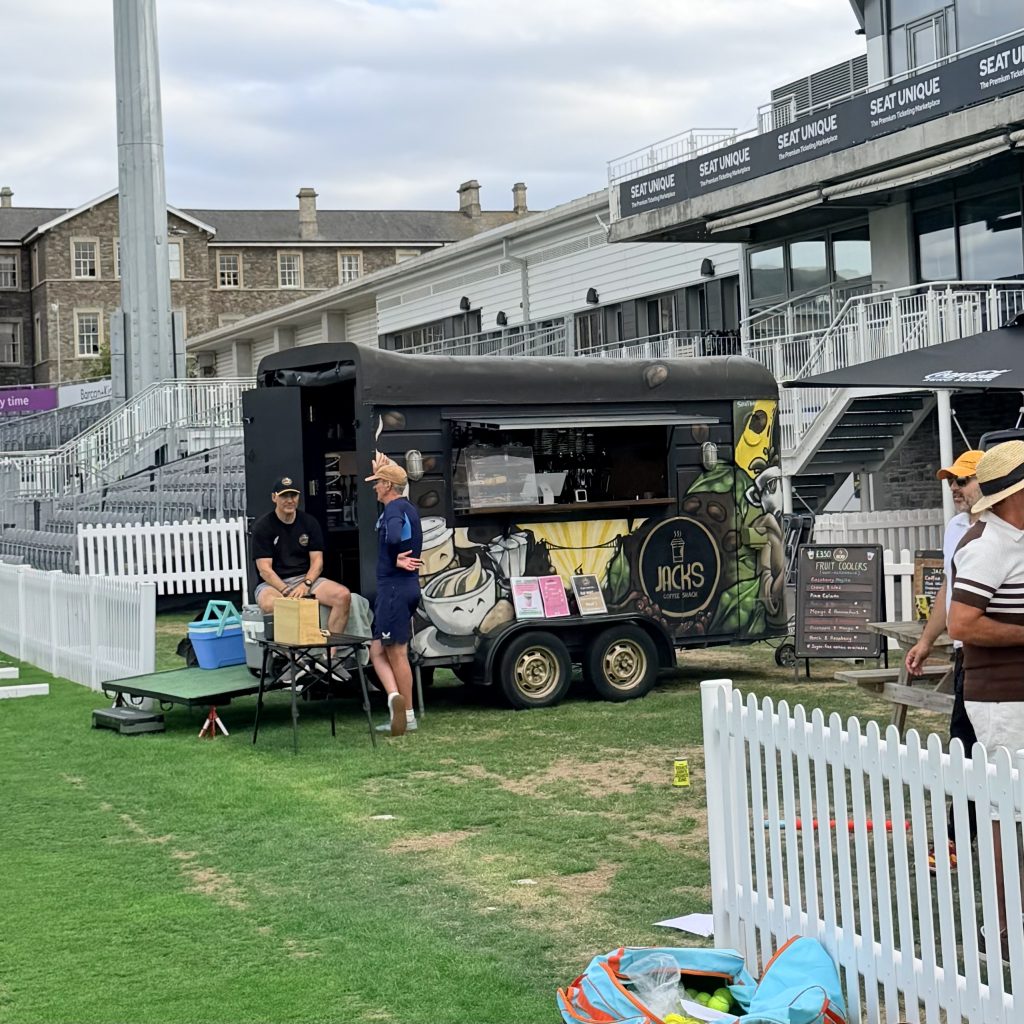
This year we had a really fantastic mix of activities, including Jack’s Coffee Stand, the Fudge Bus from Great British Fudge Company, a climbing wall from Mojo Active, as well as bouncy castles, face painting, a charity raffle with prizes donated by Digby Associates and partner businesses, live music from a local band and plenty of casual cricket activities.

Families enjoyed a wide range of activities, children embraced every opportunity to play, and there was plenty of laughter from start to finish. Gloucestershire County Cricket Club provided the perfect backdrop for the event, creating a relaxed setting where everyone could enjoy the afternoon at their own pace.

Thank You

A huge thank you to everyone who came along and helped make the day such a success.

Thank you also to everyone behind the scenes who organised the event, our charity partners, local businesses that got involved and to Gloucestershire County Cricket Club for being such fantastic hosts.

We hope everyone had as much fun as we did.

Take a look through some of the moments from the day in the gallery below.

Chaise Longue

The Psychology of Financial Confidence

What does it mean to feel financially confident?

For some people, it means having enough savings to deal with an unexpected bill. For others, it is knowing they can retire comfortably, support their family or make a major decision without worrying about every possible outcome.

It is tempting to assume that confidence simply increases as wealth grows. In reality, the relationship is more complicated.

Someone with considerable savings and investments may still worry constantly about running out of money. Another person with more modest resources may feel calm because they understand their position, have a plan and know what they can afford.

Financial confidence is therefore not simply about how much money you have. It is also about how much clarity, control and trust you feel you have over it.

Knowing the Numbers Is Only Part of It

Financial knowledge is valuable. Understanding pensions, savings, investments, mortgages and tax can help us make more informed decisions.

But knowledge alone does not always create confidence.

Many people know they should review their pension, build an emergency fund or organise their finances, yet still avoid doing so. The problem is not necessarily a lack of information. Sometimes the subject feels too complicated, the choices seem overwhelming or there is a fear of discovering something uncomfortable.

Avoidance can then create a cycle. The longer we put something off, the less in control we feel. The less in control we feel, the harder it becomes to take the first step.

Psychologists sometimes describe our belief in our ability to handle a task as self-efficacy. Applied to money, financial self-efficacy is the belief that we can understand our position, make decisions and respond to setbacks without becoming overwhelmed.

This matters because confidence often grows through action, not before it.

Confidence Comes From Clarity

Uncertainty has a habit of filling the space where facts are missing.

Someone approaching retirement may worry that they do not have enough, without knowing what their expected expenditure will be or how their different sources of income fit together. A parent may feel unable to help their children financially because they have never explored what level of gifting would remain affordable. An investor may become anxious during a market fall because they are unclear about why their portfolio was structured in a particular way.

In each case, the worry may be understandable, but it is being shaped partly by unanswered questions.

A clear financial plan cannot remove every uncertainty. Markets will fluctuate, tax rules can change and life rarely follows a perfectly predictable path.

What planning can do is replace vague fear with a clearer view of the options.

There is an important psychological difference between thinking, “I hope I will be all right,” and knowing, “We have considered several possible outcomes and have a plan for each of them.”

Small Decisions Build Confidence

Financial confidence is rarely created by one dramatic decision.

More often, it develops through small actions that demonstrate progress and control. Reviewing household spending, setting up a regular saving habit, consolidating old paperwork or having an overdue conversation about retirement can all make finances feel more manageable.

These actions provide evidence that we are capable of dealing with our money.

Over time, that sense of progress can become self-reinforcing. Greater confidence makes it easier to engage with financial decisions, and regular engagement creates greater clarity.

This does not mean every decision will be perfect. Financial confidence is not the belief that nothing will ever go wrong. It is the belief that if circumstances change, you will be able to understand the problem, seek help and adjust your plans.

Confidence Is Not the Same as Certainty

There is also an important difference between healthy financial confidence and overconfidence.

Healthy confidence involves understanding both what you know and what you do not. It allows room for questions, second opinions and changing course when new information becomes available.

Overconfidence can do the opposite. It may encourage people to underestimate risk, trade investments too frequently, chase recent performance or assume that a run of good results proves they can predict what happens next.

The goal is therefore not maximum confidence. It is well-calibrated confidence.

That means feeling sufficiently informed to make decisions, while remaining realistic about uncertainty and the limits of our knowledge.

Why Comparison Can Undermine Confidence

Money is deeply personal, but modern life makes it difficult to avoid comparison.

We see other people’s homes, holidays, cars and career milestones, usually without seeing the debt, anxiety or difficult choices sitting behind them. Social media can make financial success appear more common, more effortless and more immediate than it really is.

This can distort our sense of progress.

A financial plan built around someone else’s life is unlikely to create lasting confidence. The more useful questions are personal ones. What matters to you? What are you trying to achieve? What level of risk feels appropriate? What would make you feel secure?

Confidence tends to grow when financial decisions are connected to clear personal priorities rather than external expectations.

The Value of Another Perspective

One of the most valuable roles of a financial adviser is not simply to provide information. It is to help people interpret that information in the context of their own lives.

During uncertain periods, it can be difficult to separate a genuine financial problem from an understandable emotional reaction. A trusted adviser can step back, test assumptions and show how different decisions might affect the wider plan.

Sometimes advice identifies an action that needs to be taken. At other times, its greatest value is demonstrating that the plan remains on track and that no immediate change is required.

Reassurance is not about pretending risks do not exist. It comes from understanding those risks and knowing they have been considered properly.

Confidence Is Built, Not Bought

Greater wealth can create more choices, but it does not automatically create peace of mind.

Financial confidence comes from understanding what you have, knowing what it needs to achieve and having a plan that can adapt as life changes.

It is built through clear information, realistic expectations, regular decisions and the willingness to ask for help when it is needed.

holiday spending

Holiday Money This Summer: How Exchange Rates Could Affect Your Spending Abroad

For many of us, the countdown to a summer holiday is well underway. Flights are booked, accommodation is sorted and the suitcase is waiting to be packed.

But before heading to the airport, there is one factor that can have a surprisingly big impact on the overall cost of your trip: the exchange rate.

Even relatively small movements in the value of the pound can affect how much spending money you have once you arrive, influencing everything from restaurant meals and excursions to shopping and everyday purchases.

What Has Been Happening to the Pound?

The good news for UK holidaymakers is that sterling has been relatively resilient in recent weeks.

Against the US dollar, the pound has strengthened to around $1.34, close to its highest levels of the year, helped by changing expectations around interest rates and the wider economic outlook.

The pound has also remained relatively firm against the euro, trading at around EUR 1.17 in recent weeks.

While exchange rates move every day, a stronger pound means British travellers may find their holiday money goes slightly further than it did earlier in the year.

Why Exchange Rates Matter

Exchange rates determine how much foreign currency you receive for every pound you exchange.

Imagine you are taking £1,000 on holiday.

If the exchange rate moves from EUR 1.10 to EUR 1.17, the same £1,000 would give you around EUR 70 more to spend.

That could cover a couple of meals out, a family excursion or a few extra holiday treats.

Small movements in exchange rates can therefore make a noticeable difference, particularly for families travelling abroad.

It Is Not Just About Europe

The strength of the pound also affects holidays further afield.

Travellers visiting the United States, parts of the Caribbean or destinations where prices are linked to the US dollar may also benefit when sterling strengthens.

However, exchange rates are only one part of the picture.

Higher local prices in some destinations mean hotels, restaurants and attractions may still cost more than they did a year or two ago, even if the exchange rate has improved.

Should You Buy Currency Now or Wait?

This is one of the most common questions holidaymakers ask.

The honest answer is that nobody knows exactly where exchange rates will move next.

Currencies respond to a wide range of factors, including inflation, interest rates, economic growth and political developments. Trying to perfectly time the market is therefore extremely difficult.

Instead, some people choose to spread the risk by exchanging part of their money in advance and buying more closer to departure.

Whatever approach you take, it is worth comparing providers. Exchange rates can vary significantly, and the rate available online is often better than the one offered at the airport.

A Few Ways to Make Your Money Go Further

Exchange rates are only one part of holiday spending.

When using a debit or credit card abroad, it is usually better to choose to pay in the local currency rather than pounds sterling. This can help you avoid less favourable conversion rates applied by the retailer or payment terminal.

It is also worth checking whether your bank charges overseas transaction fees. Some accounts offer fee-free spending abroad, while others add a charge each time you use your card.

Leaving all your currency exchange until you reach the airport can also be expensive, as airport exchange desks often offer less competitive rates.

Looking Beyond the Holiday

Exchange rates do not only affect holidays.

They can also influence the price of imported goods, overseas investments and international business activity. Changes in the value of sterling can eventually affect inflation and the cost of everyday products in the UK.

For holidaymakers, however, the impact is much more immediate.

A stronger pound means your spending money can stretch further. A weaker pound means the same holiday may cost more.

Final Thoughts

Exchange rates may not be the first thing you think about when planning a holiday, but they can make a meaningful difference to your overall budget.

Nobody can predict exactly where currencies will move over the coming weeks. However, understanding how exchange rates work, comparing providers and checking card charges before you travel can help you make the most of your money.

After all, if a favourable exchange rate means an extra meal by the sea, another family day out or simply a little less financial stress while you are away, it is worth paying attention before you fly.

Banner Template

Andy Burnham Is In: Five Things We’re Watching Closely

The headlines have focused on who has moved into Number 10. The more important story is what happens next.

Andy Burnham has now taken over as Prime Minister, bringing with him a fresh agenda centred on economic growth, devolution and investment across the UK. While leadership changes naturally dominate the headlines, history suggests it is the decisions made in the weeks and months that follow which have the greatest impact on households, businesses and investors.

Attention will soon turn from personalities to policy. The government’s first Budget, its approach to taxation and public spending, support for businesses and plans to encourage investment will all help shape the economic outlook.

Here are five areas we’ll be watching particularly closely.

1. The First Budget

The first Budget is often the clearest indication of a new government’s priorities.

While election campaigns provide broad direction, Budgets reveal where governments intend to spend money, where they hope to raise revenue and which areas of the economy they want to support.

For households, this could include measures affecting taxation, pensions, inheritance tax, savings and property. For businesses, the focus may be on investment incentives, employment costs and economic growth.

The latest Budget announcements and supporting documents can be found via HM Treasury.

2. Whether Economic Growth Becomes a Reality

Economic growth remains one of the biggest challenges facing the UK economy.

Higher growth can support wages, improve public finances and create greater opportunities for businesses. However, generating sustainable growth is often easier said than done.

The new government has spoken about encouraging investment, improving productivity and supporting regional economies. Investors and businesses will be looking closely to see how these ambitions translate into practical policy.

Key economic data is published regularly by the Office for National Statistics (ONS), including GDP figures, employment data and business activity indicators.

3. Inflation and Interest Rates

Although the government does not directly control interest rates, its policies can influence inflation, market confidence and economic expectations.

Following several years of elevated inflation and higher borrowing costs, many households continue to feel the impact through mortgage payments, household bills and day-to-day spending.

The Bank of England remains responsible for setting interest rates, with decisions based on inflation and broader economic conditions. Markets will be watching closely to see whether government policy supports a stable environment for future rate reductions.

The latest inflation figures are available from the Office for National Statistics Inflation Hub, while interest rate decisions can be found on the Bank of England Bank Rate page.

4. Regional Investment and Devolution

One area where Andy Burnham has built much of his reputation is regional growth and devolution.

As Mayor of Greater Manchester, he consistently argued that local areas should have greater control over transport, housing, skills and economic development.

It will be interesting to see whether this philosophy is applied more broadly across the UK.

For businesses and communities outside London, greater regional investment could create opportunities through infrastructure projects, regeneration programmes and local economic development initiatives.

Progress on major infrastructure and regional investment projects can be monitored through UK Government announcements.

5. Tax and Wealth Planning

For many Digby Associates clients, one of the most important areas to watch will be tax and wealth planning.

Inheritance tax, pension legislation, capital gains tax, business taxation and property-related taxes all have the potential to influence long-term financial plans.

Even where no immediate changes are announced, governments often signal future policy direction well before legislation is introduced.

This makes regular financial reviews particularly valuable, ensuring plans remain aligned with both personal goals and the wider economic environment.

For independent analysis of government forecasts and public finances, the Office for Budget Responsibility (OBR)remains one of the most useful sources available.

Looking Beyond the Headlines

Political change naturally attracts attention, but for most households, businesses and investors, the real impact comes from the policies that follow rather than the personalities involved.

The coming months will provide a clearer picture of the new government’s economic priorities and how those priorities may affect the financial landscape.

As always, while headlines can create uncertainty, long-term financial planning is rarely about reacting to short-term political events. Instead, it is about understanding the changing environment, reviewing your plans regularly and remaining focused on your long-term objectives.

We’ll be watching closely.

ChatGPT Finances

ChatGPT Now Knows Your Finances. But Should It?

It’s well trodden that Artificial intelligence has been steadily finding its way into our everyday lives, helping us write emails, plan holidays, answer questions and even organise our schedules.

Now it is taking a significant step into personal finance.

OpenAI recently launched a new personal finance experience in the United States that allows ChatGPT to connect securely to financial accounts and provide insights based on a user’s actual spending, savings and investments. Rather than answering general questions about money, it can analyse real financial data and help users understand their finances in far greater detail.

It’s an impressive development.

But it also raises an interesting question:

When does financial guidance become financial advice?

A New Financial Assistant

For many people, managing money can feel overwhelming.

Bank accounts, pensions, savings, investments, mortgages, insurance policies and tax rules all compete for attention. It’s no surprise that many consumers are looking for tools that can help them make sense of it all.

The appeal of AI is obvious.

Imagine asking questions such as:

“How much did I spend on eating out last month?”

“Could I save more each month?”

“How close am I to reaching my savings goal?”

“Where is most of my money going?”

These are exactly the kinds of tasks AI can perform extremely well. It can organise information, identify patterns and present data in a way that is easy to understand.

For many people, that could be a genuinely useful step forward in improving financial awareness.

Better Information Is a Good Thing

There is no doubt that greater access to information can help people make better financial decisions.

Many of us have experienced the frustration of searching for answers to financial questions online, only to find conflicting opinions or pages of technical jargon.

AI has the potential to make financial information more accessible.

It can explain concepts such as ISAs, pensions, inheritance tax and investing in plain English. It can help people understand their spending habits and encourage more engagement with their finances.

In that respect, tools like ChatGPT could play an important role in improving financial literacy.

And that’s something to be welcomed.

But Money Is Rarely Just Maths

The challenge is that financial planning is rarely just about numbers.

Two people can have exactly the same income, savings and investments and still make completely different decisions.

Why?

Because financial decisions are influenced by far more than spreadsheets.

They are shaped by family circumstances, personal experiences, goals, fears and priorities.

One person may be worried about retiring too early.

Another may be concerned about funding future care costs.

A parent may be wondering how best to support their children financially.

A business owner may be deciding whether to invest in their company or focus on their own retirement plans.

These questions cannot be answered by looking at transaction data alone.

Information Versus Advice

This is where an important distinction exists.

Information is valuable.

Advice is personal.

An AI tool might tell you that you spent £500 on restaurants last month or that your pension contributions have increased over the past year.

What it cannot fully understand is why you are making those decisions or how they fit into your wider financial goals.

Good financial planning is often less about finding the “right” answer and more about understanding the trade-offs.

Should you help your children now or preserve more of your wealth for later life?

Should you retire next year or continue working for a few more years?

Should you take more investment risk or prioritise security?

These are personal decisions that depend on circumstances that rarely appear on a bank statement.

The Future Is Probably Both

The arrival of AI in personal finance does not mean advisers become less relevant.

If anything, it may make human advice more valuable.

As information becomes easier to access, the real challenge becomes interpretation. Understanding what matters, what doesn’t and how different decisions fit together remains where experienced advice can add significant value.

AI may become an excellent tool for organising financial information, highlighting trends and helping people engage more closely with their finances.

But financial planning has always been about more than data.

It is about helping people make confident decisions about their future.

Final Thoughts

The development of AI-powered financial tools is undoubtedly exciting.

Anything that helps people better understand their finances is likely to be a positive step.

But understanding your finances and deciding what to do about them are not always the same thing.

Technology can tell you where your money has been.

It can help explain rules, identify patterns and answer questions.

What it cannot fully understand are your ambitions, concerns, family circumstances and the things that matter most to you.

Perhaps that is where the future of financial planning lies.

Not AI versus advisers.

But AI and advisers working together, combining the power of technology with the judgement, experience and understanding that comes from human conversation.

house on hill

UK House Prices: Why Have They Been Moving Around So Much?

If you’ve been following the property market recently, you could be forgiven for feeling slightly confused.

One month, headlines suggest house prices are rising again. The next, reports point to falling values. Depending on which index you read, the market can appear to be moving in different directions altogether.

So what is actually happening to UK house prices?

The reality is that the market is currently being pulled in several different directions at once, with interest rates, mortgage affordability, housing supply and buyer confidence all playing a role.

The Numbers Don’t Always Agree

One reason for the apparent confusion is that different organisations measure house prices in different ways. The UK’s most widely reported house price indices, including those produced by the  ⁠Nationwide House Price Index, Halifax and the Office for National Statistics (ONS), all use different methodologies and datasets.

The UK’s most widely reported house price indices, including those produced by Nationwide, Halifax and the Office for National Statistics (ONS), all use different methodologies and datasets.

As a result, it is not unusual to see one index reporting modest growth while another reports a slight decline.

What they broadly agree on, however, is that the rapid house price growth seen during and immediately after the pandemic has slowed considerably.

Rather than a market experiencing dramatic rises or falls, many areas of the country are now seeing relatively modest movements in either direction.

Interest Rates Changed Everything

The biggest factor influencing the housing market over the past few years has been interest rates.

Between December 2021 and August 2023, the Bank of England increased Base Rate from 0.1% to 5.25% as it attempted to bring inflation under control. You can view the latest decisions and historical changes on the ⁠Bank of England’s Bank Rate page. While rates have since eased, borrowing costs remain significantly higher than many buyers became accustomed to during the ultra-low-rate era.

For many households, affordability has become the key issue.

Someone borrowing £300,000 at 2% faces very different monthly repayments to someone borrowing the same amount at 5%.

As a result, many buyers have had to reduce their budgets, which has naturally placed downward pressure on property values in some areas.

Mortgage Rates Are Beginning to Improve

There are signs that conditions may be becoming slightly more favourable.

As inflation has moved closer to the Bank of England’s target and expectations of future interest rate cuts have grown, many lenders have gradually reduced mortgage rates.

While mortgage costs remain higher than they were a few years ago, buyers today are generally facing better borrowing conditions than they were during the peak of the interest rate cycle.

This has helped support activity in the housing market and improve confidence among both buyers and sellers.

Supply and Demand Remain Uneven

The UK continues to face a long-term housing shortage.

Successive governments have struggled to build enough homes to meet demand, which provides some support for prices over the longer term.

However, property remains a highly local market.

While some regions continue to experience strong demand and limited supply, others are seeing a more balanced market where buyers have greater negotiating power.

This helps explain why house price trends can vary significantly depending on location.

The Stamp Duty Effect

Another factor influencing recent figures has been the ending of temporary Stamp Duty support measures.

Whenever tax incentives or policy changes are introduced, they often encourage buyers to bring purchases forward.

This can create a short-term surge in activity followed by a quieter period once the deadline passes.

As a result, some of the recent fluctuations in transaction levels and house price data may reflect timing effects rather than any fundamental change in the health of the housing market.

What About First-Time Buyers?

First-time buyers continue to face some of the greatest challenges.

Although wage growth has improved in recent years, higher mortgage rates mean affordability remains stretched in many parts of the country.

Saving for a deposit also remains difficult, particularly in areas where house prices significantly outpace average earnings.

At the same time, a more stable interest rate environment may gradually improve opportunities for those looking to enter the market over the coming years.

What Does This Mean for Homeowners and Investors?

For existing homeowners, the current market is very different from the one many experienced over the previous decade.

Double-digit annual price growth is no longer the norm.

Instead, the market appears to be returning to something closer to historical averages, where local economic conditions, affordability and housing supply play a greater role in determining prices.

For property investors, the environment has also become more complex. Higher borrowing costs, changes to tax rules and evolving rental regulations mean investment decisions require careful consideration.

Final Thoughts

The recent fluctuations in UK house prices are not the result of a single factor.

Instead, they reflect the interaction between higher borrowing costs, changing mortgage rates, housing supply constraints and shifting buyer confidence.

The good news is that the dramatic uncertainty seen immediately after interest rates began rising has started to ease.

While house prices may continue to move up and down from month to month, the bigger picture suggests a market that is gradually adjusting to a new normal, one where affordability matters more, borrowing costs remain important and long-term fundamentals continue to shape the direction of travel.